
What if the single biggest obstacle standing between your business and explosive revenue growth isn’t your pricing, but how you ask customers to pay? Every merchant knows the frustration of watching high-ticket deals evaporate because buyers hesitate over large upfront sums. Exploring the proven benefits of offering customer financing reveals a powerful shift: turning intimidating totals into accessible monthly installments removes purchase hesitation while keeping your sales pipeline moving forward.
You shouldn’t have to choose between closing high-value sales and protecting your balance sheet. In this guide, you’ll discover how point-of-sale customer financing eliminates checkout friction, lifts average ticket sizes, and protects merchant cash flow with zero credit risk. We will examine how multi-lender networks secure higher approvals, shift default liability entirely to third-party partners, and convert customer payment flexibility into your strongest revenue engine in 2026.
Key Takeaways
- Accelerate conversion rates and lift average order values by up to 15% by transforming intimidating sticker prices into accessible monthly installment plans.
- Uncover the core financial benefits of offering customer financing, which delivers full upfront funding within 24 hours while transferring non-payment and default liabilities entirely to third-party lenders.
- Win budget-conscious consumers across key sectors, enabling service providers like contractors to expand project scopes by 16% and close 21% more bids.
- Eliminate embarrassing customer declines by replacing rigid single-lender setups with multi-lender waterfall networks that connect buyers to up to 30 lending partners.
- Enhance your checkout experience with soft-check pre-qualifications that protect buyer credit scores while maintaining seamless operational momentum.
Core Revenue Drivers: How Offering Customer Financing Accelerates Sales
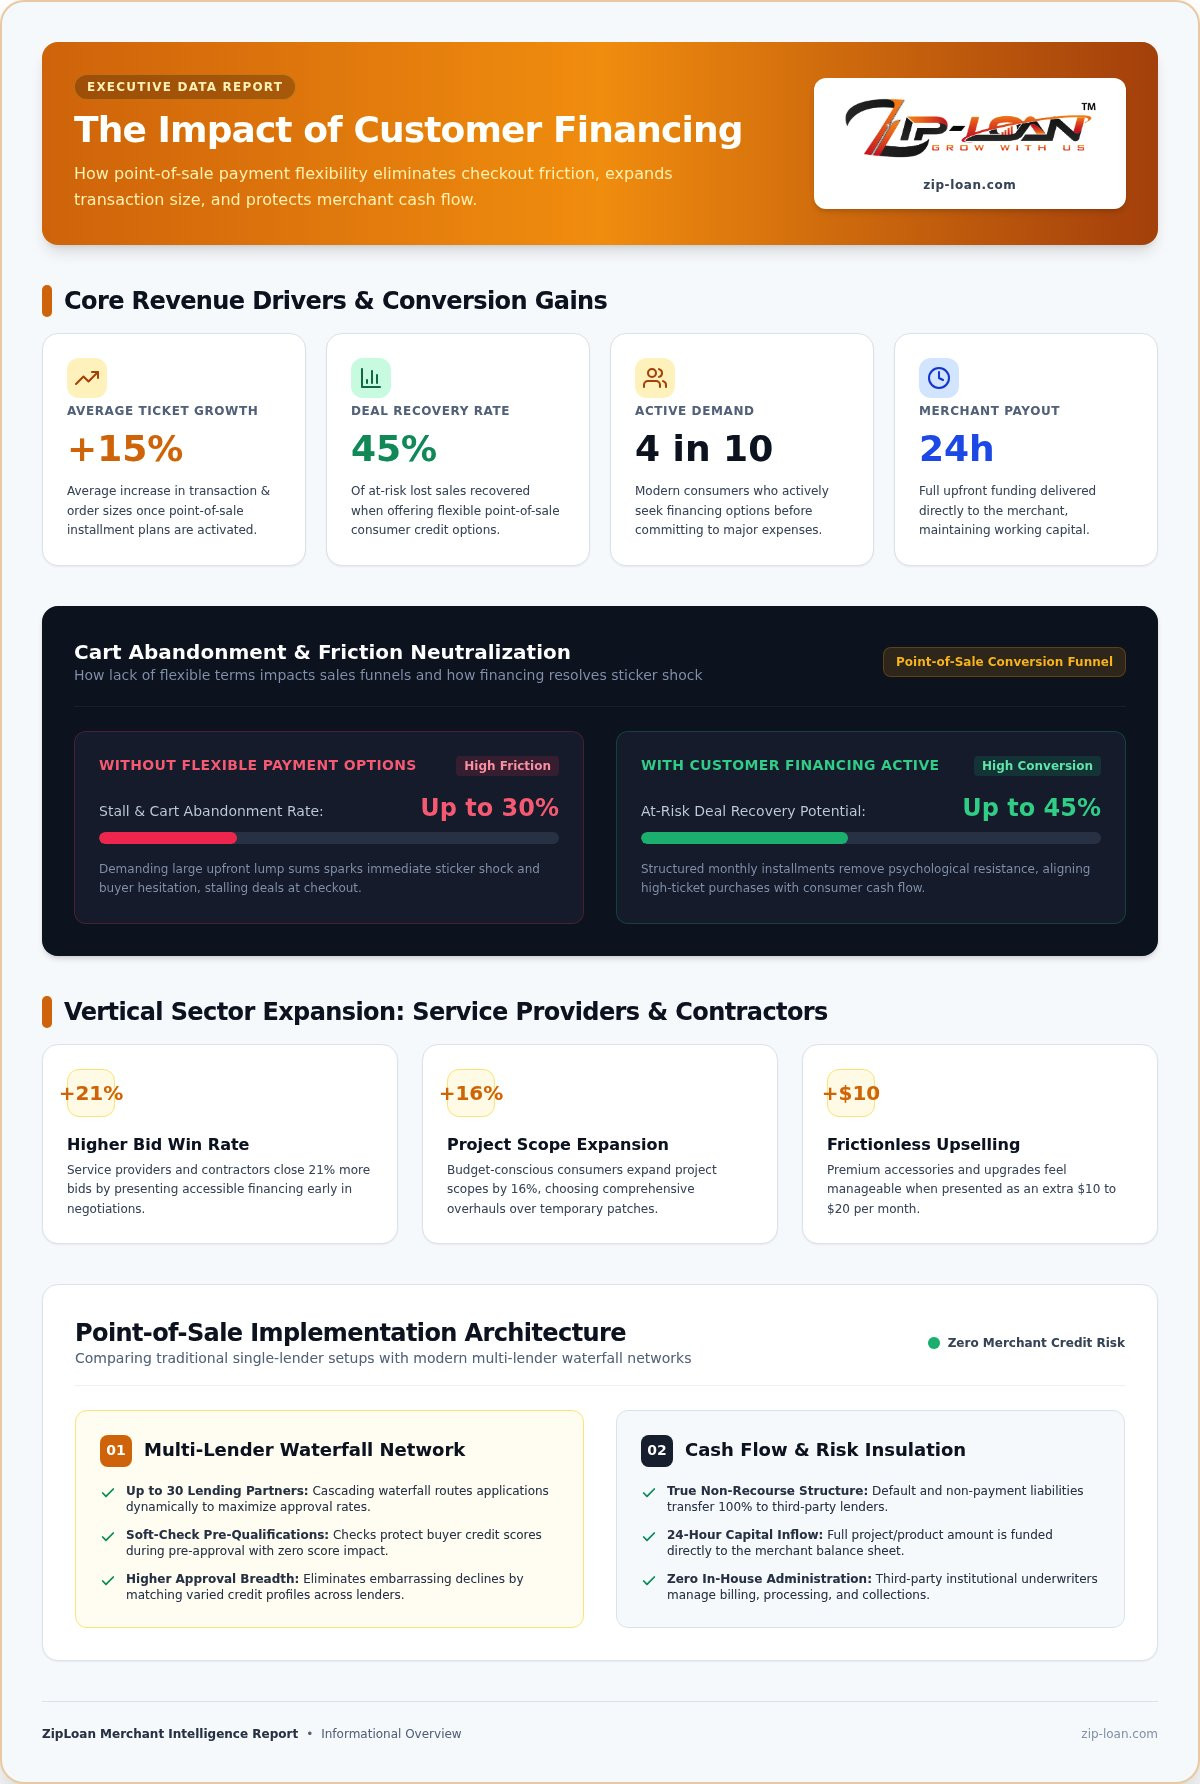
Every lost sale at checkout represents more than missed immediate cash; it reveals a structural flaw in your conversion funnel. When transactions stall, sticker shock is almost always the culprit. Traditional point-of-sale environments demand that buyers shoulder substantial lump sums immediately, sparking hesitation and cart abandonment. Understanding the primary benefits of offering customer financing allows you to dismantle this hurdle entirely. By breaking intimidating totals into predictable monthly installments, you remove psychological friction and realign your checkout process with modern purchasing habits. Merchants see up to 30% of prospective shoppers abandon purchases when flexible terms are absent. Providing flexible consumer credit options directly at checkout can recover up to 45% of those at-risk deals.
To see how flexible payment options transform everyday sales operations, watch this brief overview:
Gaining clarity on why financing drives measurable expansion is key to modern merchant growth. It reframes expensive capital outlays into manageable monthly commitments, helping you scale order values across every channel.
Eliminating Price Resistance at the Point of Sale
Transforming high-ticket invoices into accessible monthly terms neutralizes buyer hesitation on contact. Roughly four in ten modern consumers actively seek financing options before committing to major expenses. When you present structured payment plans early in the buying conversation, you eliminate friction before it stalls negotiations. Buyers make faster decisions because the expense fits naturally within their existing household or operational cash flow, keeping deals moving swiftly through your pipeline.
Expanding Transaction Size Through Strategic Upselling
Strategic payment flexibility does more than rescue wavering buyers; it expands your average ticket size. In fact, merchants experience an average 15% increase in order size once point-of-sale installment options are active. Instead of settling for entry-level fixes, clients upgrade confidently:
- Incremental upgrades: Premium accessories or extended warranties feel manageable when framed as an extra ten or twenty dollars per month.
- Comprehensive project scopes: Homeowners and vehicle owners choose complete system overhauls over temporary, cut-rate patches.
- Higher conversion velocity: Upselling becomes a consultative value-add rather than an aggressive sales pitch.
Unlocking these core revenue benefits of offering customer financing equips your team to capture latent demand, expand contract values, and turn tentative prospects into loyal, high-ticket clients.
Cash Flow Protection: Upfront Funding with Zero Merchant Credit Risk
Extending payment flexibility often triggers a valid merchant concern: who bears the liability when a customer fails to pay? Managing in-house payment terms ties up operational liquidity, clogs accounting workflows, and exposes your balance sheet to painful defaults. One of the most vital benefits of offering customer financing through an established network is complete financial insulation. Instead of acting like an informal lending institution, you secure upfront capital while delegating administrative headaches to institutional underwriters.
Recent data from the Federal Reserve Bank of New York’s Quarterly Report on Household Debt and Credit illustrates the massive scale of consumer obligations across the country. Navigating this dynamic requires smart risk management. Third-party financing allows you to tap into consumer borrowing demand while ensuring your business stays insulated from volatile debt cycles.
Shifting Default and Collection Liabilities to Lenders
Modern point-of-sale programs operate on a true non-recourse structure. The lending partners handle credit evaluations, payment processing, regulatory disclosures, and ongoing account servicing. If an approved buyer later encounters financial hardship, misses monthly installments, or files for personal bankruptcy, your enterprise retains every dollar of the initial transaction. You completely bypass:
- Balance sheet risk: Eliminate bad debt reserves and keep uncollected receivables off your financial statements.
- Collection duties: Avoid uncomfortable follow-up calls, contentious payment disputes, and expensive legal recovery efforts.
- Administrative overhead: Free your back-office staff from tracking recurring invoices, calculating interest, or reconciling partial remittances.
Accelerating Working Capital Through Instant Merchant Payouts
Cash flow stability serves as the operational lifeblood for growing companies. Traditional net-30 or net-60 arrangements force you to float labor and inventory expenses, stalling business momentum. POS financing solves this hurdle by providing direct merchant funding within 24 hours of verified transaction or project completion.
Trade contractors, for instance, utilize these rapid payouts to purchase raw materials, pay job site crews, and accept new assignments without liquidity constraints. You deliver the work or hand over the goods, and the full settlement lands directly in your commercial operating account. By tapping into the risk-free benefits of offering customer financing, you sustain rapid daily operations without draining company reserves. If you want to streamline receivables and protect your bottom line, consider partnering with Zip-Loan to power your checkout process.
Customer Acquisition and Retention: Beating Competitors on Affordability
Price transparency alone rarely wins customer loyalty in competitive markets. Today’s consumers assess major purchases based on how comfortably an expense fits into their ongoing monthly cash flow. If your checkout demands immediate cash or standard high-interest credit card swipes, you actively push prospective buyers toward competitors who provide manageable payment terms. Recognizing the acquisition benefits of offering customer financing allows you to position affordability at the center of your marketing strategy, turning casual browsers into committed buyers.
Adopting flexible customer financing solutions enables your team to capture underserved market demand. By transforming steep, upfront pricing into approachable monthly options, you immediately expand your addressable audience.
Winning Over Budget-Conscious and Credit-Diverse Shoppers
Traditional financing structures often alienate consumers by setting exclusionary credit thresholds. Modern POS networks expand accessibility by underwriting credit profiles starting around a 550 credit score. More importantly, this transition relies on initial soft credit inquiries:
- Credit score protection: Soft checks allow buyers to review terms and pre-qualify without lowering their credit scores.
- Credit line preservation: Installment loans let customers keep their existing credit card lines open for everyday expenses or unexpected emergencies.
- Reduced friction: Instant, private digital pre-qualification removes the social embarrassment often tied to credit rejections.
Leveraging Promotional Financing to Outmaneuver Competitors
Promotional financing functions as an irresistible conversion magnet. Offering same-as-cash incentives, such as 0% promotional APR periods spanning 6 to 24 months, eliminates interest-rate anxiety for cost-conscious shoppers. Buyers who possess the cash often choose these plans simply to maintain liquidity in their personal accounts.
Promote these flexible options early across your marketing assets, website banners, and sales proposals. Highlighting terms upfront changes customer psychology from “Can I afford this?” to “Which option works best for my budget?” Over time, buyers remember the ease and respect of your transaction experience. They return for subsequent purchases, refer friends and family, and ignore competitors stuck with inflexible payment models. These competitive benefits of offering customer financing establish sustainable customer retention that shields your margins and steadily scales lifetime value.
Vertical Impact: How Financing Transforms Key Industry Sectors
Consumer financing isn’t a one-size-fits-all tool; its mechanics shift dramatically depending on the industry you operate in. While retail merchants use payment flexibility to reduce cart abandonment, service-oriented trades rely on structured terms to secure high-ticket proposals and solve urgent customer emergencies. Across these diverse commercial environments, the operational benefits of offering customer financing deliver tangible revenue gains tailored to specific trade demands.
Home Improvement and Contracting: Closing Big-Ticket Projects
Residential contractors frequently face client budget pushback when bidding on roofing, HVAC, or remodeling jobs. Roughly 27% of homeowners actively finance major renovations to avoid depleting liquid savings. Presenting installment credit during the estimate phase shifts the conversation from total contract price to an affordable monthly plan. Contractor partners report closing 21% more deals and landing 16% larger projects simply by giving homeowners payment room. Instead of settling for a patched roof or an inadequate HVAC repair, clients approve comprehensive replacements with confidence.
Healthcare and Auto Repair: Resolving Emergency Financial Hurdles
Unexpected expenses create immediate financial distress for consumers. When a transmission fails or an urgent dental procedure arises, few households possess immediate cash reserves to pay on the spot. Modern POS financing transforms what could be a stressful negotiation into a smooth, supportive customer experience:
- Confidential mobile applications: Customers pre-qualify privately on their smartphones via secure text links, avoiding awkward front-desk conversations.
- Immediate repair and care authorizations: Rapid underwriting decisions allow technicians and clinicians to begin work without delay.
- Reliable practice revenue: Facilities avoid floating expensive parts or medical lab fees, securing full reimbursement quickly.
To evaluate how tailored lending structures accelerate growth across different trade environments, review the market applications on our industries we serve page. Harnessing the sector-specific benefits of offering customer financing ensures your business captures revenue right when your clients need your expertise most.
Explore tailored financing solutions for your industry
Implementing Point-of-Sale Financing: Single Lenders vs. Multi-Lender Portals
Choosing the right technology architecture determines whether your financing program accelerates growth or creates unexpected sales bottlenecks. Many businesses begin with a single direct lending partner, only to watch sales collapse right at the register. Maximizing the operational benefits of offering customer financing requires an infrastructure capable of serving diverse credit profiles without adding administrative drag.
The Multi-Lender Waterfall Advantage Over Single Lenders
Single-lender programs rely on rigid, narrow underwriting criteria. When an applicant falls just outside that institution’s risk appetite, the system issues a flat rejection. Single lenders often decline up to 50% of applicants who fail to meet strict prime guidelines. In fact, 60% of customers approved through multi-lender networks were previously turned away by prime institutions.
Multi-lender waterfall technology eliminates this friction entirely. Instead of submitting multiple applications, your buyer completes a single, streamlined form. The platform instantly cascades the request across a network of up to 30 lenders, moving seamlessly from prime institutions down to alternative underwriters. This intelligent routing delivers approval rates exceeding 85%, securing instant decisions for amounts up to $65,000 with repayment terms extending up to 20 years.
Simple Steps to Launch Seamless Merchant Financing
Modernizing your checkout experience shouldn’t require complex technical overhauls. Rolling out a high-converting point-of-sale program takes four direct steps:
- Step 1: Merchant enrollment. Register your business within a dedicated multi-lender portal to connect instantly with dozens of credit partners.
- Step 2: Deploy marketing assets. Place clear POS signage, online payment buttons, and direct QR codes across your storefront, sales sheets, and digital invoices.
- Step 3: Introduce pre-qualification early. Offer soft-check financing during initial quotes, allowing clients to explore affordable terms without impacting their credit scores.
- Step 4: Close and receive funding. Capture instant digital approvals and finalize contracts knowing your business receives full payment within 24 hours.
Explore our complete consumer financing services to learn how an automated multi-lender setup can transform your sales floor. Harnessing the true benefits of offering customer financing ensures you never lose another qualified buyer to rigid credit standards.
Transform Your Point of Sale into a Scalable Growth Engine
Eliminating payment hesitation is the most effective way to expand transaction sizes while protecting operational cash flow. Capturing the full benefits of offering customer financing means you don’t have to choose between winning high-ticket bids and safeguarding working capital. Shifting non-payment liability entirely to institutional lending partners ensures your enterprise receives full payment within 24 hours while buyers enjoy clear, manageable monthly terms.
Connecting to 30 trusted lenders through a single integrated portal unlocks approval rates exceeding 85%, serving credit scores down to 550. With instant decisions up to $65,000, you provide immediate purchasing power right at the point of sale without placing your balance sheet at risk.
Take control of your revenue trajectory, eliminate purchase friction, and build the empowering checkout experience your customers deserve.
Frequently Asked Questions
How does offering customer financing benefit my business cash flow?
Offering financing injects immediate working capital into your business because third-party lenders fund approved invoices upfront. Instead of acting as an informal bank or waiting 30 to 90 days on receivables, you get paid in full within 24 hours. This predictable capital flow lets you cover operational costs, order materials, and reinvest without draining your cash reserves. Experiencing these immediate benefits of offering customer financing keeps your cash flow consistent and dependable.
What happens if a customer defaults on their financing payments?
Your business carries zero liability if a customer defaults on their loan payments. Modern point-of-sale programs operate on a non-recourse basis, meaning the third-party lending network assumes all credit underwriting, servicing, and collection responsibilities. Once the transaction completes and your funds deposit, you retain 100% of the proceeds. Your enterprise remains completely shielded from customer bankruptcies, late payments, or ongoing collection hassles.
Can offering customer financing increase my average order value?
Yes, financing consistently lifts order sizes by an average of 15% across retail and service sectors. When customers evaluate purchases by low monthly installments rather than intimidating total sums, they feel empowered to upgrade. Buyers regularly opt for premium packages, extended warranties, or broader project scopes instead of bare-minimum fixes. This simple shift unlocks the revenue benefits of offering customer financing by turning modest transactions into higher-tier sales.
Does checking financing options negatively impact my customer’s credit score?
No, exploring pre-qualification options does not harm your customer’s credit score. The initial application utilizes a soft credit inquiry, allowing buyers to check eligible terms and monthly payment estimates safely. A traditional hard inquiry only occurs if the customer decides to accept an official loan offer and complete the agreement. This friction-free process encourages hesitant shoppers to explore financing without fearing damage to their personal credit ratings.
How quickly does a merchant receive funds after a financed sale?
Merchants typically receive full funding within 24 hours of project sign-off or transaction completion. Unlike slow corporate invoicing or traditional installment plans where you wait weeks for checks to clear, digital POS platforms automate direct deposits. Healthcare providers and high-volume contractors often see daily settlements. Rapid payout turnaround ensures you maintain active operational momentum without floating inventory, parts, or labor expenses out of pocket.
What is the difference between a single-lender program and a multi-lender platform?
A single-lender setup relies on one financial institution, which declines up to half of non-prime applicants and stalls sales. A multi-lender platform connects your business to a waterfall network of up to 30 diverse lenders through one portal. If a prime lender turns down an applicant, the engine automatically routes the request down the chain. This structure achieves approval rates above 85% across all customer credit profiles.
Can customers with low credit scores qualify for financing programs?
Yes, multi-lender networks provide accessible financing options for credit scores starting down around 550. Because the waterfall technology evaluates applicants across prime, near-prime, and subprime lending tiers, approvals remain high. In fact, 60% of consumers approved through multi-lender systems were previously rejected by conventional prime banks. This broad access ensures your sales team doesn’t lose qualified buyers simply because of a non-traditional credit profile.