
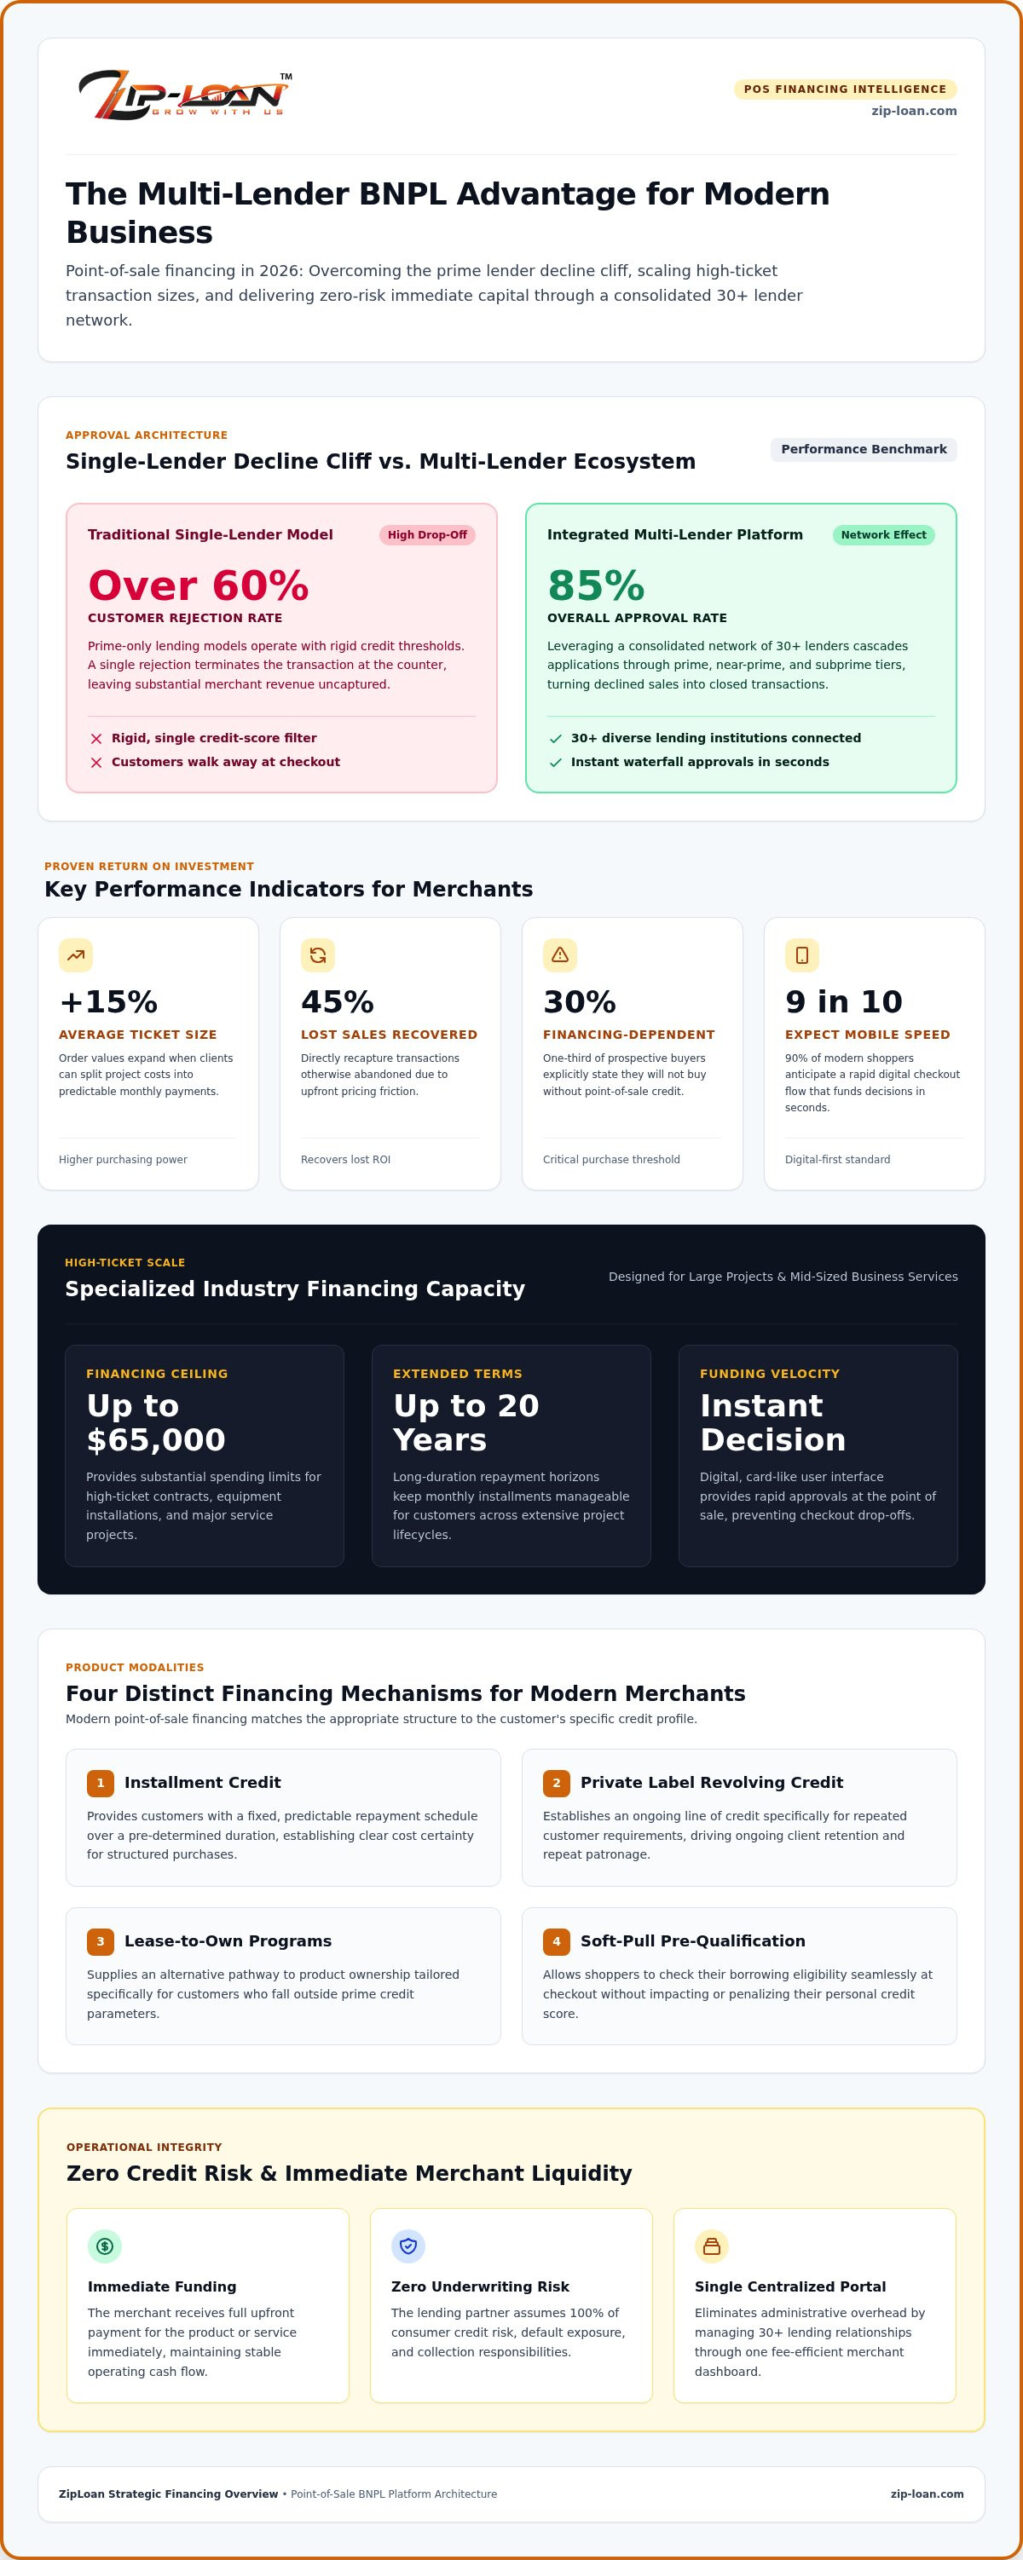
Did you know that over 60% of consumers seeking point-of-sale financing are rejected by traditional prime lenders, leaving a massive portion of your potential revenue on the table? It’s a common hurdle for merchants who rely on a single financing partner, only to see customers walk away because they don’t meet a specific, rigid credit score. You already know that every decline isn’t just a lost transaction; it’s a missed opportunity to build a long-term relationship and scale your operations.
Implementing a robust multi-lender buy now pay later for business platform allows you to bridge this gap and capture the growth you’ve been chasing. By reading this guide, you’ll discover how to increase your average ticket size by 15% and recover nearly 45% of your lost sales through a streamlined, high-approval ecosystem. We’ll show you how to move beyond the decline cliff by leveraging a network of 30+ lenders to secure instant approvals up to $65,000. This article previews the exact steps to transition from complex, manual processes to a visionary financing model that provides immediate funding and elevates your business to its next stage of success.
Key Takeaways
- Boost your bottom line by increasing average ticket sizes by 15% and recovering nearly half of your abandoned sales through flexible financing.
- Navigate the shift toward multi-lender platforms to achieve an 85% approval rate, ensuring you never lose a customer to a single-lender decline again.
- Unlock high-ticket potential in specialized industries by offering financing for projects up to $65,000 with repayment terms reaching up to 20 years.
- Streamline your growth with a buy now pay later for business solution that provides an instant, card-like experience and immediate funding for your operations.
- Eliminate the complexity of managing multiple financial relationships by integrating 30+ lenders into one centralized, fee-efficient merchant portal.
What is ‘Buy Now Pay Later’ for Business in 2026?
Point-of-sale financing has evolved into a sophisticated growth engine that empowers merchants to offer flexible payment terms at the moment of purchase. While early iterations focused on micro-transactions for retail goods, buy now pay later for business in 2026 represents a shift toward “Financing as a Service.” This model allows small to mid-sized companies to act as their own financial facilitators, providing customers with the ability to split high-ticket costs into manageable installments up to $65,000. It’s essential to distinguish this from B2B procurement BNPL, which handles how you buy supplies. Instead, merchant-offered BNPL focuses on how you sell your services to your own clients, removing the immediate price barrier to closing deals.
To better understand the impact this can have on your operations, watch this helpful video:
The Evolution of Point-of-Sale Credit
Traditional store credit cards once dominated the landscape, but they often required lengthy applications and rigid credit checks that alienated a massive portion of the market. Modern Buy now, pay later financing models have replaced these hurdles with instant, digital-first interfaces. Today, 9-in-10 shoppers expect a seamless mobile experience where they can secure funding in seconds. As the economy fluctuates, prime-only lending has declined in effectiveness. Visionary merchants are now turning to multi-lender platforms that accommodate a broader spectrum of credit profiles, ensuring that more customers receive a “yes” at the service desk even if they fall into near-prime or subprime categories.
Key Terminology for Modern Merchants
Success starts with understanding the specific tools at your disposal. You aren’t limited to a single product. Installment credit provides a fixed repayment schedule, while private label revolving credit offers a line of credit for ongoing needs. For customers with lower credit scores, lease-to-own programs provide an alternative path to ownership. Most of these modern solutions utilize a “soft-pull pre-qualification,” which allows your customers to check their eligibility without impacting their credit score. When evaluating these options, focus on the “Discount Fee.” While this is the cost you pay per transaction, the return on investment comes from capturing the 45% of sales that would otherwise be lost to a lack of financing. You can learn more about why financing is the key to scaling by exploring how it shifts the focus from cost to value.
How Modern BNPL Platforms Drive Merchant Revenue
Accelerate your revenue by removing the financial friction that often stalls high-ticket deals. Implementing buy now pay later for business isn’t just about offering a convenience; it’s a strategic move to capture the 30% of shoppers who state they wouldn’t complete a transaction without point-of-sale financing. By providing an instant, card-like experience, you mirror the speed of a credit card transaction while unlocking significantly higher purchasing power for your clients. This shift is highlighted in the CFPB market report on Buy Now, Pay Later trends, which notes how these models are becoming essential for merchants to maintain competitiveness in a shifting economy.
Perhaps the most empowering aspect for the business owner is the zero-risk nature of these platforms. You receive full funding for the project or product immediately. The lender assumes all responsibility for credit risk and collections. This allows you to maintain healthy cash flow without the burden of managing debt or chasing payments. If you’re looking to optimize your operations, you can explore how financing transforms your sales process from a hurdle into a catalyst for growth.
Increasing Your Average Ticket Size
Merchants who integrate these platforms typically see a 15% increase in average order size. This growth is driven by 0% promotional APR options that encourage customers to choose premium upgrades they might otherwise decline. Offering flexible terms from 12 to 120 months, and even up to 20 years for major projects, makes high-ticket items up to $65,000 feel immediately affordable. Monthly payment options shift the customer’s focus from the daunting total price to a manageable monthly budget fit. This psychological shift allows your sales team to present the best possible solution rather than the cheapest one.
The Merchant Workflow: From Application to Funding
Modern platforms eliminate the “decline cliff” and the paperwork traditionally associated with credit. The process is designed for speed and simplicity. It respects your time and your customer’s intelligence. Here is how it works:
- Step 1: Your customer scans a QR code at your desk or receives a text-to-apply link on their mobile device.
- Step 2: They complete a soft-pull application that delivers instant offers from a network of 30+ lenders without affecting their credit score.
- Step 3: Once the customer selects their plan, the merchant receives funding within 24 hours.
This streamlined approach ensures your business stays liquid and ready for the next project. You won’t have to wait for project completion or navigate complex bank relationships to get paid.
The Strategic Advantage of Multi-Lender Financing Platforms
Eliminate the “decline cliff” by shifting your strategy from a single-bank model to a comprehensive multi-lender ecosystem. Relying on a single financing partner often creates a “prime-only” trap where nearly 60% of your prospective buyers are rejected immediately because they don’t meet one lender’s specific, narrow criteria. This doesn’t just end a transaction; it creates a negative experience that can drive a customer straight to your competitor. Transitioning to a multi-lender buy now pay later for business platform ensures that one application opens dozens of potential approval paths, maximizing your chances of hearing “yes” at the service desk.
A recent McKinsey analysis on point-of-sale financing models suggests that specialized, vertical-specific architecture is essential for capturing high-ticket sales. By leveraging a network of 30+ lenders, you can serve the full credit spectrum. This includes everyone from customers with 800+ FICO scores to those with credit scores as low as 550. This inclusive approach is why ZipLoan maintains an average approval rate of over 85%, empowering you to close deals that other merchants simply cannot fund.
Comparing Single-Source vs. Multi-Lender Models
Single-source solutions are fundamentally limited by the risk appetite of one institution. When that bank tightens its lending standards, your sales suffer. In contrast, a multi-lender platform creates an environment where lenders compete for your customer’s business. This competition drives better terms for the consumer and significantly more “Approved” button clicks for your staff. You gain the flexibility to offer diverse terms, from 12-120 months up to 20 years, without being tethered to the limitations of a single prime bank. This model turns your financing portal into a visionary tool for expansion rather than a bottleneck.
Soft-Pull Technology and Consumer Trust
Building trust is the foundation of any high-ticket sale. Research shows that 95% of customers rate clear, transparent terms as essential when considering financing. Modern platforms utilize soft-pull technology, which allows customers to see their offers without any damage to their credit score. This removes the fear of rejection and encourages more shoppers to explore their options. By offering private-label revolving credit and installment plans through a trusted portal, you build lasting brand loyalty. Customers feel supported rather than scrutinized, positioning your business as a partner in their success. You can see how these tools fit your specific field by reviewing the industries we serve to find your tailored solution.
Implementing BNPL Across Specialized Industries
Vertical integration transforms a generic payment tool into a specialized sales engine. By tailoring your buy now pay later for business strategy to the unique demands of your specific field, you address the exact friction points that prevent your customers from signing on the dotted line. Whether you’re managing a high-ticket home renovation or an emergency medical procedure, the right financing structure ensures that cost is never the final word. This industry-specific approach allows you to move beyond basic transactions and start facilitating major life improvements for your clients.
Contractor Financing: Closing More Big Jobs
Residential remodeling and HVAC projects often carry high price tags that can trigger immediate sticker shock. Roofing and home service professionals who implement specialized financing see an average 21% lift in deal closures. By offering installment credit for projects up to $65,000 with terms reaching up to 20 years, you make a complete kitchen remodel or a full roof replacement feel like a manageable monthly commitment. Promotional “Same-as-Cash” offers are particularly effective here. They allow homeowners to start their projects immediately while deferring interest, which often serves as the final catalyst for a signed contract. You can explore how these tools apply to your specific trade by reviewing the industries we serve.
Healthcare and Retail Success Strategies
Closing the gap for elective procedures requires a delicate balance of empathy and financial flexibility. Patient financing solutions allow you to offer care without the burden of prepayment penalties, ensuring that health decisions remain based on need rather than immediate liquidity. With daily funding, your practice remains liquid while patients benefit from fixed monthly installments. In the retail sector, visibility is everything. Using “Touch-n-Buy” assets like window clings and brochures can significantly impact your bottom line. Data shows that 4 in 10 shoppers will utilize financing if they know it’s an option before they reach the checkout. This proactive communication builds confidence and increases the likelihood of a premium purchase.
Auto Repair and Professional Services
Emergency auto repairs are rarely planned, and a $1,500 repair bill can be a major disruption for most households. Offering lease-to-own programs or 0% interest promotions at the service desk prevents abandoned repair orders and keeps your bays full. Similarly, professional services like law firms are increasingly using legal financing to drive revenue. By allowing clients to pay for counsel through structured installments, firms can secure their fees upfront while providing clients with the representation they need. This model eliminates the “cash flow gap” that often plagues service-based businesses waiting for project milestones or case resolutions.
Partner with a visionary financing provider today
Scaling Your Business with ZipLoan’s Financing in a Box
Unlock the full potential of your sales team by removing the administrative burden of traditional lending. ZipLoan provides a “Financing in a Box” model that allows you to bypass the typical hurdles of merchant credit and start scaling immediately. You can integrate a comprehensive buy now pay later for business strategy without worrying about dealer fees eating into your margins. This efficiency is paired with a powerful Merchant Dashboard, which acts as your command center. It provides clear visibility into every application, whether you’re offering installment credit or lease-to-own programs. This level of oversight allows you to identify which promotional offers are driving the most conversions and adjust your approach in real-time.
Maintain your liquid position with instant funding that lands in your account within 24 hours of approval. This rapid settlement eliminates the cash flow gaps that often stall project-based work, ensuring you have the capital needed for your next job. To further boost awareness, you can leverage free marketing support and POS advertising assets. From window clings to digital banners, these tools ensure every customer knows that a premium upgrade is within their reach. By positioning financing as a core part of your brand, you transition from a simple vendor to a visionary facilitator of your clients’ goals.
The Merchant Enrollment Journey
Streamline your transition into a financing-led growth model with a process designed for speed. Getting started is simple and avoids the hidden transaction hurdles that often plague traditional banking relationships. The first step involves merchant enrollment for financing, where you’ll gain access to a platform that connects you with 30+ lenders instantly. Once enrolled, you’ll set up a personalized online portal tailored to your specific business needs. This portal serves as the central hub where customers can submit applications and receive instant offers, creating a professional and cohesive experience that builds trust from the first click.
Future-Proofing Your Sales Strategy
Adapt to the shifting economic climate where offering flexible payment terms is no longer a luxury but an operational necessity. In a high-interest environment, customers are increasingly protective of their immediate liquidity. You can use the APR calculator as a consultative sales tool to show exactly how a large investment, such as a $65,000 home improvement project, fits into a manageable monthly budget. This transparency transforms the sales conversation from one about total cost to one about value and long-term affordability. Are you ready to remove the final barrier to your expansion? Empower your business growth with ZipLoan today and secure the tools you need to lead your industry.
Accelerate Your Business Growth with Visionary Financing
Adopting a modern buy now pay later for business strategy is the catalyst your company needs to remove financial barriers and capture latent revenue. You’ve seen how moving beyond the “decline cliff” of single-lender models can transform your sales floor into a high-conversion environment. By leveraging a network of 30+ lenders in one portal, you ensure that more customers receive an immediate “yes,” driving your approval rates to an average of 85%. This isn’t just about processing transactions; it’s about optimizing your entire sales funnel for expansion and long-term success.
Providing instant approvals for amounts up to $65,000 gives your clients the confidence to choose the best solutions rather than the cheapest ones. You’re now equipped to scale with a “Financing in a Box” model that prioritizes your cash flow and removes the traditional barriers to entry. Your business is on the verge of a significant breakthrough, and the right financing partner is the key to that transition. It’s time to stop leaving sales on the table and start building the future you’ve envisioned.
Your idealized future is within reach. Take the final step toward a more expansive and profitable journey today.
Frequently Asked Questions
How does Buy Now Pay Later for business differ from a traditional business loan?
Buy Now Pay Later functions as a point-of-sale tool that allows your customers to pay in installments while you receive full payment upfront. Unlike a traditional business loan, which is debt your company takes on for capital, this financing model focuses on accelerating consumer purchasing power. It removes the barrier of high upfront costs, allowing you to close more deals without increasing your own liabilities or managing complex repayment schedules.
Will offering financing to my customers impact my own credit score?
Offering financing through ZipLoan has no impact on your personal or business credit score. The application process involves a soft credit pull for the customer, which protects their score while providing you with an instant approval decision. Since the lenders assume the credit risk, your credit profile remains untouched. This allows you to scale your operations and offer premium services with total confidence in your financial standing.
How quickly does a business get paid after a customer is approved for BNPL?
Merchants typically receive full funding within 24 hours of a customer’s approval. This rapid settlement ensures your cash flow remains healthy, allowing you to pay for materials or labor without delay. For healthcare providers, the platform offers daily funding to maintain operational fluidity. Getting paid immediately while your customer pays over time creates a visionary balance that supports both your business growth and your client’s budget.
What credit scores are required for customers to be approved on the ZipLoan platform?
The ZipLoan platform is designed to serve a broad credit spectrum, accommodating scores as low as 550. While traditional prime lenders often decline nearly 60% of applicants, our multi-lender network achieves an 85% approval rate by routing applications through 30+ different lenders. This inclusive approach ensures that near-prime and subprime customers can still access the buy now pay later for business options they need to complete their purchases.
Are there any hidden dealer fees or risks for the merchant?
There are no hidden dealer fees or risks for the merchant when using this platform. ZipLoan offers a transparent structure that includes free enrollment and risk-free financing for your shop. The lenders assume all responsibility for collections and credit risk, so you don’t have to worry about defaults. This model protects your margins while providing a catalytic tool for increasing your average order size by 15% through optimized purchasing power.
Can BNPL be used for high-ticket items like HVAC systems or home renovations?
Yes, the platform is specifically optimized for high-ticket industries like HVAC, roofing, and residential remodeling. You can offer instant approvals for amounts up to $65,000, with total financing options reaching $100,000 for larger projects. With repayment terms extending from 12 to 120 months and even up to 20 years, you make major home renovations feel affordable for your clients, helping you close 21% more big-ticket deals.
Does ZipLoan offer 0% interest promotional periods for customers?
ZipLoan provides several 0% promotional APR options to help you drive higher sales volume. Customers can access same-as-cash periods for 6, 12, 18, or 24 months when the balance is paid in full within the promotional window. These offers are powerful consultative tools that encourage shoppers to upgrade to premium products. Using these promotions often recovers up to 45% of sales that would otherwise be lost to budget constraints.
How do I integrate BNPL into my existing point-of-sale process?
Integrating buy now pay later for business into your existing process is seamless and requires no complex hardware. You can provide customers with a personalized web link, a QR code for mobile scanning, or send a text-to-apply link directly to their phone. The application takes seconds, mirroring the speed of a standard credit card transaction. This digital-first approach ensures a frictionless experience that meets modern consumer expectations for immediate approvals.