
Did you know that offering flexible payment options at the point of sale can increase your conversion rates by up to 30%? Imagine capturing every customer who currently walks away because of a high upfront cost. Implementing the right customer financing programs for business isn’t just a nice-to-have perk anymore; it’s the definitive growth strategy for 2026. You’ve likely felt the sting of high cart abandonment or watched a potential client choose a competitor simply because they offered a monthly plan you didn’t. It’s frustrating to lose revenue to traditional bank rejection rates or complex regulatory hurdles that feel impossible to clear.
We understand that you want to scale without taking on unnecessary debt risk or administrative headaches. This article promises to reveal how you can implement high-conversion programs that remove price barriers and accelerate your business revenue immediately. Are you ready to see your average ticket size soar while receiving payment the moment the sale is made? We’ll preview the most effective installment and lease-to-own models, explore how to navigate new 2026 disclosure laws, and show you how to integrate these tools into your existing sales flow for a seamless breakthrough in performance.
Key Takeaways
- Understand how to secure immediate payment for your business while allowing customers to pay over time, effectively removing price as a barrier to entry.
- Identify the specific customer financing programs for business that align with your price point, ranging from installment credit to flexible lease-to-own options.
- Learn to tailor your financing speed to meet urgent customer needs, ensuring you never lose a job to a competitor with more flexible payment plans.
- Discover the “waterfall” lending strategy designed to maximize approvals and capture every customer profile, regardless of their credit background.
- Explore how a “financing in a box” solution can be seamlessly integrated into your current sales flow to catalyze your next stage of business expansion.
What Are Customer Financing Programs for Business?
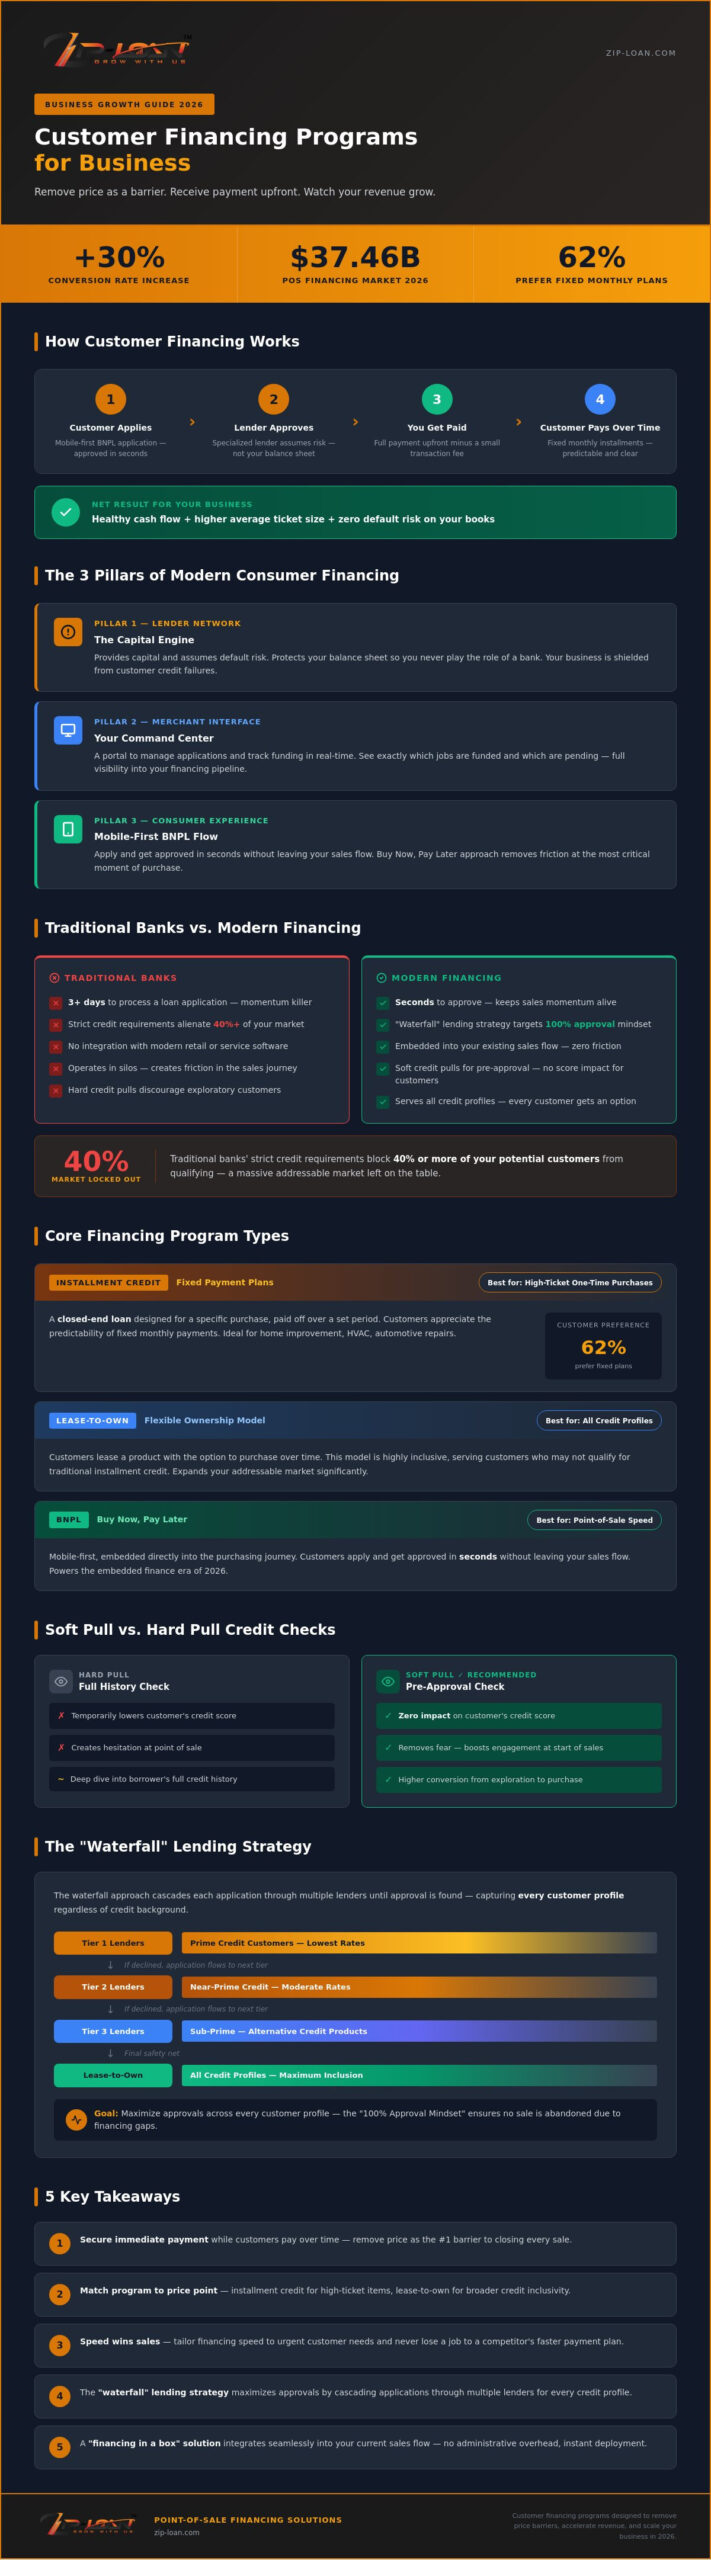
Transform your sales strategy by removing the single biggest obstacle to growth: the price tag. At its core, customer financing programs for business represent a strategic partnership between your company and a specialized lender to offer immediate credit at the point of sale. This isn’t just a payment plan; it’s a financial engine that fuels your revenue. The mechanism is simple yet powerful. While your customer enjoys the flexibility of paying over time, you receive the full payment upfront, minus a small transaction fee. This ensures your cash flow remains healthy while your customers get what they need exactly when they need it.
Why is 2026 the year this becomes non-negotiable? We’ve entered the era of “embedded finance,” where financial services are no longer external destinations but are woven directly into the purchasing journey. For small to mid-sized businesses, this shift has turned financing from an optional perk into a competitive necessity. If you sell high-ticket items and don’t offer a way to split the cost, you’re essentially handing your leads to a competitor who does. With the global point-of-sale financing market projected to reach $37.46 billion in 2026, the data is clear: customers expect flexibility at checkout. Deploying the right customer financing solutions ensures you meet this demand head-on and convert more prospects into paying clients.
The Three Pillars of Modern Consumer Financing
Think of your financing program as a tripod. It relies on three critical components to stay upright and functional:
- Lender Network: This is the engine that provides the capital and assumes the risk. It protects your balance sheet from defaults and ensures you aren’t playing the role of a bank.
- Merchant Interface: This portal allows you to manage applications and track funding in real-time. It’s your command center for viewing which jobs are funded and which are pending.
- Consumer Experience: Modern solutions utilize a mobile-first, Buy Now, Pay Later (BNPL) approach. This lets customers apply and get approved in seconds without ever leaving your sales flow.
Why Traditional Bank Loans Are Failing Your Customers
Traditional banking is often too slow for the modern consumer’s pace. Have you ever seen a customer lose interest because a loan application took three days to process? Slow approval times kill the momentum of an impulse buy or an urgent home repair. Legacy institutions often have strict credit requirements that alienate 40% or more of the market, leaving a massive segment of your potential audience without options.
These older models lack the integration with modern retail and service software that today’s businesses require. They operate in silos, creating friction where there should be fluidity. By choosing modern customer financing programs for business, you bypass these hurdles and offer a solution that moves as fast as your sales team does.
Core Types of Financing Programs to Offer Your Clients
Select the right financial vehicle to drive your sales forward. Not all customer financing programs for business are created equal, and the structure you choose should align perfectly with your average transaction value. High-ticket items like a new roof or a complete HVAC system require different tools than smaller retail purchases. One of the first decisions you’ll make involves the credit inquiry process. While “hard” credit checks provide a deep dive into a borrower’s history, they can temporarily lower a credit score. In contrast, “soft” pulls for pre-approval allow customers to check their eligibility without any impact on their score. This often leads to higher engagement at the start of the sales process because it removes the fear of credit damage.
A survey found that 62% of customers prefer fixed monthly payment plans with clear terms. This preference highlights why choosing the right credit vehicle is a strategic necessity rather than a back-office detail. Whether you’re looking for one-time transaction support or a way to build a recurring relationship, understanding these core structures is the first step toward expansion. Knowing how to choose a consumer financing partner that supports your full customer base is equally critical to ensuring these structures deliver maximum results.
Installment Credit and Fixed Payment Plans
Target high-ticket, one-time investments with precision. Installment credit acts as a closed-end loan designed for a specific purchase where the balance is paid off over a set period. This structure is ideal for industries like home improvement or major automotive repairs where the cost is significant but the purchase is infrequent. Customers appreciate the predictability of fixed monthly payments because it allows them to budget accurately for large expenses without surprises. By offering these clear terms, you remove the sticker shock that often leads to abandoned quotes and lost jobs.
Lease-to-Own: The 100% Approval Powerhouse
Unlock potential in markets where traditional credit scores fall short. Lease-to-own programs are a transformative tool because they often bypass conventional credit checks entirely, focusing instead on a customer’s current income and banking history. This makes them a secret weapon for furniture, electronics, and appliance retailers who want to serve the underbanked or those with no credit history. The psychology here is powerful; it moves the conversation from “Can I afford this?” to “I am earning ownership over time.” It’s a proactive way to ensure no customer is left behind due to a number on a credit report.
Private Label Revolving Credit
Foster long-term loyalty with a credit line that carries your brand’s name. Unlike a one-time loan, private label revolving credit gives customers a dedicated limit they can use repeatedly at your business. This strategy is excellent for retail and healthcare sectors where repeat visits are common. It significantly boosts Customer Lifetime Value (CLV) by making your store the first choice for future needs. When a customer has a branded credit option, they’re far more likely to return to you rather than a competitor. If you’re ready to see how these diverse options can fit your specific model, you can explore tailored merchant enrollment options to get started today.
Industry-Specific Applications: Scaling Your Niche
Generic solutions rarely yield exceptional results. When you implement customer financing programs for business, success depends on how well the financial product mirrors the customer’s buying journey. A homeowner facing a flooded basement has vastly different priorities than a couple browsing for an engagement ring. For the plumber, “financing speed” is the primary value proposition. If you can’t offer an approval in seconds via a mobile device, the customer might choose the competitor who can. By matching the pace of funding to the urgency of the need, you transform a stressful transaction into a manageable solution.
Positioning is everything. Instead of discussing “debt,” frame financing as a tool for optimization. This shift allows you to leverage credit to upsell premium materials or extended warranties. When a customer sees that an extra $20 per month upgrades them to a high-efficiency HVAC unit or a more durable roofing shingle, the value becomes clear. You aren’t just selling a product; you’re facilitating a better long-term outcome through flexible capital.
Contractors and Home Improvement
Close the deal on the driveway, not days later. Contractors in HVAC, roofing, and landscaping often deal with “grudge purchases”-things people have to buy but don’t necessarily want to. Using customer financing programs for business allows you to turn an emergency repair into a full system upgrade. Promotions like “no interest if paid in full” within a certain window are incredibly persuasive for homeowners. Because these decisions often happen on-site, having mobile-ready applications is non-negotiable for maintaining sales momentum.
Retail and High-Ticket Goods
Eliminate sticker shock before it stops a sale. Retailers selling furniture, jewelry, or electronics should display low monthly payments directly on price tags. This makes high-ticket items feel accessible rather than intimidating. Integrating these options into your e-commerce checkout flow reduces cart abandonment by offering a path forward for every budget. For customers who may not qualify for traditional credit, lease-to-own programs act as a vital bridge, capturing the “unbanked” or “underbanked” market that competitors often ignore.
Healthcare and Patient Financing
Prioritize care by removing financial friction. In the healthcare sector, flexible payments help patients afford elective procedures or manage high deductibles that might otherwise lead them to delay treatment. By removing the financial stress from the clinical conversation, you improve patient compliance and overall outcomes. When patients feel empowered to choose the best care path without immediate fiscal strain, your practice sees both increased loyalty and more consistent revenue streams.
How to Implement a 100% Approval Mindset
Stop leaving money on the table by saying “no” to customers who don’t fit a narrow credit box. The hidden cost of customer rejection is one of the biggest drains on a company’s growth. When you turn someone away due to credit hurdles, you aren’t just losing a single sale; you’re losing the lifetime value of that client and their potential referrals. Embracing a “Yes” Economy means shifting your perspective to see every prospect as a funded project waiting to happen.
Success in this area requires a “waterfall” lending strategy. This mechanism automatically routes a single application through a tiered network of lenders, from prime to sub-prime. If a traditional bank says no, the system immediately presents the application to alternative lenders or lease-to-own providers. This multi-lender approach is the only way to ensure your customer financing programs for business achieve the high approval rates necessary to scale. By catching every customer profile, you transform your sales floor into a high-conversion environment where price is never the final word. Businesses that invest in robust customer financing solutions for business growth consistently outperform competitors who rely on a single-lender model.
Step 1: Audit Your Current Lost Sales
Begin by quantifying the impact of price objections. Analyze your data from the last quarter to see exactly how many quotes were sent but never signed. Do you know the credit profile of your local market? In many regions, a significant portion of consumers may fall outside the “prime” window. Set an ambitious goal for a minimum 90% approval rate. Using multi-lender tools makes this target achievable, allowing you to serve the broad spectrum of your community’s financial backgrounds.
Step 2: Enroll in a ‘Financing in a Box’ Platform
Speed is your greatest ally in sales. Look for a partner that offers Merchant Enrollment with instant activation to avoid any downtime in your operations. A truly visionary platform handles the heavy lifting, including all regulatory compliance and debt collection. This transfers the risk away from your business, letting you focus on what you do best: providing excellent service and products. Transparency is also vital in 2026, especially with new regulations like California’s SB 362. Utilizing an integrated APR calculator ensures your offers are clear, legal, and built on trust.
Step 3: Market Your Financing Everywhere
Visibility creates opportunity. Don’t wait until the final invoice to mention payment options. Add “Financing Available” to your truck wraps, social media ads, and the header of your website. Train your sales team on “Payment-First” quoting. Instead of presenting a $5,000 upfront cost, lead with “$89 per month.” This simple shift in communication makes your services feel immediately attainable. Transparency in your customer financing programs for business builds immediate consumer trust, positioning you as a helpful partner rather than just another vendor. Ready to catalyze your expansion? Enroll as a merchant today and start saying yes to more customers.
ZipLoan: Your Visionary Partner for Business Expansion
Accelerate your trajectory by choosing a partner that views your success as its own. ZipLoan isn’t just a service provider; we’re the catalyst that turns your latent potential into tangible revenue. While previous sections explored the strategic “why” behind flexible payments, ZipLoan provides the “how” through a seamless “financing in a box” solution. Our platform is designed to dismantle the barriers that keep your customers from saying yes, allowing you to focus on the core operations of your business while we handle the complexities of the financial landscape.
We believe in a future where no customer is left behind due to rigid, outdated banking standards. Our “100% Approval” philosophy is more than a slogan; it’s a commitment to providing a waterfall of options that catch every profile, from prime borrowers to those needing lease-to-own alternatives. When you utilize our customer financing programs for business, you gain the benefit of instant liquidity. You receive payment for your services immediately upon the sale, while the risk of the loan is transferred entirely to our lender network. This ensures your cash flow remains robust and predictable, regardless of the customer’s payment schedule.
The ZipLoan Advantage: Technology Meets Growth
Manage your entire financial ecosystem from a single, intuitive dashboard. Whether your business requires installment credit for high-ticket home improvements or private label revolving lines for recurring retail visits, our technology integrates these diverse tools into one accessible interface. We prioritize transparency and compliance, offering features like an integrated APR calculator to ensure your offers meet all 2026 regulatory standards. This no-risk merchant model means you keep the profit and the customer relationship, while we shoulder the administrative and financial weight of the credit process.
Unlocking Your Business Potential Today
Experience a transition that is as smooth as it is transformative. Our merchant enrollment process is designed for speed, allowing you to go from application to offering credit in record time. ZipLoan is built to scale alongside you. Whether you’re financing your first system upgrade or managing your thousandth retail transaction, our support remains unwavering. We provide the expertise and the infrastructure necessary to turn customer financing programs for business into your most effective sales tool. It’s time to bridge the gap between your current state and your idealized future.
Catalyze Your Revenue Expansion for 2026
Transforming your sales strategy requires moving beyond the limitations of traditional credit. By adopting a “yes” economy mindset and leveraging a waterfall of lending options, you ensure that price is never the reason a customer walks away. We’ve explored how matching the right financial vehicle to your specific niche, whether in contracting or retail, creates a seamless experience that builds lasting loyalty. It’s about more than just transactions; it’s about removing the barriers that stand between your business and its idealized future.
Implementing high-performance customer financing programs for business is the definitive step toward securing immediate liquidity and increasing your average ticket size. With ZipLoan, you gain access to 100% Approval Programs and Instant Merchant Enrollment across our National US Coverage network. Whether you need specialized contractor or retail solutions, our “Financing in a Box” model keeps your business paid while we manage the risk. Empower your customers and grow your sales with ZipLoan’s Financing in a Box. Your next stage of growth is ready to begin; let’s unlock it together.
Frequently Asked Questions
How do customer financing programs work for a business?
Transform your sales process by acting as a bridge between your customers and professional capital. These programs establish a tri-party relationship where a lender provides the funding, you deliver the product or service, and the customer pays the lender over time. It’s a proactive way to deploy customer financing programs for business without having to act as a bank or carry the debt on your own books.
Will I get paid immediately if I offer financing to my customers?
Expect immediate liquidity for every financed sale you close. Once the customer approves the terms and signs their agreement, the lender typically transfers the full purchase amount to your business account within one to two business days. This ensures your operational cash flow remains steady and robust while your customer enjoys the flexibility of staggered monthly payments.
What are the requirements for a business to offer financing?
Start with basic business credentials and a vision for expansion. Most platforms require standard documentation like your tax identification number, business bank account details, and a brief history of your operations. The merchant enrollment process is designed to be frictionless; many businesses can begin offering credit to their clients on the same day they apply.
Can I offer financing to customers with bad credit or no credit history?
Capture a broader market by utilizing a multi-tiered lending approach that leaves no one behind. By using lease-to-own programs or near-prime installment credit, you can successfully serve customers who are often rejected by traditional banks. This “waterfall” strategy ensures that a low credit score doesn’t become an insurmountable barrier to your business growth.
What are the typical merchant fees for customer financing programs?
View merchant fees as a strategic investment in securing a much larger transaction. These fees are generally calculated as a percentage of the total sale, often comparable to standard credit card processing costs. The specific rate varies based on your industry, your average ticket size, and the level of risk the lender network assumes for the transaction. To make the most informed decision, understanding how to choose a consumer financing partner with the right fee structure for your business model is an essential part of your due diligence.
How does offering financing increase my average order value (AOV)?
Shift the sales conversation from the total upfront price to a manageable monthly budget. When customers see that a premium upgrade only adds a few dollars to their monthly payment, they’re far more likely to choose higher-end materials or extended warranties. This natural upselling mechanism is why customer financing programs for business are essential for maximizing the value of every lead.
Do I have to collect the payments from the customers myself?
Relieve your team of the administrative burden and risk associated with debt collection. The lender assumes all responsibility for billing the customer, processing their monthly payments, and managing any potential defaults. Your involvement in the financial side ends the moment the service is delivered and you’ve received your upfront funding from the lender.
Is it hard to integrate financing into my existing checkout or POS system?
Simplify your daily workflow with mobile-first technology that requires zero technical expertise. Modern financing tools are designed to work alongside your existing POS or e-commerce systems without requiring complex software overhauls. Most applications take less than a few minutes for a customer to complete on a tablet or smartphone right at the point of sale.