
Sixty percent of customers are currently being declined by prime-only lenders, leaving merchants to watch their sales momentum vanish at the finish line. It’s a frustrating reality for many business owners who don’t yet know how to choose a consumer financing partner that actually supports their entire customer base. You’ve likely felt the sting of a promising lead disappearing because a slow application process or a rigid credit requirement stood in the way. Every “no” from a lender is a lost opportunity for your business to expand, and you deserve a solution that acts as a bridge to your next breakthrough rather than a barrier to your success.
How do you transition from these limitations to a state of constant expansion? This guide provides the strategic blueprint to select a partner that doesn’t just process transactions, but actually fuels your upward trajectory. We’ll show you how to identify a multi-lender ecosystem that covers the full credit spectrum from prime to subprime. You’ll discover how to implement soft-pull technology that protects customer credit scores and secure the instant funding needed to keep your cash flow fluid. These criteria are the key to maximizing your approval rates and accelerating your business growth throughout 2026.
Key Takeaways
- Stop losing sales to prime-only lenders by switching to a partner that approves up to 85% of applicants across the full credit spectrum.
- Protect your customers’ financial health by implementing soft-pull technology that allows for instant pre-qualification without affecting credit scores.
- Maintain a healthy cash flow by prioritizing partners that deliver funds within 24 hours, ensuring your business remains liquid and ready for expansion.
- Master how to choose a consumer financing partner by asking critical questions about their credit waterfall and actual approval rates for subprime tiers.
- Unlock the power of a multi-lender ecosystem to ensure that the 30% of shoppers who require payment plans are never turned away at the point of sale.
Why Your Choice of Consumer Financing Partner Dictates Your Growth
Growth is never accidental; it’s the result of removing every possible barrier between a customer’s desire and their purchase. For many merchants, the final hurdle isn’t the quality of the product or the price point, but the accessibility of the funds. This is why understanding how to choose a consumer financing partner is one of the most critical strategic decisions you’ll make this year. Your choice of partner creates the ceiling for your revenue. If you partner with a “prime-only” lender, you’re effectively placing a cap on your potential by ignoring a massive segment of the market.
Consider the hidden cost of high decline rates. When a customer is rejected at the point of sale, you don’t just lose a single transaction; you damage your brand’s reputation and kill the sales momentum you worked hard to build. Statistics show that roughly 30% of shoppers won’t even consider a major purchase without a clear payment plan in place. By offering a robust financing solution, you aren’t just providing a loan; you’re providing a conversion tool. This shift in perspective often leads to a psychological breakthrough for the consumer, frequently resulting in an average ticket size increase of up to 15%. When customers feel empowered by flexible terms, they stop looking at the total price and start looking at the possibilities.
The Shift from Traditional Banking to POS Fintech
The days of sending customers to a local bank to fill out stacks of paperwork are over. Modern merchants are rapidly adopting “Financing in a Box” solutions that integrate directly into the sales flow. In 2026, consumers expect an instant, card-like experience that mirrors the speed of digital commerce. Moving away from slow, manual processes allows your team to focus on the relationship rather than the administration. These fintech-driven platforms provide the agility needed to capture sales in real-time, turning a hesitant “maybe” into a confident “yes” within seconds. Understanding the latest point of sale financing solutions driving growth in 2026 can help you identify which platform features will have the greatest impact on your conversion rates.
Defining Your Business Goals for Financing
Before you commit to a provider, you must align their capabilities with your specific objectives. Are you trying to recover lost sales from credit-challenged customers, or are you looking to drive high-volume transactions for premium products? This alignment is essential for long-term success. You must match your average ticket size to the partner’s lending limits. A partner that specializes in $1k retail purchases might not have the depth to support a $100k home improvement project. Determining these needs early is a vital part of why offering financing is a strategic necessity for modern scaling. Your partner should be a visionary facilitator that understands your industry’s unique transaction flow and helps you bridge the gap to your idealized future.
The Technical Vetting: Approval Rates and Credit Spectrums
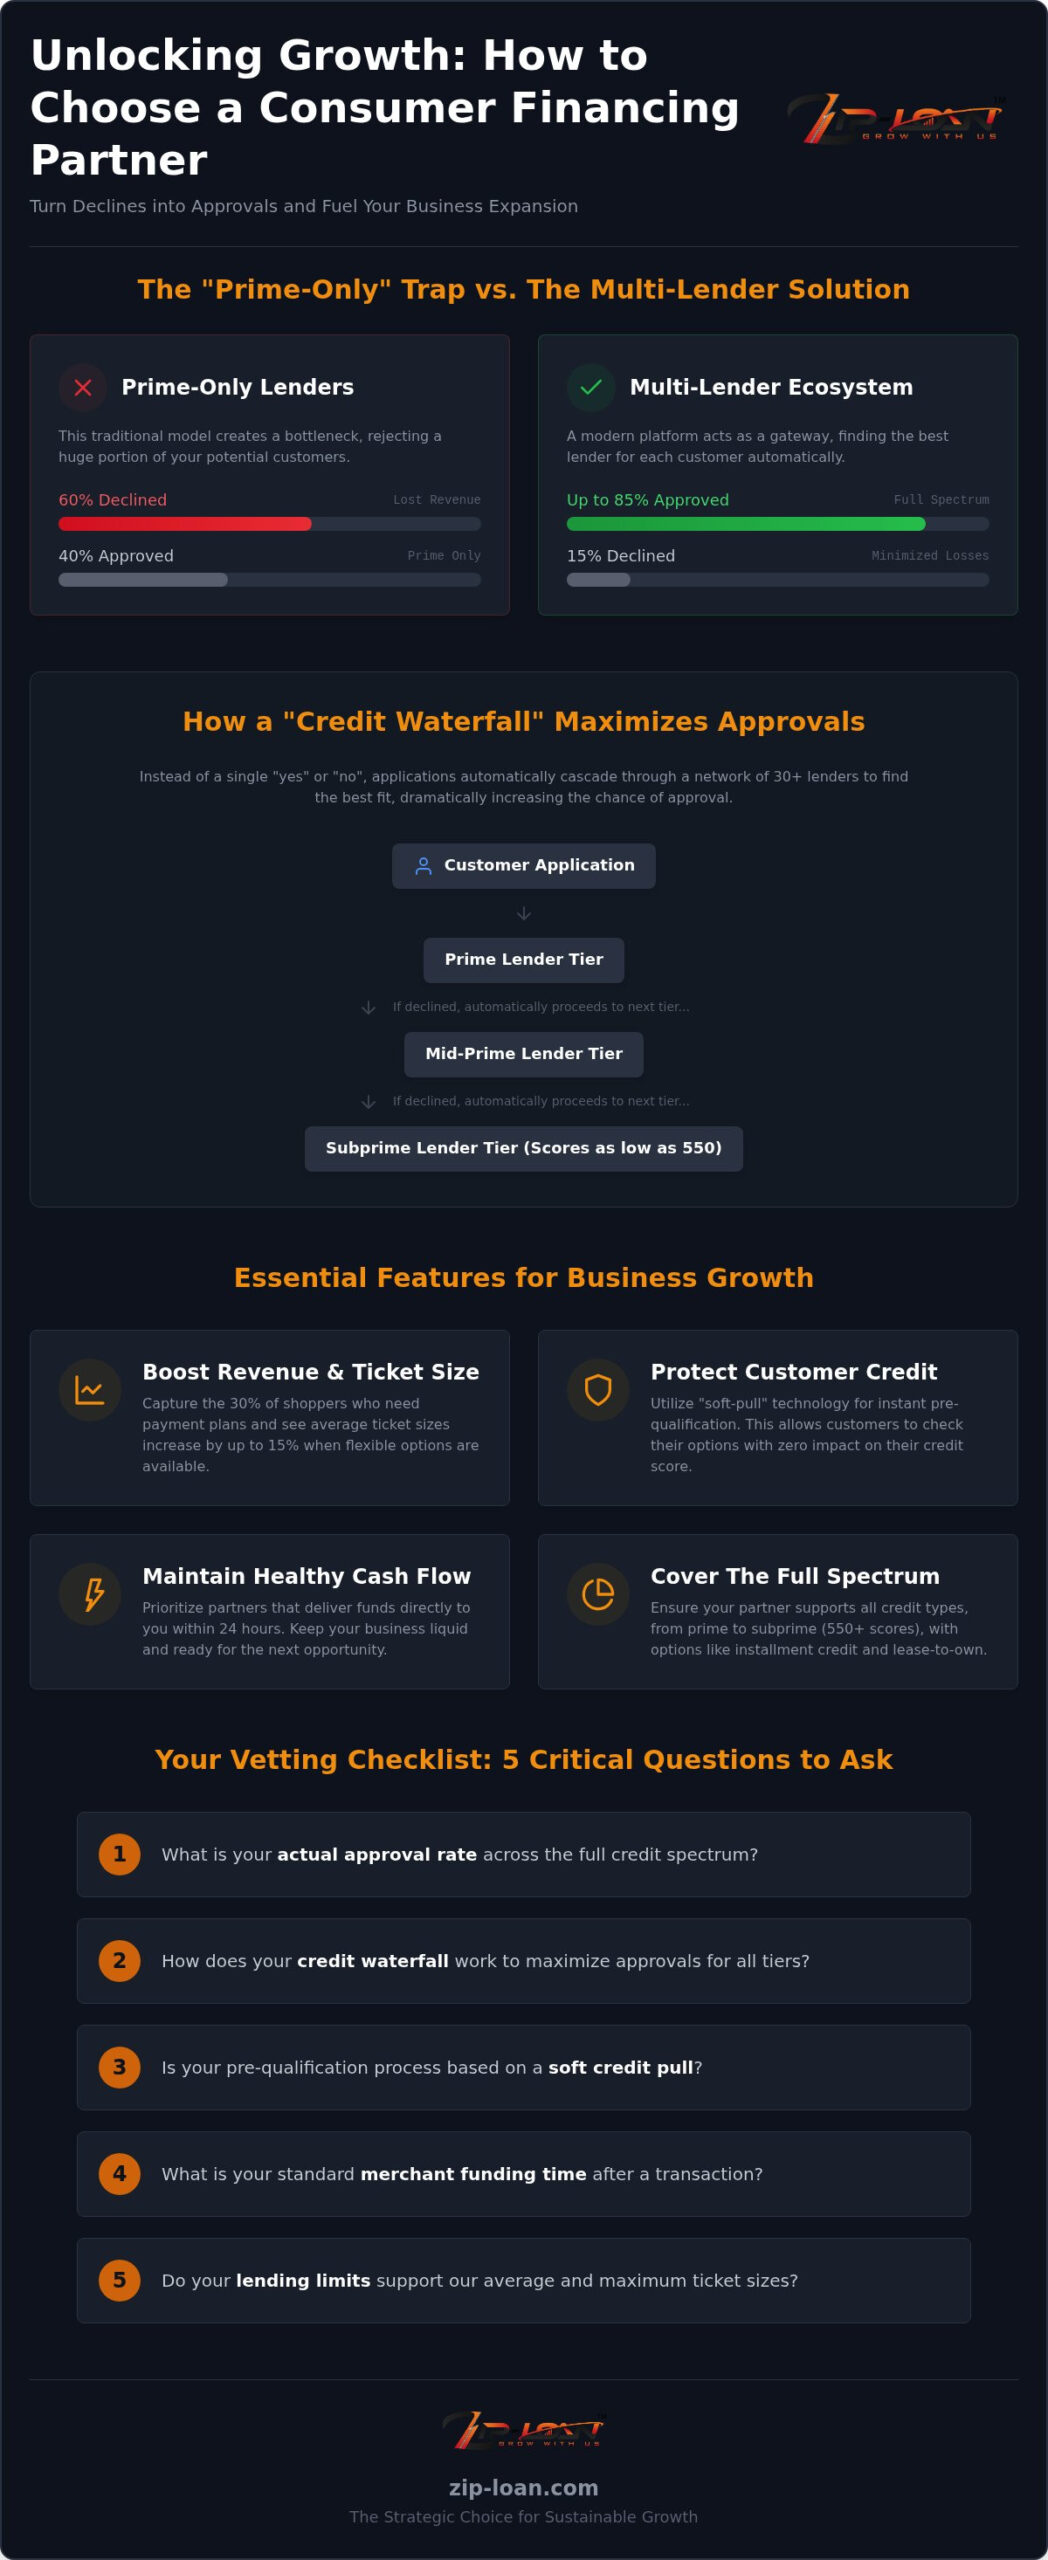
Analyze your current approval data to see if your financing solution is actually a growth engine or a silent sales killer. Many merchants fall into the “prime-only” trap, partnering with a single bank that only accepts customers with credit scores above 700. This narrow focus ignores the 60% of consumers who are typically declined by traditional big banks. Mastering how to choose a consumer financing partner requires you to look beneath the surface of a simple application and evaluate the technical infrastructure of the lending network. A single lender is a bottleneck; a multi-lender ecosystem is a gateway to untapped revenue.
The “Credit Waterfall” acts as a mechanism for cascading applications through multiple lenders to find the best possible match for the borrower. Instead of a binary “yes” or “no,” this system ensures that if a prime lender declines an applicant, the request automatically moves to the next tier. This cascading effect is how top-tier platforms achieve 85% approval rates. By utilizing a network of 30 or more lenders, you ensure that every customer has the highest statistical probability of securing the funds they need to move forward with their purchase.
Maximizing Approvals Across the Spectrum
Expand your reach by serving the full credit spectrum, from prime borrowers to those in the deep subprime category with scores as low as 550. Flexible partners offer diverse programs such as installment credit, lease-to-own options, and no-credit-needed solutions. This variety ensures that credit-challenged buyers feel welcomed rather than rejected. Implementing modern customer financing solutions that include soft-pull technology eliminates the friction of credit score anxiety by allowing customers to pre-qualify with zero impact on their credit score. It’s a risk-free way for them to explore their buying power while you maintain your sales momentum.
Speed and Limits: Instant Decisions Matter
Respect your customer’s time by demanding instant decisions at the point of sale. The “90% Rule” suggests that modern consumers expect an approval in seconds, not hours; any delay beyond that significantly increases the risk of cart abandonment. Your partner must also offer financial flexibility that matches your business model. Whether you are handling minor $500 repairs or $100k major renovations, the financing limits must be broad enough to cover your entire service catalog. You can explore industry-specific financing solutions to see how these limits apply to your particular niche. Ensuring your technical vetting is thorough will position your business as a leader in customer experience. If you’re ready to see how a multi-lender platform can transform your conversion rates, connect with a consultant today to discuss your specific growth goals.
The Merchant Experience: Integration, Funding, and Support
Technical approvals are only half the battle. Once you’ve secured a “yes” for your customer, the focus shifts to your own operational efficiency. Determining how to choose a consumer financing partner involves looking at how their platform interacts with your daily workflow. Does it create more work for your bookkeeping team, or does it streamline your cash flow? A visionary partner provides a seamless bridge between the sale and the deposit, ensuring that your business remains agile and focused on expansion. It’s about removing the friction that often exists between a signed contract and a funded account.
Cash Flow and Risk Management
Ongoing Support and Training
Your technology is only as effective as the people who use it. Your staff must feel completely comfortable presenting financing as a benefit rather than a hurdle. A supportive partner provides the training and dedicated account management needed to optimize your approach. This high-level consultancy is part of the ultimate growth strategy for customer financing. When your team views financing as an empowering tool, they become a catalyst for your business’s breakthrough. Dedicated support ensures that you’re never navigating technical hurdles alone, allowing you to stay focused on your primary goal: serving your clients and scaling your vision.
5 Critical Questions to Ask Potential Financing Partners
Interviewing a potential provider requires more than a surface-level look at their brochure. To truly understand how to choose a consumer financing partner that aligns with your 2026 expansion goals, you must dig into the mechanics of their operations. Ask these five targeted questions to separate the visionary facilitators from the simple vendors. These inquiries will reveal whether a partner is built to support your breakthrough or if they’ll become another barrier to your progress.
- What is your actual approval rate across all credit tiers, not just prime? Look for a partner that can consistently hit an 85% approval rate by serving the full credit spectrum, including those with scores as low as 550.
- Does your application process involve a hard or soft credit pull for pre-qualification? Soft-pull technology is the standard for 2026; it allows customers to explore their options without the fear of damaging their credit score.
- How many different lenders are competing for my customer’s business in your portal? A single lender is a bottleneck. You want a multi-lender ecosystem where 30 or more institutions are working to fund your sales.
- What are the total costs, including setup fees, monthly minimums, and transaction discounts? Transparency is the foundation of a healthy partnership. Avoid providers that bury fees in complex contracts or surprise you with hidden costs after enrollment.
- How quickly are funds deposited into my account once the customer signs? Cash flow is your business’s lifeblood. Demand a partner that delivers funding within 24 hours of the completed transaction.
Schedule a consultation to see our 30-lender ecosystem in action
Red Flags to Watch Out For
Protect your brand by identifying restrictive practices before you sign. Be wary of exclusive contracts that prevent you from utilizing other financing tools as your business scales. You should also watch for hidden “penalty interest” or pre-payment penalties that punish your customers for being responsible. Finally, avoid any platform that requires a manual, document-heavy approval process for small ticket items. These hurdles only serve to kill your sales momentum and frustrate your buyers, turning a potential breakthrough into a logistical nightmare.
The Transparency Test
Build long-term loyalty by prioritizing clear communication. Data shows that 95% of consumers rate clear, understandable terms as the most essential factor when choosing a financing plan. Your partner should provide an accessible APR calculator that allows customers to see exactly what they’re committing to before they click “accept.” Providing this level of transparency in terms reduces merchant liability and significantly lowers the number of customer complaints. When your customers feel informed, they feel empowered to invest more in your services, knowing there are no hidden surprises waiting for them.
Conclusion: Why ZipLoan is the Strategic Choice for 2026
Selecting the right financial ally is the final step in moving your business from its current state to its idealized future. Throughout this guide, we’ve explored the technical and operational benchmarks required to scale effectively. When you finally decide how to choose a consumer financing partner, you’ll find that Zip-Loan doesn’t just meet these standards; it redefines them. By replacing the traditional single-lender bottleneck with a robust multi-lender ecosystem, we ensure that your growth is never limited by a single bank’s rigid criteria. Our platform connects you with over 30 lenders through a single, streamlined application, delivering instant results that keep your sales momentum high.
The Zip-Loan difference is rooted in tangible outcomes that solve your most persistent pain points. We’re proud to facilitate an 85% approval rate, effectively capturing the 60% of customers who are typically turned away by prime-only institutions. This inclusivity is matched by operational speed, as we deliver funds to your account within 24 hours to maintain your business’s liquidity. Whether you’re managing $1,000 auto repairs or $100,000 extensive home improvements, our scalability ensures that no project is too small or too large for our network to handle. We act as a visionary facilitator, providing the tools you need to remove every barrier to purchase.
Empowering Your Business Success
Adopt a “100% Approval” mindset by ensuring every customer has a path to purchase. Zip-Loan serves as a catalytic tool that transforms your sales floor into a center for advancement and opportunity. We’re dedicated to a partnership aimed at your mutual success, providing the flexibility to serve the entire credit spectrum without compromise. This supportive approach is designed to make your business feel like it’s on the verge of a significant breakthrough. You can contact us to start your merchant enrollment and begin your journey toward optimized conversion rates.
Next Steps for Your Team
Transitioning to our platform is a frictionless process designed to respect your time and intelligence. Once enrolled, you’ll gain access to a personalized online portal where you can manage applications and track funding in real-time. We provide custom QR codes and text-to-pay options to modernize your point-of-sale experience immediately. To ensure your success is visible, you can utilize our Touch-n-Buy program for free marketing assets, including digital banners and physical POS displays. This comprehensive support system ensures that your team is fully equipped to present financing with confidence and clarity.
Unlock Your Business’s Latent Growth Potential
Success in 2026 requires more than just a great product; it demands a frictionless path to ownership for every customer who walks through your doors. By focusing on a multi-lender waterfall and prioritizing soft-pull technology, you remove the barriers that historically stifled your revenue. Mastering how to choose a consumer financing partner ensures that your business is equipped with an ecosystem that prioritizes your expansion over rigid lending limitations. You’re no longer just a merchant; you’re a facilitator of your customers’ goals.
ZipLoan provides the specialized tools needed to achieve this transition. With access to 30+ lenders in a single portal, you can confidently offer financing that boasts an 85% approval rate across all credit types. Our commitment to your cash flow is reflected in our 24-hour funding cycle, ensuring that your capital remains as dynamic as your vision. It’s time to leave the restrictions of prime-only lending behind and embrace a partner that sees your breakthrough as our own success. Merchants who want to stay ahead of the curve can explore how point of sale financing solutions are evolving in 2026 to drive higher conversion rates and capture more of the market.
The future of your business is built on the partnerships you forge today. We’re ready to help you scale with confidence, optimism, and the reliable support your vision deserves.
Frequently Asked Questions
How do I choose the right financing company for my small business?
Prioritize approval rates and lender diversity when evaluating how to choose a consumer financing partner for your specific industry. You need a platform that serves the full credit spectrum and integrates seamlessly with your existing point-of-sale workflow. Look for a partner that acts as a visionary facilitator, providing the tools to remove purchase barriers rather than just processing transactions.
What is the difference between a single-lender and a multi-lender financing platform?
The difference lies in the number of banks competing for your customer’s application. Single-lender systems rely on one bank’s rigid criteria, which often leads to high decline rates. In contrast, a multi-lender platform uses a waterfall system to cascade applications through a network of 30 or more institutions, significantly increasing the probability of a successful approval for every customer.
How much does it cost a merchant to offer consumer financing?
Merchant costs generally consist of a percentage-based discount fee on each financed transaction, functioning much like a standard credit card processing fee. A fair industry benchmark for this fee is around 2.99%, although rates can vary based on your specific industry. Avoid providers that demand high upfront setup costs or hidden monthly minimums that eat into your profit margins.
What happens if my customer defaults on their financing payment?
Merchant liability is eliminated in a zero-risk model where the lender assumes all responsibility for the credit risk. If a customer defaults on their payments, your business keeps the full amount of the funded sale. This approach allows you to focus on expansion and service delivery without the burden of debt collection or financial loss from non-payment.
Can I offer financing to customers with bad credit or no credit history?
Capture more sales by selecting a partner that serves the subprime market through lease-to-own and alternative credit programs. Many modern platforms approve scores as low as 550, allowing you to serve the 60% of consumers typically declined by traditional banks. This inclusivity ensures that credit-challenged buyers feel empowered to move forward with their purchases at your business.
How long does it take for a merchant to get paid after a customer is approved?
Expect to receive your funds within 24 hours of the completed transaction when working with a high-performance financing partner. Rapid funding is essential for maintaining a healthy cash flow, especially for contractors or healthcare providers who need to cover immediate labor and material costs. Choosing a partner that prioritizes daily deposits ensures your operational momentum remains uninterrupted as you scale.
Does offering financing actually increase sales conversion rates?
Increase your conversion rates by removing the psychological barrier of a high upfront cost. Data shows that 30% of shoppers won’t consider a major purchase without a payment plan available. By offering monthly installments, you empower customers to focus on the value of your service rather than the total price, often increasing average ticket sizes by up to 15%.
What is a soft-pull pre-qualification and why is it better for my customers?
Soft-pull pre-qualification allows customers to see their approval status and buying power without any impact on their credit score. This risk-free process builds immediate trust and encourages more shoppers to apply for financing. It’s a critical factor in how to choose a consumer financing partner because it reduces application anxiety and leads to a higher volume of completed sales. Businesses looking to maximize these benefits should explore comprehensive customer financing solutions for business growth that combine soft-pull technology with a multi-lender network for the highest possible approval rates.