
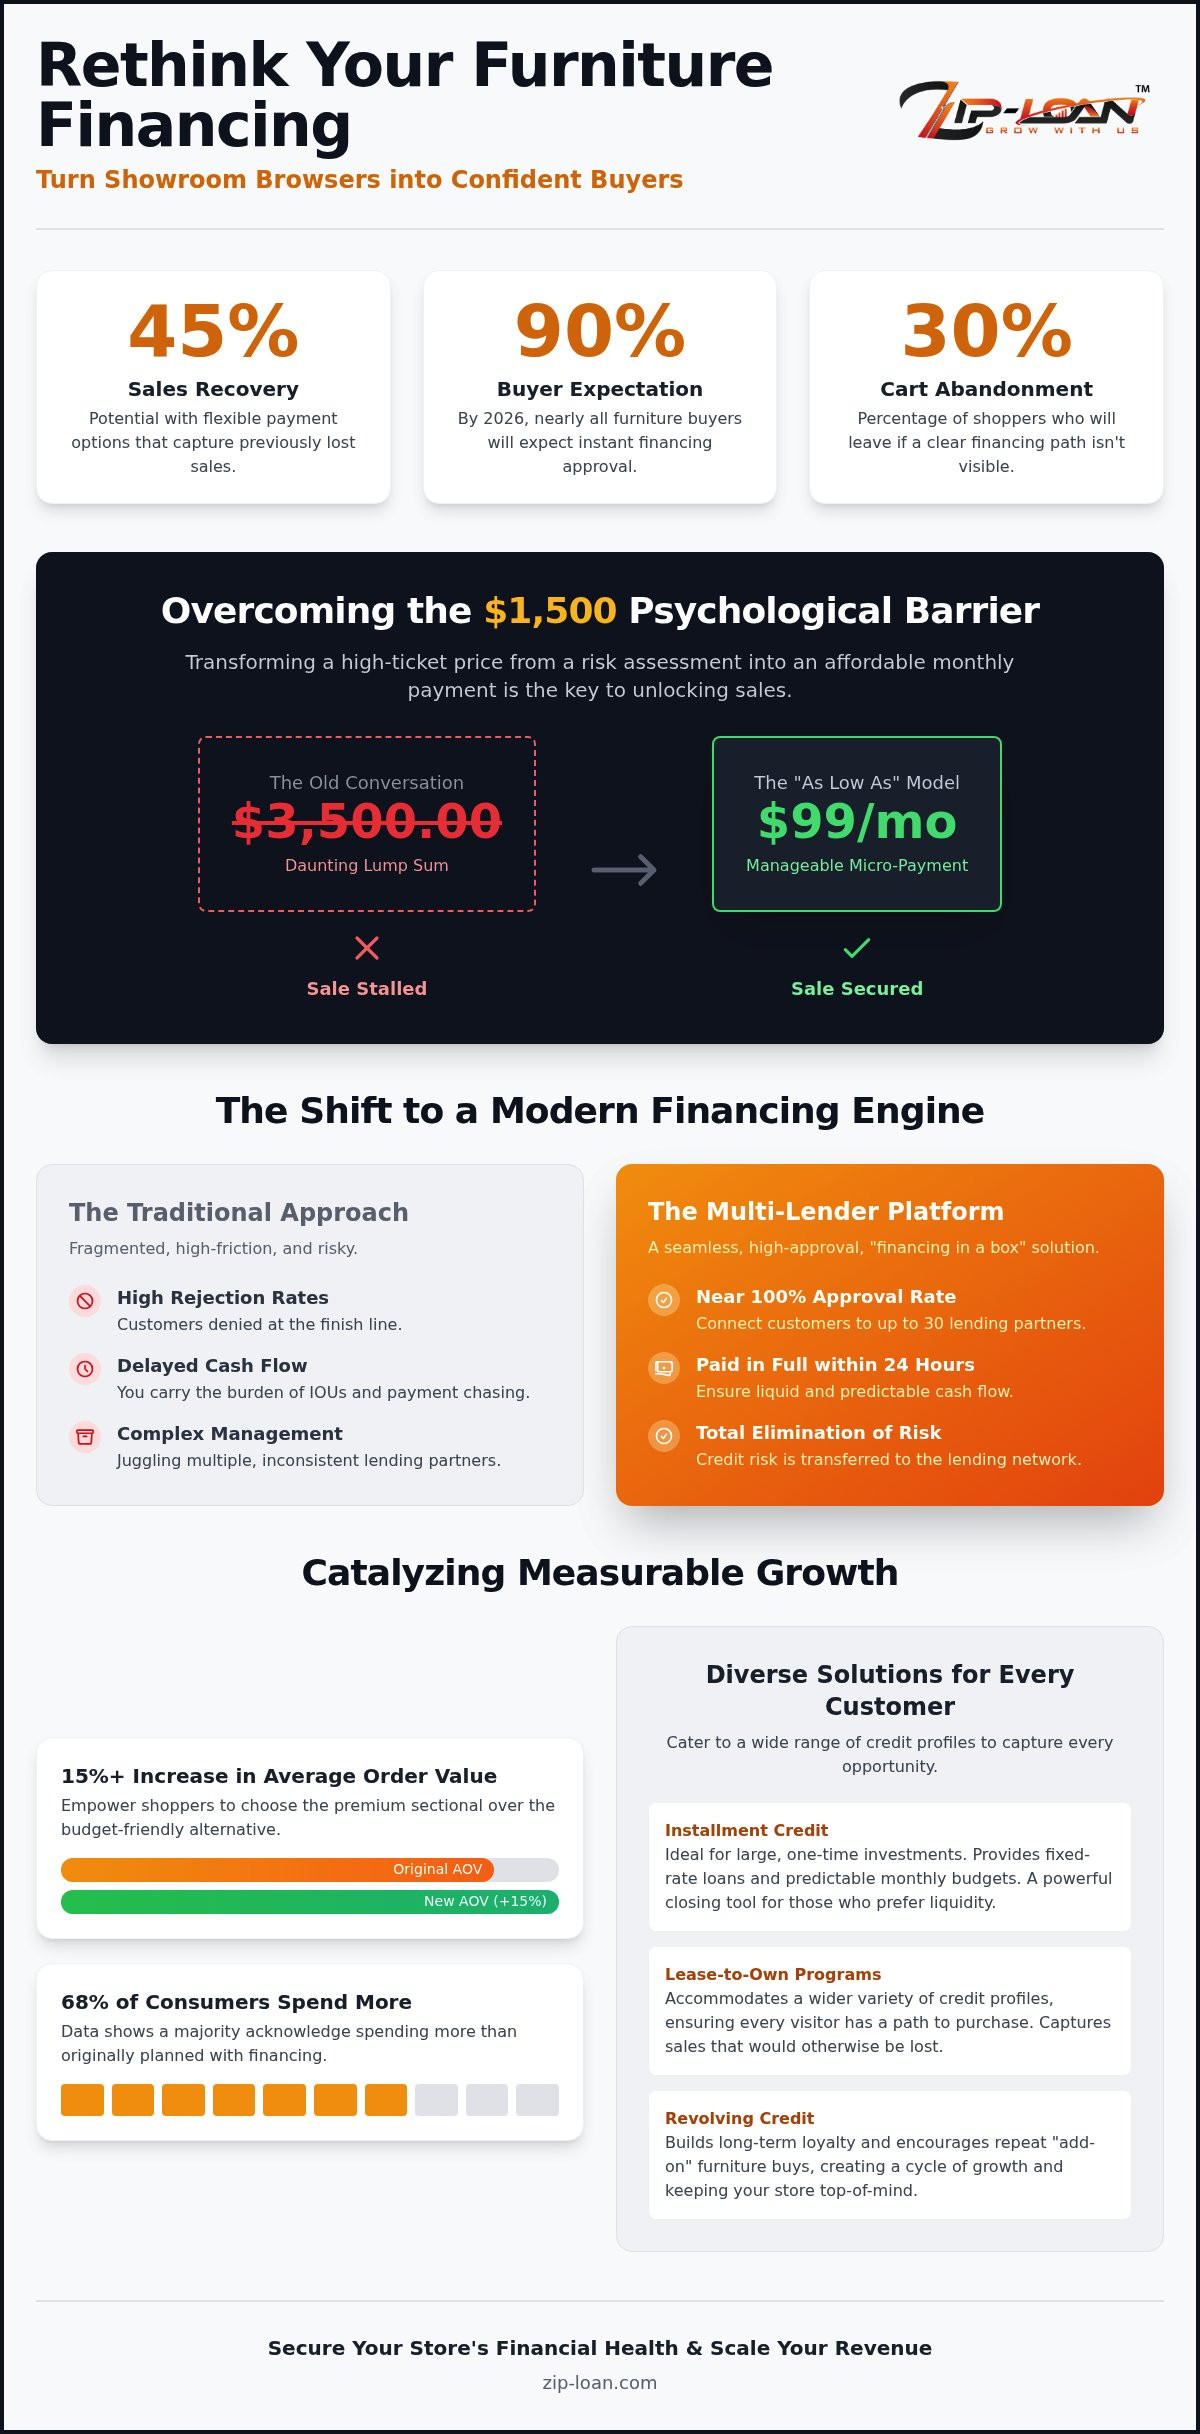
Did you know that flexible payment options can recover up to 45% of previously lost sales? In 2026, nearly 90% of furniture buyers expect instant approval before they even touch a fabric swatch, yet many independent retailers still lose ground to big-box competitors with deep-pocketed finance arms. If you’re tired of watching showroom browsers walk away because of high rejection rates from traditional lenders, it’s time to rethink your strategy for how to offer financing in a furniture store.
You already know that the difference between a stalled sale and a $35,000 whole-home transformation often comes down to the monthly payment. It’s frustrating to manage complex lending relationships only to have customers denied at the finish line. This guide reveals how to integrate a high-approval financing engine that turns hesitant browsers into confident buyers while increasing your average ticket size by 15% or more. We’ll walk through the transition from fragmented lending to a seamless “financing in a box” solution that achieves near 100% approval rates. By the end of this article, you’ll understand how to provide the flexible terms your customers crave while ensuring your business gets paid in full the moment the sale is finalized.
Key Takeaways
- Scale your revenue by learning how to bridge the high-ticket price gap, effectively increasing your average furniture ticket size by 15% or more through flexible payment options.
- Master the professional process of how to offer financing in a furniture store by leveraging a multi-lender platform that connects your customers with up to 30 different lending partners.
- Capture every sales opportunity by offering a diverse suite of solutions, including installment credit and lease-to-own programs, that accommodate a wide range of credit profiles.
- Reframe your showroom pricing strategy using the “As Low As” model to convert window shoppers into buyers by presenting manageable monthly micro-payments.
- Secure your store’s financial health with a seamless system that ensures you are paid in full within 24 hours, removing the burden of managing complex lending relationships.
Why Every Furniture Store Needs a Financing Strategy in 2026
Furniture remains the ultimate high-ticket category. With the average cost to furnish a three-bedroom home reaching between $22,000 and $35,000 in 2026, cash-on-hand is rarely the primary payment method for the modern shopper. Research indicates that 30% of shoppers will abandon their carts entirely if a clear financing path isn’t visible. This isn’t just a convenience; it’s a fundamental requirement for survival in a market dominated by national chains. Independent retailers must master how to offer financing in a furniture store to level the playing field against big-box giants who use captive finance arms to lock in loyalty. By providing these options, partners typically see a 15% increase in average order size, as shoppers feel empowered to choose the premium sectional over the budget-friendly alternative.
Overcoming the $1,500 Barrier
Psychology plays a massive role in the showroom. Once a price tag crosses the $1,500 threshold, the consumer’s brain often shifts from “desire” to “risk assessment.” This transition frequently stalls the sale before it even begins. However, by breaking that total down into manageable installments, you remove the friction. Data suggests that 68% of consumers acknowledge that flexible payment options lead them to spend more than they originally planned. In fact, four out of ten customers in 2026 will only commit to a purchase if they can secure financing at the point of sale. Learning how to offer financing in a furniture store allows you to pivot the conversation from a daunting lump sum to a comfortable monthly micro-payment. Integrating a Understanding Buy Now, Pay Later (BNPL) model allows you to capture this massive segment of the market that would otherwise walk out the door.
Immediate Cash Flow Benefits for Retailers
Growth requires capital, not a ledger full of IOUs. One of the most significant advantages of a modern financing strategy is the total elimination of merchant risk. When you implement a professional financing platform, you’re no longer the lender; you’re the facilitator. The credit risk is transferred entirely to a network of professional lenders. This shift means you get paid in full within 24 hours of delivery, ensuring your cash flow remains liquid and predictable. You can stop worrying about credit management or late payments and focus on what you do best: selling quality furniture. By removing the burden of in-house credit, you unlock the ability to scale without the traditional financial constraints that hold back smaller showrooms. It’s a catalytic shift that turns your payment desk into a sales recovery engine.
Understanding the Different Types of Furniture Store Payment Plans
Diversifying your payment options is the key to unlocking latent revenue and removing the barriers that stall showroom sales. When considering how to offer financing in a furniture store, you must move beyond a “one-size-fits-all” approach. Shoppers in 2026 expect a tailored experience that fits their unique financial health. By offering a mix of installment credit and lease-to-own programs, you ensure that every visitor finds a path to purchase. This variety signals that you aren’t just a vendor, but a partner invested in their home’s transformation.
Installment credit provides fixed-rate loans with predictable monthly budgets, making it ideal for customers furnishing entire rooms or making large, one-time investments. Using 0% APR promotional financing for 6 to 24 months acts as a high-powered closing tool for those who have the cash but prefer to maintain their liquidity. Meanwhile, private label revolving credit builds long-term loyalty, encouraging customers to return for “add-on” furniture buys once their initial balance is paid down. This creates a cycle of growth that keeps your store top-of-mind for future needs.
Installment Loans vs. Revolving Credit
Recommend fixed-term installment loans for large investments like bedroom sets or living room packages. These offer the structural clarity that 95% of consumers now demand. Revolving lines, however, provide a “furniture fund” for the future, allowing for smaller, repeat purchases over time. Staying compliant is non-negotiable for a professional brand. Always ensure your disclosures align with the FTC’s Credit Practices Rule to maintain trust and professional standards. This transparency is a cornerstone of being a dependable business partner to your community and protects your brand’s reputation.
The Role of Lease-to-Own in Furniture Retail
Traditional prime lenders often decline up to 60% of applicants, leaving a massive gap in your sales funnel and frustrating potential buyers. Lease-to-own programs solve this “no credit needed” dilemma for high-risk buyers. These options expand your total addressable market by focusing on income and employment history rather than just a credit score. This inclusive approach ensures that your store remains welcoming to those looking to scale their lifestyle regardless of their past financial challenges. If you’re ready to see how these programs look in action, you can reach out to a specialist to design your custom financing toolkit. By mastering how to offer financing in a furniture store across all credit tiers, you position your business as a visionary facilitator of your customers’ home dreams.
Step-by-Step: How to Offer Financing in Your Furniture Store
Implementing a robust payment strategy is the catalyst your business needs to transition from a local shop to a market leader. When you master how to offer financing in a furniture store, you’re not just adding a payment button; you’re removing the primary barrier to home transformation. This step-by-step approach ensures your transition is both seamless and immediately profitable, positioning your brand as a facilitator of the customer’s idealized lifestyle.
Choosing the Right Financing Partner
Start by selecting a multi-lender platform rather than a single bank. Why settle for one lender when access to 30 partners in a single portal can drive approval rates to 85%? This variety is essential in 2026 because nine in ten furniture buyers now expect an instant decision. You’ll want a partner that offers soft-pull pre-qualification technology. This allows your customers to check their eligibility without impacting their credit scores, which significantly reduces applicant anxiety. As you evaluate potential partners, ensure they provide comprehensive consumer financial protection regulations guidance to keep your store compliant with federal standards like the Truth in Lending Act. This level of professional oversight protects both your business and your clients.
Integrating Financing into the Showroom Flow
Visibility is the key to conversion. Use “Touch-n-Buy” posters and window clings to signal affordability the moment a guest enters. You’re aiming for a “Financing in a Box” experience where the tools are already at your fingertips. Place QR codes on every price tag to allow for instant, private pre-qualification on a customer’s own device. This digital-first approach creates a card-like experience that feels modern and low-pressure. If you prefer a more guided path, set up tablet-based kiosks where your team can assist with applications in seconds. It’s about meeting the customer exactly where they are in their journey.
Training your sales team is the final, most critical step in learning how to offer financing in a furniture store. Teach them to lead with monthly payments instead of the total ticket price. When a customer sees a $4,000 sofa as a manageable monthly investment, the psychological hurdle disappears. Once the sale is finalized, your platform should trigger funding within 24 hours of delivery. This ensures your cash flow remains as fluid as your sales process, allowing you to reinvest in inventory and continue your upward momentum. If you’re ready to see how these tools look in your showroom, you can connect with an enrollment specialist to get started.
Marketing Your Financing Options to Increase Average Ticket Size
Marketing your payment programs is where the real revenue expansion begins. It’s not enough to simply have the tools; you must weave them into every touchpoint of the customer journey. When you effectively communicate how to offer financing in a furniture store, you transform your showroom from a place of high-ticket anxiety into a destination of accessible luxury. This shift in narrative allows you to capture the 68% of consumers who admit they spend more when flexible payments are available. Beyond simple conversion, highlighting high-approval solutions allows you to recover sales that would otherwise be lost to lender declines, saving deals right at the finish line.
The “As Low As” strategy is your most potent tool for this transformation. By replacing daunting four-figure price tags with manageable monthly micro-payments, you lower the psychological barrier to entry. This approach is particularly effective during seasonal furniture events. Imagine promoting a 0% APR event for 24 months during a holiday blowout. It turns a “someday” purchase into a “today” reality, ensuring you don’t lose sales to big-box competitors with massive advertising budgets. It’s about making the dream of a beautiful home attainable for every visitor.
Upselling Through Affordable Payments
Use financing to bridge the gap between “good” and “best.” Often, a customer hesitates to upgrade to a premium mattress or a high-end leather sectional because of the immediate price jump. However, when you present that upgrade as a mere $20 or $30 difference in their monthly payment, the value proposition becomes undeniable. This strategy is also perfect for bundling. Instead of selling just a sofa, you can market a complete living room package including rugs and lamps, all under one installment plan. This overcomes the common “I need to wait” objection by showing the customer they can have the complete look now without draining their savings.
Digital Marketing for Financing
Your digital presence should act as a pre-qualification engine. Add clear pre-qualification links to your website’s header and product pages to catch browsers before they even enter your store. This proactive approach reduces showroom friction and builds confidence. On social media, run targeted ads that focus on “Instant Approval” for home upgrades rather than just product features. You can also leverage your existing database by emailing previous customers about their available revolving credit lines. Remind them that their “furniture fund” is ready for new arrivals, driving repeat business and long-term loyalty. Mastering how to offer financing in a furniture store through an omnichannel approach ensures your message reaches shoppers wherever they are.
Scale your average ticket size with ZipLoan’s marketing toolkit
Unlocking 100% Approval Potential with Zip-Loan
Transform your retail environment into a high-conversion sales engine by implementing the industry’s most versatile financing platform. Zip-Loan provides the definitive answer for those looking for how to offer financing in a furniture store without the traditional headaches of high rejection rates or slow funding. Our system delivers instant approvals for furniture tickets up to $65,000 in seconds, ensuring that your most ambitious sales close with confidence. By leveraging 30 lenders within a single portal, we offer a multi-lender advantage that approves 85% of applicants, capturing the vast segment of shoppers that prime-only banks often ignore.
Eliminate the financial uncertainty that comes with in-house credit management. Zip-Loan ensures zero-risk for the furniture merchant by transferring the credit responsibility to our extensive lender network. You get paid in full within 24 hours of delivery, maintaining the liquidity you need to reinvest in your 2026 inventory. To support your showroom’s visibility, our Touch-n-Buy dealer program includes free POS marketing assets. These professional tools, from window clings to digital banners, signal to every visitor that their dream home is within reach, often increasing average order sizes by 15% or more for our partners.
Why Zip-Loan Wins for Furniture Retailers
Empower your customers with terms that fit their lifestyle. We provide flexible repayment options ranging from 12 to 120 months, making even large-scale bedroom and dining sets affordable for any budget. Your clients will benefit from 0% APR promotional options and the freedom of no prepayment penalties, fostering a relationship of trust and transparency. We view our role as a consultative partnership. Our team works alongside you to ensure our “Financing in a Box” solution integrates perfectly with your existing showroom flow, removing the barriers that have historically limited your store’s growth.
Get Started with Furniture Financing Today
Initiate your store’s breakthrough with our simple merchant enrollment process. Once you’re onboarded, you’ll gain access to a real-time merchant dashboard that provides total visibility into your financing performance. This data-driven approach allows you to track approvals, funding, and customer trends with a few clicks. It’s time to level the playing field and compete directly with national chains. By choosing a partner that prioritizes your success, you’re not just adding a payment method; you’re securing your store’s future. You can contact Zip-Loan to transform your furniture sales and begin your journey toward optimized revenue today.
Scale Your Showroom Revenue with Confidence
The future of furniture retail belongs to those who remove the financial barriers between their customers and their ideal homes. By moving beyond single-lender limitations and embracing a multi-lender platform, you position your store as a visionary leader in the 2026 market. You’ve seen how mastering how to offer financing in a furniture store can recover nearly half of previously lost sales while boosting your average ticket size. It’s about more than just a payment button; it’s about providing the confidence your shoppers need to say “yes” to premium quality and complete room sets.
With an 85% average approval rate and access to over 30 lenders in one portal, you don’t have to watch qualified buyers walk away empty-handed. Our partners enjoy the security of receiving full funding within 24 hours of delivery, ensuring that rapid growth never compromises your cash flow. You now have the tools and the strategy required to facilitate a major business breakthrough through the Zip-Loan network.
Your business is on the verge of a significant transition. Take the first step toward a more profitable, high-approval future and watch your showroom potential finally reach its peak.
Frequently Asked Questions
How can I offer financing to my customers in a small furniture store?
You can offer financing in a small furniture store by enrolling in a multi-lender platform that provides a “financing in a box” solution. This allows you to provide the same flexible payment options as national chains without the complex overhead. By integrating the Zip-Loan portal, your small business can access 30 different lenders, ensuring that you can approve customers with a wide range of credit profiles right at the point of sale.
Do I need a high credit score for my business to offer financing?
No, your personal credit score is not the primary factor for merchant enrollment. The focus of our partnership is on your business’s ability to provide quality furniture to your community. Once enrolled with Zip-Loan, you can help shoppers with credit scores as low as 550 secure the items they need. This approach removes barriers to entry, allowing established retailers to scale their operations by focusing on sales growth rather than their own history.
What is the best financing for furniture stores with bad credit customers?
The most effective strategy for how to offer financing in a furniture store with diverse credit backgrounds is using a multi-lender portal. This system automatically routes applications to 30 different partners, including sub-prime lenders and lease-to-own programs. Because 60% of Zip-Loan customers were previously declined by prime banks, this multi-tiered approach is essential for achieving an 85% approval rate and capturing revenue that your competitors might be missing.
How long does it take for the merchant to get paid after a financed sale?
Merchants typically receive their funding in full within 24 hours after the furniture is delivered to the customer. This rapid funding cycle is designed to keep your cash flow fluid and predictable. By transferring the credit risk to the Zip-Loan lender network, you avoid the burden of waiting for monthly installments. You get the capital you need immediately to restock your inventory and continue your showroom’s upward expansion.
Will offering financing affect my customer’s credit score?
No, our soft-pull pre-qualification technology allows customers to check their eligibility without any impact on their credit scores. This is a vital tool for reducing shopper anxiety during the initial stages of a high-ticket purchase. By offering this transparent and risk-free process through Zip-Loan, you build trust with your guests. It encourages more browsers to apply, as they know their financial standing is protected while they explore their purchasing power.
Can I offer 0% interest financing in my furniture store?
Yes, you can absolutely offer 0% promotional APR options to your customers through the Zip-Loan platform. These “same-as-cash” promotions are available for 6, 12, 18, and 24 month periods. Highlighting these interest-free windows is a powerful way to compete with national big-box retailers. It acts as a catalytic closing tool, especially during seasonal sales events, by making premium furniture sets immediately affordable for qualified applicants.
What is the maximum amount a customer can finance for furniture?
Are there any merchant fees for offering furniture payment plans?
While there are percentage-based merchant transaction fees, these are designed to be competitive and scalable with your growth. These fees allow you to receive immediate payment while shifting all credit risk to the lender. When researching how to offer financing in a furniture store, it’s important to note that Zip-Loan includes free POS marketing assets through the Touch-n-Buy program. These materials help drive the 15% average increase in ticket size that offsets operational costs.