
The most effective merchant financing application in 2026 isn’t for a traditional bank loan; it’s the one that transforms your retail store into its own lending powerhouse. You’ve likely felt the frustration of watching a perfect sale evaporate because a single-source lender rejected your customer at the finish line. When you offer revolving credit for retail stores, you remove those barriers and take control of your growth. It’s exhausting to wait weeks for project funding or struggle with complex enrollment processes that feel like they require deep technical expertise just to get started.
This guide empowers you to master the application process for private-label financing, ensuring your customers get the “yes” they need in seconds. We’ll show you how to implement a 100% risk-free “Financing in a Box” solution that delivers payment in full to your account within 24 hours. We’ll walk through the streamlined enrollment steps, the latest 2026 regulatory shifts regarding credit data, and the exact path to scaling your revenue without the technical headaches. It’s time to stop acting as a middleman and start providing the catalytic tools your customers need to buy now.
Key Takeaways
- Identify the strategic shift from being a borrower with merchant cash advances to becoming a facilitator of growth through private-label platforms.
- Streamline your enrollment using a two-phase verification process designed to get your financing platform operational without requiring technical expertise.
- Offer revolving credit for retail stores to foster repeat business and secure immediate payment in full while the platform carries 100% of the risk.
- Maximize approval rates by leveraging soft-pull technology and a multi-lender network that provides instant decisions for tickets up to $65,000.
- Accelerate your cash flow with a system that ensures funds are delivered to your business within 24 hours of a customer purchase.
What is the Merchant Financing Application Process for Revolving Credit?
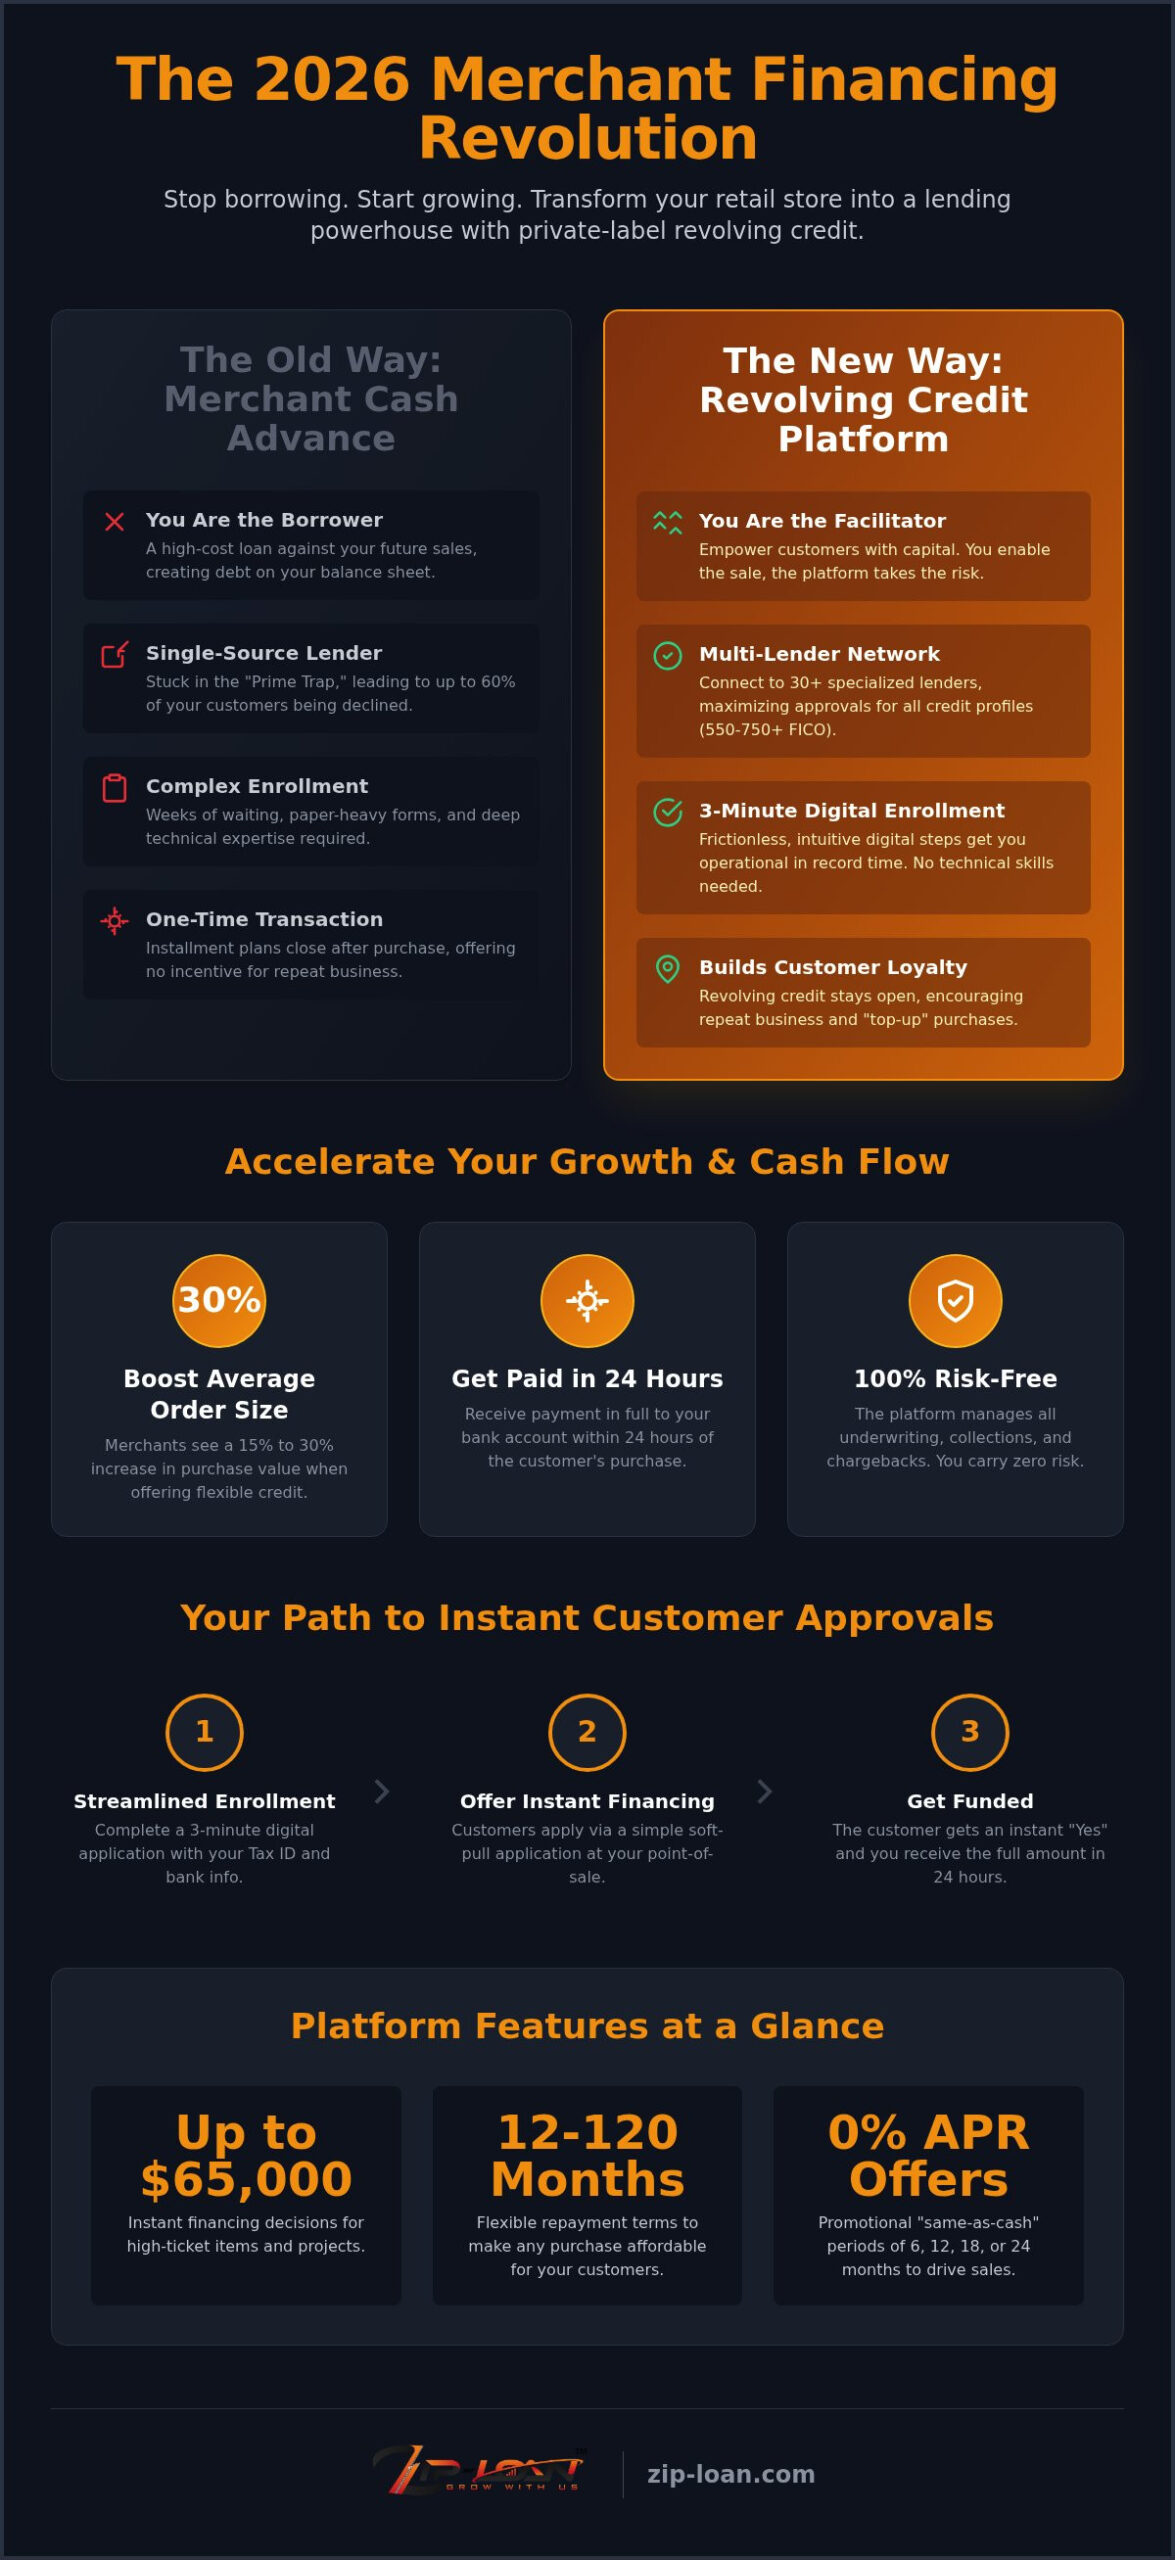
Stop viewing merchant financing as a debt your business carries. Many traditional financial resources confuse merchant enrollment with Merchant Cash Advances (MCA), but these two concepts live on opposite sides of the balance sheet. While an MCA is a high-cost loan against your future sales, merchant enrollment for revolving credit for retail stores transforms you into a facilitator of growth. You aren’t the borrower; you’re the expert guide providing your customers with the capital they need to finalize a purchase. By 2026, the application process has evolved from paper-heavy bank forms into a streamlined, three-minute digital enrollment that connects your POS system to a world of opportunity.
Why should you prioritize this transition? Data shows that merchants who offer private-label revolving lines see an average order size increase of 15% to 30%. This isn’t just a one-time boost. Because customers have an open line of credit, they’re statistically more likely to return for “top-up” purchases, creating a cycle of loyalty that one-off installment loans simply can’t match. You can explore the transformative impact of point-of-sale credit to see how this shifts the customer’s mindset from “can I afford this?” to “how much more can I get?”
The Multi-Lender Platform Advantage
Ditch the limitations of single-source lending. If you rely on a lone bank, you’re likely trapped in the “Prime Trap,” where up to 60% of your customers are declined because they don’t meet a narrow credit profile. Zip-Loan shatters this barrier by connecting your store to a network of 30 specialized lenders through a single portal. This multi-lender approach ensures that whether a customer has a 750 or a 550 FICO score, they have a high probability of an instant “yes.” This speed is vital for reducing cart abandonment in high-ticket retail environments, where even a five-minute delay can cost you a sale.
Revolving Credit vs. Traditional Installment Plans
Understand the mechanism behind the money. To grasp the full value, it helps to review What is Revolving Credit and how it differs from fixed installment plans. While installment plans are great for a single purchase, revolving credit for retail stores provides a flexible, ongoing line that stays open after the first transaction. This encourages repeat business and long-term engagement. Zip-Loan offers several key advantages in this space:
- Extended Terms: Offer repayment terms ranging from 12 to 120 months, making even $65,000 projects affordable.
- Risk Mitigation: The platform manages all underwriting and collections, ensuring the merchant faces zero risk of chargebacks.
- Rapid Liquidity: Receive payment in full within 24 hours of the transaction, maintaining your operational cash flow.
- Promotional Flexibility: Utilize 0% promotional APR offers for 6 to 24 months to drive seasonal traffic.
Step-by-Step: Applying for a Retail Revolving Credit Platform
Activating your platform shouldn’t feel like a chore. The 2026 enrollment journey is designed to be frictionless, moving you from application to offering revolving credit for retail stores in record time. It’s a structured path that replaces complex underwriting with intuitive digital steps, ensuring you can focus on sales rather than paperwork. This transition allows you to stop worrying about customer declines and start focusing on expansion.
Merchant Documentation and Requirements
Secure your credentials first. You’ll need basic business identifiers like your Tax ID and a bank account for those 24-hour fund deposits. During this initial phase, you’ll select your primary industry, such as Retail, Contracting, or Healthcare. This step is vital because it triggers the algorithm to match you with the most relevant lenders from our network of 30 specialized partners. Once verified, your Merchant Dashboard becomes the central hub for monitoring approvals and managing your cash flow in real-time.
Configuring Your 0% Promotional Offers
Customize your competitive edge by selecting promotional periods that fit your business model. You have the flexibility to offer 6, 12, 18, or 24 months of “same-as-cash” financing. Use the APR calculator during this phase to visualize how these terms impact your customers’ monthly payments. While these promotions involve a small discount fee, the payoff is a significantly higher conversion rate on high-ticket items. Balancing these fees with your sales targets is the key to maximizing your ROI.
Integration and training represent the final stretch. This involves placing QR codes on your showroom floor and utilizing text-to-apply links for mobile or remote sales. This digital-first approach ensures that revolving credit for retail stores is always accessible to your customers, regardless of where they choose to shop. Finally, empower your team through brief training sessions. When your staff understands how to present financing as a growth tool, they stop being order-takers and start being consultants. If you’re ready to scale, you can contact our enrollment team to start your verification today.
MCA vs. Revolving Credit: Which Application Fits Your Business?
Choosing the right financial tool requires understanding who is actually carrying the debt. In a traditional Merchant Cash Advance (MCA), you’re the borrower. You’re selling a portion of your future sales for immediate cash, often at a steep cost that can hinder your long-term flexibility. Conversely, when you apply for revolving credit for retail stores, your role shifts to that of a facilitator. You aren’t taking on a liability; you’re providing a bridge that connects your customers to the capital they need to finalize high-ticket purchases. This distinction is the difference between a business that’s managing debt and one that’s optimized to scale.
The cost analysis reveals a sharp contrast. MCAs typically use factor rates, which can mask effective APRs that occasionally reach into the triple digits. These advances also rely on daily or weekly bank withdrawals that can cripple your operational cash flow during slow periods. Point-of-sale (POS) revolving credit moves that cost to the consumer in the form of interest, or to the merchant as a predictable, one-time discount fee. Most importantly, while an MCA impacts your business credit through hard inquiries and increased debt ratios, merchant enrollment with a platform like Zip-Loan usually involves a soft pull that protects your credit standing.
The Hidden Risks of Merchant Cash Advances
Daily withdrawals are the silent killer of retail momentum. When an MCA provider takes a fixed percentage of your daily credit card receipts, your ability to restock inventory or pay staff becomes tied to a lender’s priority. This creates a cycle of “stacking” where businesses take on a second or third advance just to cover the first. It’s a dangerous path that leads away from true expansion. You can learn why financing is a significantly safer growth strategy than traditional debt by shifting the focus from your own borrowing to your customers’ buying power.
Unlocking Growth with Customer Credit Lines
Accelerate your revenue without the risk. When you facilitate a transaction through a multi-lender platform, you receive payment in full within 24 hours. The lender assumes 100% of the risk; if the customer defaults, your business keeps every penny of the sale. This platform also acts as a powerful recovery tool. Merchants report recovering up to 45% of previously lost sales from applicants who were declined by single-source lenders. For a deeper dive into these strategies, reference our guide on Consumer Financing Services to see how these credit lines drive sustainable retail growth in 2026.
Optimizing Your Application for Instant Customer Approvals
Speed is the ultimate currency in modern retail. When a customer stands at your counter or browses your digital catalog, the window for a successful high-ticket sale is remarkably narrow. You’ve already done the hard work of building interest; now, you must remove the final barrier of affordability. By optimizing how you present revolving credit for retail stores, you transform the financing conversation from a hurdle into an invitation. This isn’t just about providing funds; it’s about providing the confidence for your customers to say “yes” to the products they truly want.
Mastering the Soft-Pull Pre-Qualification
Soft-pull pre-qualification is a non-invasive credit check that allows retailers to offer financing without lowering a customer’s FICO score. This technology is a game-changer for 2026 consumer trust because it eliminates the “credit anxiety” that often prevents people from applying. You can place QR codes discreetly throughout your showroom or on service estimates, allowing customers to check their buying power privately on their own devices. For those with more challenging financial histories, integrating “No Credit Needed” or lease-to-own options within the same portal ensures you have a solution for every person who walks through your door.
Serving All Credit Types (Scores 550+)
Why settle for a platform that only approves the top tier of borrowers? Relying on a single lender often leads to high decline rates, which can alienate your most motivated buyers. Zip-Loan’s 30-lender network is designed to approve over 85% of applicants, including those with credit scores as low as 550. This broad reach is especially vital for auto-repair shops and contracting businesses where average tickets are high and immediate solutions are mandatory. You can explore the industries we serve to find specific approval strategies tailored to your unique business model.
Maximizing your success rate also requires a commitment to data accuracy within your merchant portal. Ensuring that customer information is entered correctly the first time prevents unnecessary underwriting delays that can stall a project. Beyond the technicalities, focus on transparency. Use clear, simple terms to explain the revolving credit for retail stores you offer, highlighting the promotional APRs and flexible repayment terms. When you integrate these financing options into the early stages of your sales conversation, you position your business as a partner in the customer’s success rather than just another vendor.
Apply now to start approving more customers today
Why Zip-Loan is the Gold Standard for Merchant Financing Enrollment
Zip-Loan stands as the definitive partner for businesses ready to shed the limitations of traditional lending. By consolidating a network of 30 specialized lenders into one intuitive portal, we’ve eliminated the “prime trap” that leaves so many motivated buyers empty-handed. Our platform provides instant approvals for amounts up to $65,000 across the retail, home improvement, and healthcare sectors. This isn’t just about offering revolving credit for retail stores; it’s about providing a scalable engine for your business growth. We’ve optimized every touchpoint to ensure that you can focus on your craft while we handle the complexities of capital.
The ‘Financing in a Box’ Solution
Simplicity drives adoption. We’ve engineered our platform to make offering financing as effortless as processing a standard credit card transaction. This “Financing in a Box” approach ensures that your team can present options with confidence and clarity. Once a sale is finalized, your business receives full funding within 24 hours, protecting your inventory levels and ensuring payroll is never a concern. This speed is a cornerstone of our service, allowing you to maintain operational fluidity. It’s telling that 60% of Zip-Loan customers were previously declined by prime lenders; our multi-lender strategy finds the “yes” where others only see risk.
Start Your 3-Minute Enrollment Today
Transforming your sales trajectory begins with a simple digital path. Our enrollment process is designed for the busy professional, requiring only a few minutes to verify your credentials and activate your secure merchant dashboard. Once enrolled, you’ll gain access to our Touch-n-Buy program, which provides free POS marketing materials to help you signal your new capabilities to every customer. We specialize in approving credit scores as low as 550, ensuring that your revolving credit for retail stores reaches the widest possible audience. You’ll also have the flexibility to offer repayment terms ranging from 12 to 120 months, making even the most ambitious projects accessible to your clientele.
Don’t let another sale slip away due to outdated lending models. You can Enroll with Zip-Loan now to gain real-time support and the tools necessary to unlock your business’s latent potential. Our expert guides are ready to help you navigate the 2026 retail landscape with a platform that is 100% risk-free and fundamentally growth-oriented.
Accelerate Your Path to Sustainable Retail Growth
Transitioning your business into a financing-enabled powerhouse is more than a technical upgrade; it’s a strategic breakthrough. By mastering the enrollment process and leveraging a multi-lender network, you remove the financial barriers that once stalled your momentum. You’ve discovered how to distinguish high-cost merchant debt from facilitator tools that empower your customers. Offering revolving credit for retail stores ensures that you never have to watch a motivated buyer walk away because of a rigid bank decline.
Success in 2026 belongs to the retailers who act as expert guides for their customers’ aspirations. With access to 30 lenders in one portal, you can provide instant approvals up to $65,000 while maintaining a seamless 24-hour funding cycle. This 100% risk-free platform allows you to focus on results rather than limitations. Your future expansion is just a three-minute application away.
Step forward with the confidence that your business is equipped to say “yes” to every breakthrough. We’re here to ensure your transition to a high-growth model is seamless and successful.
Frequently Asked Questions
How long does the merchant financing application process take?
Merchant enrollment takes approximately three minutes through our secure digital portal. Once you’re verified, your business can immediately start offering revolving credit for retail stores to every customer who walks through your door. For your shoppers, the point-of-sale approval happens in seconds, creating a card-like experience that doesn’t slow down the checkout line. This rapid turnaround ensures you never lose momentum during a high-ticket sales conversation or a busy retail shift.
Does applying for merchant financing affect my business credit score?
Enrolling as a merchant with ZipLoan typically involves a soft credit inquiry, which means your business credit score remains protected. We prioritize a frictionless onboarding experience that focuses on your business credentials rather than invasive credit checks. This allows you to scale your operations and offer new payment flexibility without the worry of lowering your own credit standing. It’s a strategic move designed to enhance your revenue potential while maintaining your financial health.
What is the difference between a factor rate and an APR?
A factor rate is a fixed multiplier used in Merchant Cash Advances, while an APR represents the annualized cost of a traditional credit line. Factor rates often mask high effective costs because they apply to the original loan amount rather than the declining balance. By choosing revolving credit for retail stores, you move away from high-cost merchant debt and toward a transparent APR model that is easier for your customers to manage and understand.
Can I offer revolving credit to customers with bad credit?
Yes, our multi-lender network is specifically designed to approve customers with a wide range of credit profiles, including scores as low as 550. Because we connect your store to 30 different lenders, we find approvals for over 85% of applicants. This inclusive approach means you can provide financing to shoppers who were previously declined by prime-only banks. You’ll capture sales from a broader demographic and build loyalty with underserved customer segments who need flexible payment options.
How quickly will I receive funds after a customer is approved?
You will receive payment in full within 24 hours of the transaction being finalized. Our system ensures that your cash flow remains consistent, allowing you to restock inventory or cover payroll without delay. Healthcare providers can even benefit from daily funding cycles. This rapid liquidity is a core advantage of our platform, ensuring that your business gets paid immediately while your customers enjoy the flexibility of paying over time through their approved credit lines.
What documents do I need to enroll as a ZipLoan merchant?
To begin your enrollment, you’ll need your basic business identifiers, including your Tax ID (EIN) and your business bank account information for direct deposits. We also require standard verification of your business credentials to ensure a secure partnership. The process is entirely digital and designed for speed, allowing you to move from application to activation in just a few minutes. This streamlined approach gets your financing tools into the field without any unnecessary administrative hurdles.
Are there prepayment penalties for my retail customers?
No, ZipLoan’s patient and retail financing programs do not include prepayment penalties or penalty interest. Your customers have the freedom to pay off their balance early without facing any additional charges or administrative fees. This transparency builds significant trust and encourages shoppers to utilize your credit lines for both emergency needs and planned upgrades. Providing a penalty-free experience ensures your customers feel empowered and respected throughout their entire repayment journey with your brand.
What happens if a customer defaults on their revolving credit line?
Your business is 100% protected because the lender network assumes all the risk associated with customer defaults. If a shopper fails to make their payments, you keep every penny of the original sale. This risk-free structure allows you to offer high-limit financing up to $65,000 without worrying about chargebacks or collection efforts. You can focus entirely on delivering exceptional products and services while the platform handles the complexities and risks of credit management.