
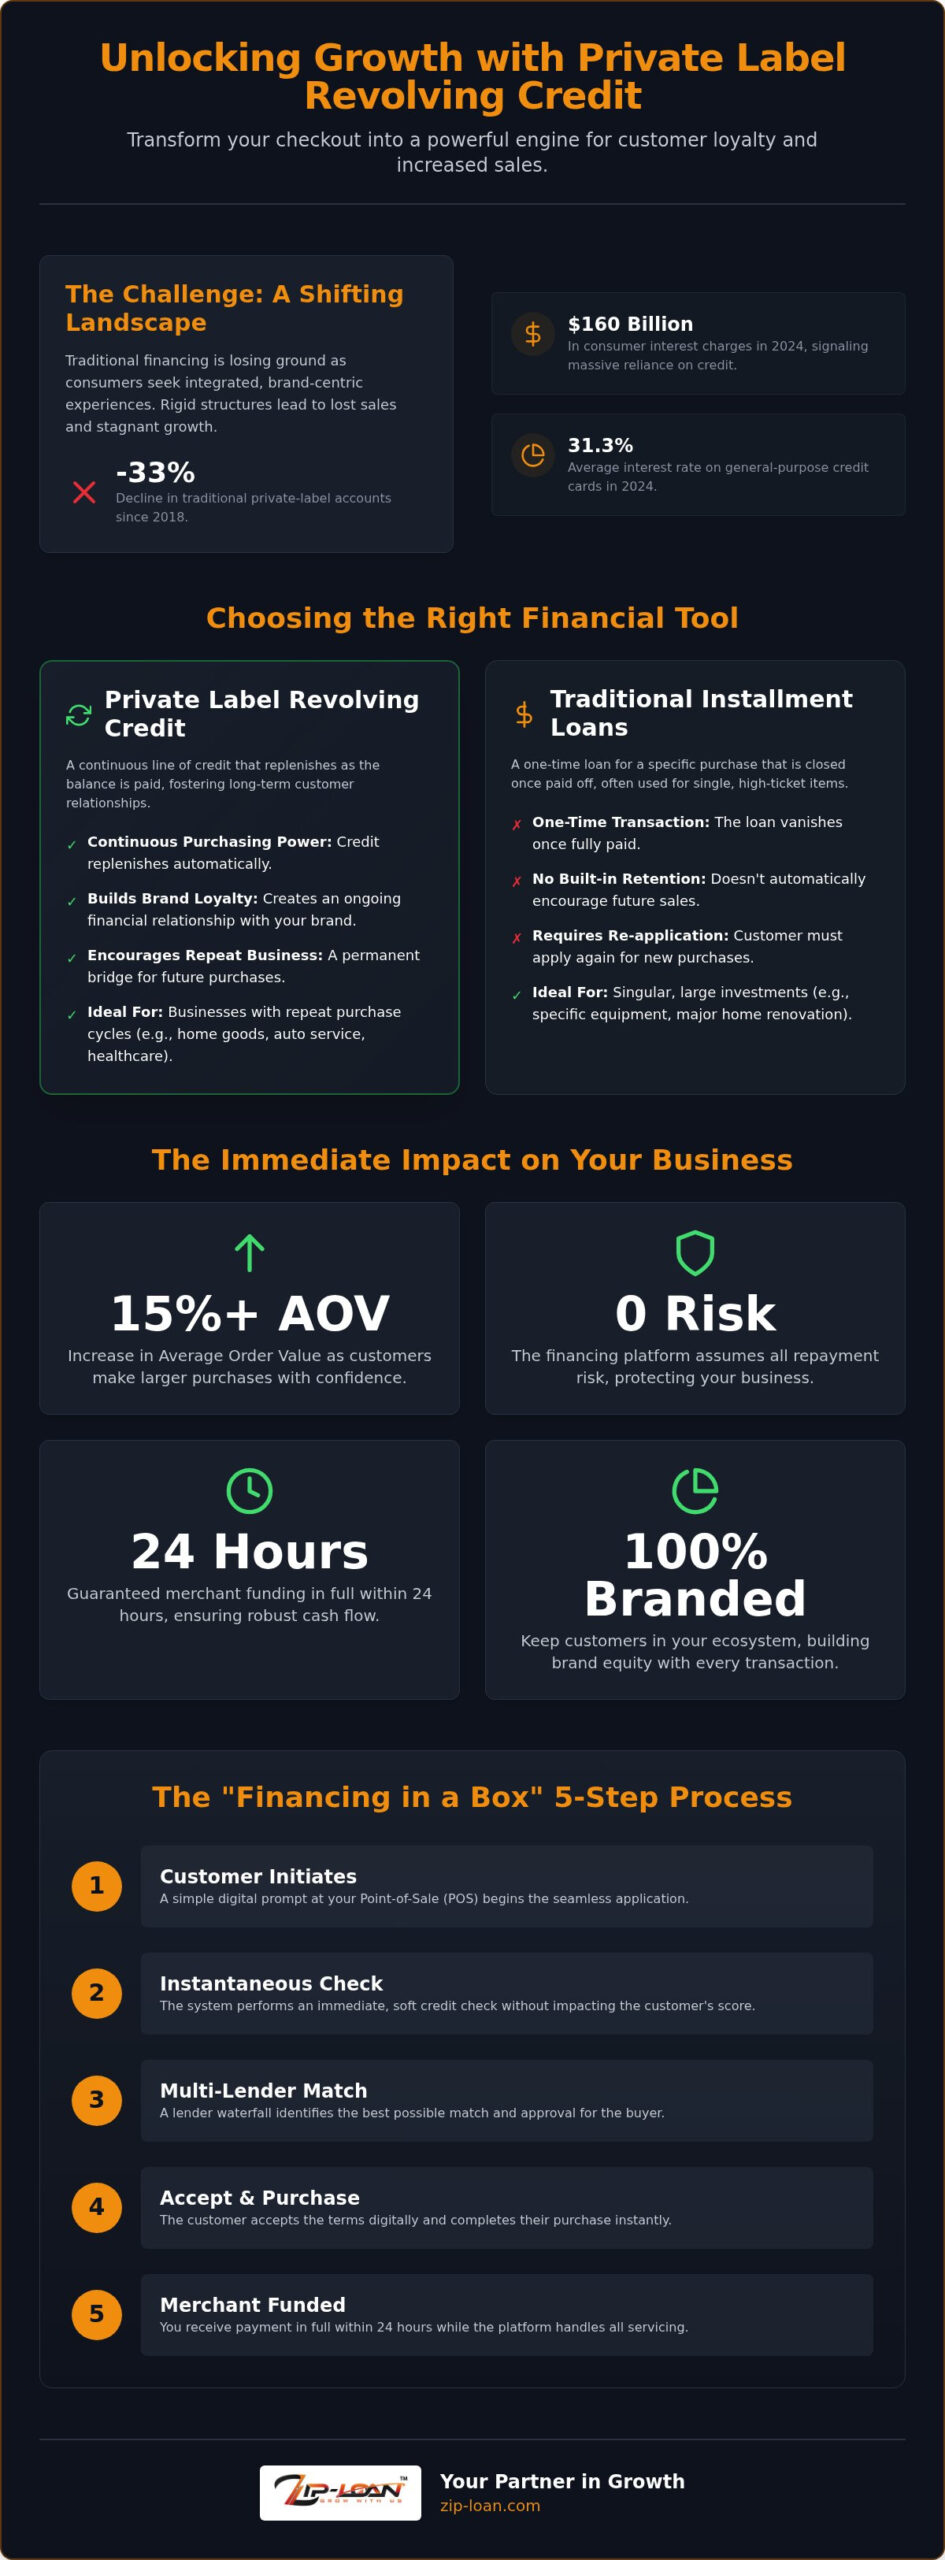
Why has the number of traditional private-label accounts plummeted by over 33% since 2018? It isn’t because consumers have stopped spending; it’s because they are searching for a more integrated, branded experience. You’ve likely watched potential customers walk away from big-ticket items or struggled with stagnant repeat purchase rates while competitors offer more flexible terms. It’s exhausting to lose market share to rigid financing structures that don’t reflect your brand’s value. Transitioning to a modern private label revolving credit strategy allows you to reclaim those lost opportunities and transform one-time shoppers into lifelong advocates.
You can turn your checkout process into a powerful engine for growth and customer retention. This guide provides the strategic framework you need to increase ticket sizes and build lasting loyalty through a seamless POS experience. We’ll examine how to navigate a market where consumer interest charges hit $160 billion in 2024 by offering a solution that feels like a partnership rather than a transaction. By the end of this article, you’ll understand how to leverage branded financing to remove purchase barriers and position your business for a significant breakthrough in 2026.
Key Takeaways
- Discover how a branded financial ecosystem transforms one-time shoppers into loyal advocates by providing continuous purchasing power.
- Learn the operational mechanics of private label revolving credit and how to seamlessly integrate a “Financing in a Box” solution into your existing POS system.
- Master the distinction between installment loans and revolving lines to ensure you offer the right financial tool for your specific business cycle and customer needs.
- Accelerate your sales growth by utilizing promotional APR offers that reduce consumer friction and significantly increase your average order value.
- Streamline your path to expansion with multi-lender platforms that deliver instant approvals and guarantee merchant funding within 24 hours.
What is Private Label Revolving Credit and Why Does it Matter?
In 2026, the definition of private label revolving credit has evolved from a simple plastic card to a sophisticated digital financial ecosystem. Understanding What is a private label credit card is the first step in realizing how these tools differ from co-branded or general-purpose cards like Visa. While a standard credit card is a tool for general spending, a private label line is a dedicated invitation to your brand. It removes the friction of high interest rates often found on general cards, which reached an average of 31.3% in 2024. By offering a branded line, you provide a tailored solution that signals a partnership aimed at mutual success.
To better understand how these financial tools operate and why they are essential for growth, watch this helpful video:
Total credit card balances exceeded $1.2 trillion in 2024, signaling a massive consumer reliance on credit. However, third-party “buy now pay later” (BNPL) services often dilute your brand equity by taking the customer out of your environment. When you offer your own private label revolving credit, you stop sending your customers to a third-party app to manage their payments. This transition keeps your brand front and center during every monthly statement and payment notification. It shifts the consumer’s mindset from a simple transaction to an ongoing relationship. They no longer see a purchase as a one-time expense but as an exercise of their pre-approved budget with your business.
The Mechanics of a Revolving Line
Unlike installment loans that vanish once paid, a revolving line is a permanent bridge to your brand. Once a customer pays down their balance, their credit limit replenishes automatically. This re-usable nature encourages ongoing engagement and reduces the need for you to “re-sell” the customer on every visit. Interest and minimum payments function similarly to standard cards, but the exclusivity ensures those funds return to your store. It’s a closed-loop system designed for longevity and operational fluidity, providing a reliable resource for future needs.
The Business Case for Branded Credit
Empowering your customers with a dedicated line of credit through a partner like Zip-Loan yields immediate, tangible results. Many merchants see their Average Order Value (AOV) climb by 15% or more as shoppers feel confident making larger investments. Beyond the initial sale, you build a proprietary database of spending habits that allows for precision marketing. Discover more about why financing is the key to unlocking latent potential. You aren’t just selling a product; you’re providing the capital for your customers to achieve their goals while securing your company’s growth.
How Modern Revolving Credit Platforms Work for Merchants
Optimize your checkout experience by adopting a “Financing in a Box” model that integrates directly into your existing point-of-sale systems. Modern platforms have distilled the complex lending process into a 5-step journey that prioritizes speed and merchant security. First, the customer initiates the process via a simple digital prompt. Second, the system performs an instantaneous check. Third, a multi-lender waterfall identifies the best match for the buyer. Fourth, the customer accepts the terms and completes the purchase. Finally, you receive payment in full within 24 hours while the platform assumes all repayment risk. This streamlined workflow ensures you focus on your products while the financial infrastructure handles the heavy lifting.
Deploying private label revolving credit shouldn’t require a complete overhaul of your operations. High-performance platforms like Zip-Loan are designed to sit quietly behind your brand, providing the necessary capital without the administrative headache. You get the benefit of rapid funding, ensuring your cash flow remains robust even as you offer flexible payment terms to your clientele. It’s about moving from a transactional mindset to an operational strategy that fosters growth and removes the barriers to high-ticket sales.
The Soft-Pull Pre-Qualification Process
Remove the anxiety of credit applications by utilizing soft-pull technology. Customers can scan a QR code or use a text-to-apply link to see their options in seconds without any impact on their credit scores. This transparency builds immediate trust and encourages shoppers to explore premium items they might otherwise ignore. Soft-pull technology acts as a conversion catalyst by providing instant clarity and removing the fear of a rejected hard inquiry. By the time they reach the checkout, they already know their spending power, which significantly reduces cart abandonment and increases overall confidence.
The Multi-Lender Advantage
Relying on a single bank is a common mistake that leaves revenue on the table. When you utilize a network of 30 lenders instead of one, you drastically increase your chances of securing an approval for every person who walks through your door. This “waterfall” approach allows the system to capture the “decline” market, serving customers with credit scores as low as 550. This inclusivity doesn’t increase your risk because the platform manages the individual lender relationships and the subsequent collections. You can learn more about Why Financing? is the essential tool for capturing a diverse customer base. If you’re ready to broaden your reach, consider how an expanded lender network could transform your revenue. You’ll find that partnering with a visionary facilitator like Zip-Loan is the key to unlocking your business’s latent potential.
Revolving Credit vs. Installment Loans: Choosing the Right Tool
Selecting the right financing tool is a strategic decision that shapes your entire customer lifecycle. While installment loans provide a structured path for single, large investments, private label revolving credit offers a flexible, open-ended resource that adapts to your customer’s changing needs. In 2026, we see a clear trend: consumers prioritize the ability to re-access funds without the friction of re-applying every time they need a service. This flexibility often outweighs the rigid schedules of traditional loans, especially for households managing fluctuating monthly budgets or unexpected life events. It’s about giving your customers a financial safety net they can use whenever they interact with your brand.
You might wonder if the costs associated with revolving lines deter potential buyers. While interest rates for private-label cards reached record highs in 2024, the perceived value lies in the accessibility and the peace of mind the credit line provides. When framed as a tool for manageable monthly payments and immediate access to necessary services, it becomes a value-add rather than a burden. It’s about removing the barrier of a large upfront cost and replacing it with a sustainable financial partnership that supports the customer’s long-term goals. By offering this choice, you position yourself as a supportive partner rather than just a vendor.
When to Use Installment Credit
Major one-off projects like a full roof replacement or a primary vehicle engine overhaul benefit from the clear “end date” of an installment plan. This structure provides a psychological sense of closure, as the customer knows exactly when the debt will be retired. If your business model revolves around these high-ticket, infrequent events, explore our Small Business Customer Installment Plans to see how to structure these offers effectively. These plans are ideal for customers who prefer a fixed repayment schedule with no surprises, allowing them to budget for a significant one-time expense with total clarity.
When Revolving Credit Wins
Private label revolving credit truly shines in industries defined by ongoing care or maintenance, such as dental practices, veterinary clinics, or HVAC services. By providing a dedicated line of credit, you create a “membership” feel that encourages customers to return for preventative care or sudden repairs. It makes the “add-on” sale at the point of service much easier. When a customer knows they have an open, branded line with your business, they’re more likely to say “yes” to that extra maintenance service or premium upgrade. This evergreen nature of the credit limit ensures that your brand remains the first choice for all their future needs, fostering a deep sense of loyalty and recurring revenue.
Strategic Implementation Across Key Industries
Training your team is equally vital to this transition. Shift the conversation away from “taking on debt” and toward “utilizing a budgeting tool.” When your staff frames the credit line as a way to manage monthly expenses while securing the quality they deserve, the customer feels empowered rather than burdened. This subtle shift in vocabulary positions your business as a partner in their financial health. You can explore the specific nuances of various Industries We Serve to see how Zip-Loan scales this approach across different sectors. It’s about moving from a transactional interaction to a consultative partnership that removes barriers to growth.
Contractors and Home Improvement
Healthcare and Patient Financing
In the medical field, the cost of procedures often dictates the timing of care. Branded financing removes this barrier, allowing patients to prioritize their health rather than their bank balance. This accessibility directly improves patient outcomes by ensuring they don’t delay treatments due to financial strain. Modern platforms also offer secure, transparent billing dashboards that simplify the administrative side of patient care for your office staff. It’s a visionary approach that balances professional care with financial fluidity, making high-quality healthcare accessible to a broader demographic while stabilizing your practice’s revenue.
Schedule a consultation to build your branded credit strategy
Getting Started with ZipLoan’s Branded Credit Solutions
Launch your journey toward total operational fluidity by completing the streamlined merchant enrollment process. Transitioning from application to a “live” status happens quickly, allowing you to begin offering private label revolving credit without delay. Once enrolled, you gain immediate access to a suite of free marketing assets, including branded QR codes, brochures, and banners. These tools are designed to catch the eye of your customers and spark the consultative conversations that lead to higher ticket sizes. You don’t have to guess about your success; the real-time merchant dashboard provides total transparency into every sale and funding event.
Experience the confidence that comes with the Zip-Loan promise of zero risk and 24-hour merchant funding. You’re paid in full for every transaction within a single business day, regardless of the customer’s repayment schedule. This ensures your cash flow remains robust while you provide the flexible purchasing power your clients demand. It’s a catalytic shift that removes the financial barriers between your current state and your business’s idealized future. By positioning yourself as a visionary facilitator, you build a foundation of reliability that keeps customers coming back.
Unlocking 100% Approval Programs
Capture the revenue you’ve been leaving on the table by utilizing a platform that identifies opportunities where others see obstacles. Zip-Loan captures 60% of customers who were previously declined by prime lenders, significantly expanding your reachable market. By offering approvals for credit scores as low as 550, you ensure that nearly every person who walks through your door has a path to purchase. These instant approvals act as a powerful sales conversion engine, turning window shoppers into committed buyers in seconds. As your transaction volume increases, you’ll see a corresponding rise in your business capital, providing the resources you need to scale at an accelerated pace.
Next Steps for Growth
Take the first step toward a significant breakthrough by consulting with a Zip-Loan expert to tailor your financing mix. Every business is unique, and a personalized approach ensures you’re utilizing the right blend of revolving lines and installment options. You can also integrate the APR calculator into your sales process to facilitate transparent, trust-building conversations with your customers. For a deeper dive into these strategies, read our Consumer Financing Services Pillar. It’s time to position your brand as an essential tool that empowers its customers to achieve their goals while you secure your business’s future.
Master Your Growth with Branded Financial Ecosystems
Your business is on the verge of a significant breakthrough. You’ve learned how private label revolving credit acts as a bridge between your current state and a future defined by loyal, high-value customers. By moving away from rigid third-party apps and adopting a branded ecosystem, you remove the barriers that cause cart abandonment and stagnant growth. You now have the strategic framework to offer a seamless financing experience that provides instant clarity to your shoppers.
Accessing 30 lenders through a single portal allows you to achieve approval rates exceeding 85%, ensuring you never leave revenue on the table. You benefit from 24-hour merchant funding, keeping your operations fluid while your customers enjoy the flexible purchasing power they crave. It’s time to stop losing market share to competitors and start positioning your brand as an essential partner in your customers’ lives. This transition isn’t just about a new payment method; it’s about unlocking the latent potential of your entire enterprise.
Take the lead in 2026 by providing the financial flexibility your audience deserves. Success is within reach, and we’re here to act as the expert guide for your next phase of expansion.
Frequently Asked Questions
What is the difference between private label credit and a standard credit card?
Private label revolving credit is a dedicated, closed-loop financial tool used exclusively at your business, whereas standard credit cards are open-loop and accepted anywhere. This exclusivity ensures that your customers return to you whenever they need to utilize their line again. By offering a branded option, you create a direct link between the customer’s purchasing power and your specific services, fostering a level of loyalty that general-purpose cards cannot match.
How does a multi-lender platform increase my customer approval rates?
A multi-lender platform utilizes a waterfall mechanism that routes a single application through a network of 30 different lenders. If a prime lender declines the request, the system automatically presents it to mid-tier and subprime partners. This collaborative approach allows you to achieve approval rates exceeding 85%. It ensures that you don’t lose customers simply because they don’t meet the rigid criteria of a single traditional bank.
Will offering revolving credit impact my customers credit score during the application?
Pre-qualification typically uses soft-pull technology, which has zero impact on a customer’s credit score. This allows shoppers to explore their spending power with confidence and without the fear of a rejected hard inquiry. A hard pull only occurs once the customer officially accepts the terms and finalizes the transaction. This transparency acts as a conversion catalyst, reducing consumer anxiety during the initial stages of the sales process.
How quickly can my business get paid after a customer is approved?
You receive payment in full within 24 hours of the transaction’s completion. This rapid funding cycle ensures that your business capital remains fluid and available for operational needs. While your customer enjoys the flexibility of manageable monthly payments over time, your cash flow is protected. You don’t have to wait for the customer to pay their balance; the platform handles the entire repayment lifecycle on your behalf.
What industries benefit most from private label revolving credit?
Service-based sectors with recurring needs, such as HVAC, dental, veterinary, and general contracting, see the most significant advancement from these programs. These industries often deal with emergency repairs or elective procedures where immediate capital is essential. By providing a dedicated line of credit, you enable these clients to say “yes” to necessary services today while securing their return for future maintenance or additional projects.
Can I offer 0% interest promotions with a revolving credit line?
Yes, you can leverage promotional APR offers, such as 0% interest for 6, 12, or 18 months, to close more deals. These promotions are highly effective at removing the “interest cost” objection during a high-ticket sale. They allow your customers to budget for their needs without the immediate burden of finance charges. It’s a strategic way to increase your average order value while positioning your brand as a supportive partner.
What happens if a customer defaults on their revolving credit payments?
Your business carries zero risk if a customer fails to make their payments. Once you are funded, the responsibility for collections and credit management shifts entirely to the lending network. This protection allows you to offer private label revolving credit to a diverse range of customers, including those with credit scores as low as 550, without worrying about your bottom line. You focus on delivering quality service while the financial infrastructure manages the risk.
Is there a minimum or maximum transaction size for revolving credit?
While specific limits depend on the lender and the customer’s profile, revolving lines can reach up to $100,000. This broad range allows you to facilitate everything from minor service calls to massive home renovations or extensive medical treatments. Having such a wide window of purchasing power ensures that you can accommodate nearly any project size, making your business the one-stop solution for your customers’ most ambitious goals.