
Nearly 78% of online shopping carts are abandoned before checkout, frequently at the exact moment a high-intent buyer faces sticker shock over a large lump-sum transaction. It’s deeply frustrating to watch motivated customers vanish at the final payment step simply because they are rejected by rigid, single-lender solutions. Fortunately, forward-thinking brands can successfully reduce cart abandonment with customer financing that transforms substantial upfront costs into flexible, accessible options. You already know that scaling your business requires removing every operational barrier at the point of sale.
How can your platform unlock this latent revenue and convert hesitant browsers into high-value buyers? Discover how point-of-sale customer financing eliminates checkout friction, overcomes sticker shock, and recovers high-ticket revenue. We will explore how implementing a robust multi-lender strategy can recover up to 45% of abandoned sales, drive higher average order values, and ensure immediate risk-free merchant funding the moment a transaction completes.
Key Takeaways
- Understand how payment shock drives late-stage checkout abandonment and why nearly 30% of high-intent shoppers walk away when flexible payment options are missing.
- Discover how to strategically reduce cart abandonment with customer financing by dissolving price hesitation through predictable, low-cost monthly installments.
- Identify the ideal financing structures, including installment credit and lease-to-own programs, tailored to your specific purchase thresholds and customer demographics.
- Master a frictionless integration strategy that utilizes multi-channel access points like SMS and QR codes to streamline the application process for every shopper.
- Learn promotional best practices for displaying dynamic payment calculations early in the buyer journey to maximize conversion rates on high-ticket items.
The Psychology of Cart Abandonment: Why High-Intent Buyers Hesitate
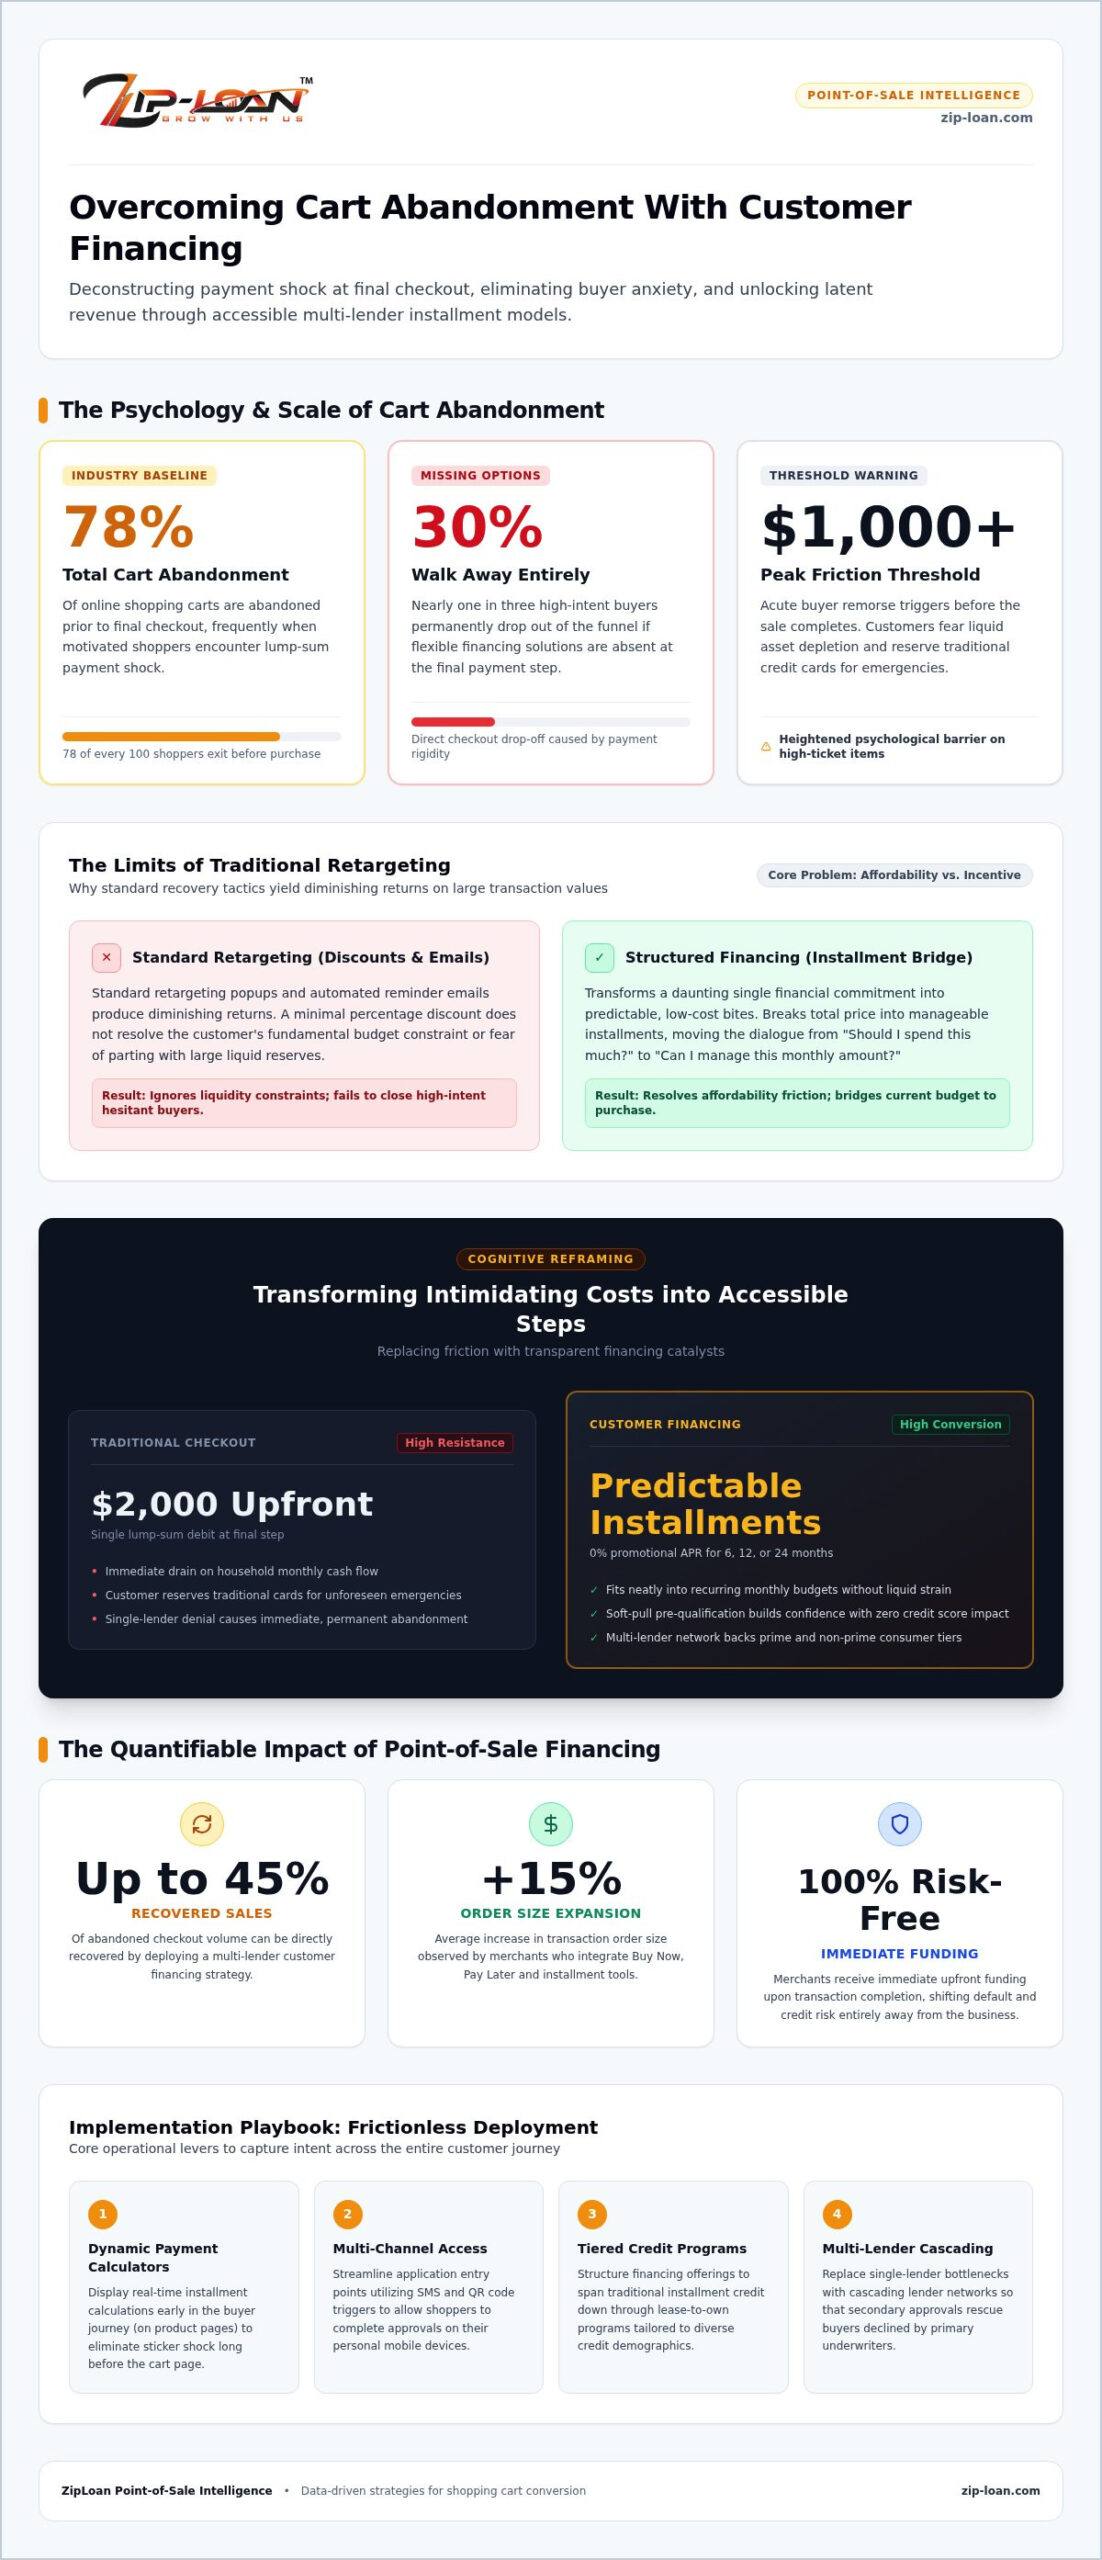
Payment shock serves as the ultimate barrier between a high-intent shopper and a completed transaction. While many retailers focus on fixing broken buttons or slow page loads, the actual driver of the global shopping cart abandonment rate is often a deep psychological reluctance to part with a large sum of capital at once. Recent research indicates that 30% of shoppers will abandon a purchase entirely if they don’t see flexible payment options at the final step. This isn’t just lost traffic; it’s lost potential for your brand. Data suggests that up to 45% of these abandoned sales are actually recoverable when merchants provide a clear path to affordability.
Watch this brief breakdown to see how these psychological barriers impact your bottom line:
Deconstructing the Final Purchase Hesitation
When an order value exceeds $1,000, buyer anxiety typically reaches its peak. Shoppers often experience acute buyer remorse before the transaction even occurs, fearing the immediate impact a large lump-sum payment will have on their monthly cash flow. Many consumers deliberately reserve their traditional credit cards for unexpected emergencies, making them hesitant to utilize their existing limits on a single luxury or necessity. You can explore how this dynamic shifts at why financing matters for growth-oriented businesses. By addressing this mental block, you empower your customers to move forward with confidence without compromising their financial security or liquid assets.
The Limits of Traditional Retargeting Campaigns
Standard retargeting tactics like discount popups or abandoned cart emails often fail because they don’t address the core issue of affordability. A small percentage discount rarely moves the needle for a customer who is fundamentally uncomfortable with the total price tag. These reminders produce diminishing returns because they ignore the budgetary constraints holding the shopper back. To truly reduce cart abandonment with customer financing, you must offer structured installments that break down the total cost into manageable, predictable bites. This approach transforms a daunting financial commitment into a catalytic investment. When you reduce cart abandonment with customer financing, you aren’t just selling a product; you’re providing a bridge between the customer’s current state and their idealized future.
How Customer Financing Directly Eliminates Checkout Drop-Off
Eliminate the friction that stalls your growth. When you offer flexible installment options, you change the customer’s internal dialogue from “Should I spend this much?” to “Can I manage this monthly amount?” Research into Buy Now, Pay Later market trends shows that these options are no longer a luxury but a fundamental consumer expectation. Merchants who integrate these tools often see an average 15% increase in order size. By providing a clear path to ownership, you don’t just close a sale; you build a partnership based on accessibility.
Breaking Down Lump Sums into Manageable Payments
Transform intimidating total balances into accessible commitments. Instead of a single $2,000 transaction, a customer sees a manageable monthly payment that fits their existing budget. Offering 0% promotional APR plans for 6, 12, or 24 months serves as a powerful catalyst for action. This transparency dissolves price hesitation instantly. You can see how this shift directly impacts your bottom line by exploring why financing is the definitive tool to reduce cart abandonment with customer financing. Soft-pull pre-qualification further enhances this by building immediate buyer confidence without impacting their credit score.
Expanding Purchasing Power Beyond Prime Credit
Adopt a multi-lender network to ensure no customer is left behind. Traditional single-lender solutions often reject non-prime shoppers, leaving revenue on the table. Our platform connects you to 30 different lenders, achieving approval rates that exceed 85% across all credit tiers. This waterfall approach is the ultimate antidote to declines. We frequently approve consumers with credit scores down to 550, including many who were previously declined by prime lenders. In fact, 60% of our approvals come from shoppers who couldn’t secure financing elsewhere. This broad reach is essential if you want to reduce cart abandonment with customer financing effectively.
Protecting Merchant Cash Flow with Zero Risk
Scale your business with total peace of mind. While your customers enjoy flexible terms, you receive your funding immediately. We assume all non-payment and credit default risks, so you don’t have to worry about collections or financial liability. Our instant merchant funding workflows ensure you receive payment within 24 business hours of the transaction completion. This upfront settlement safeguards your operational liquidity and provides the capital necessary for advancement. If you’re ready to remove these barriers, you might consider how to start your enrollment today.
Core Financing Structures That Convert Hesitant Shoppers
Deploying the right payment mechanism requires a deep understanding of your customer’s unique financial situation. Relying on a basic pay-in-four model leaves substantial revenue on the table, especially for larger ticket sizes up to $100,000. To effectively reduce cart abandonment with customer financing, you need a diverse suite of options that align with different purchase thresholds. Depending on the vertical and the consumer’s credit profile, repayment terms can range flexibly from 12 months up to 20 years. Reviewing comprehensive retail financing options helps merchants design a strategy that captures every potential sale.
Fixed-Term Installment Credit for High-Ticket Purchases
Accelerate big-ticket sales with structured installment loans designed for significant purchases up to $65,000. These programs offer predictable fixed monthly payments with transparent interest structures, ensuring zero prepayment penalties or surprise fees. This structure is ideal for high-consideration verticals where price hesitation is most acute. It provides immediate clarity for industries such as:
- Major home improvements and contracting services
- Elective healthcare and dental procedures
- High-end automotive repairs and parts
Lease-to-Own and No-Credit-Needed Alternatives
Capture the underserved non-prime market through flexible lease purchase mechanisms. Unlike traditional lending models that require strict prime credit history, lease-to-own programs focus on the consumer’s current income and employment stability. This compliance distinction allows merchants to serve credit-building individuals legally and responsibly. Furniture, mattress, and appliance retailers regularly utilize these alternative structures to recapture shoppers who would otherwise walk away due to a low credit score. It transforms a flat rejection into an empowering path to ownership.
Revolving Lines of Credit for Repeat Purchases
Foster long-term relationship growth with private-label revolving credit lines. Instead of a single closed-end contract, revolving accounts provide a dedicated credit line that customers can use repeatedly at your business. This ongoing relationship builds enduring brand loyalty and significantly increases lifetime customer value. Utilizing specialized consumer financing services allows your brand to establish a tailored credit program that keeps your business top-of-mind. When you reduce cart abandonment with customer financing through revolving lines, you secure both today’s sale and tomorrow’s repeat orders.
Deploying Financing at Checkout: Frictionless Integration Strategies
Moving from strategic planning to operational execution requires a clear, frictionless roadmap. You don’t need a massive development team or a months-long overhaul to modernize your payment stack. Instead, focus on a turn-key deployment that meets shoppers exactly where they are. Whether they are browsing on a desktop at home or scanning a code in a physical showroom, the goal is to reduce cart abandonment with customer financing by removing every technical hurdle. By following a structured 4-step sequence, you can activate high-tier lending capabilities across the diverse industries we serve without disrupting your current workflow.
Step 1 & 2: Platform Selection and Streamlined Enrollment
Begin by selecting a platform that offers a broad, multi-tier reach. You shouldn’t settle for a single-lender solution that limits your growth potential. Evaluate platforms that provide immediate access to 30 diverse lenders within a single application portal. This variety ensures your business can serve the widest possible credit spectrum from the start. The enrollment process should be rapid and empowering. Look for streamlined onboarding that avoids complex technical overhead or restrictive legacy lock-ins. Once active, utilize automated merchant dashboards to track transactions in real-time and maintain total oversight of your settlement schedule.
Step 3 & 4: Touchpoint Placement and Instant Adjudication
Strategic placement is the key to visibility. Embed pre-qualification triggers early in the buyer journey, including product landing pages and digital banners, rather than waiting until the final checkout screen. Providing multi-channel access via SMS links and QR codes allows customers to apply privately on their own mobile devices. These paperless applications are typically completed in under two minutes, creating a seamless transition from interest to approval. Because the system utilizes multi-tier lender routing, automated underwriting portals generate instant approval decisions in seconds. This speed is essential to reduce cart abandonment with customer financing, as it maintains the shopper’s momentum and eliminates the anxiety of a long wait.
Start your frictionless enrollment today
Best Practices to Promote Customer Financing and Maximize Conversion
Unlock the full potential of your payment strategy by making flexible options a visible, integral part of the buyer journey. It’s not enough to simply offer these tools; your customers must feel empowered to use them from the moment they land on your page. When you proactively reduce cart abandonment with customer financing, you transform your marketing from a series of transactional demands into a suite of accessible solutions. Proactive promotion ensures that shoppers never reach the point of sticker shock because they’ve already budgeted for their purchase using your flexible terms.
Upstream Transparency: Introducing Financing Before Checkout
Start the conversation early to anchor your customers in affordability. Research shows that only 36% of consumers currently recognize merchant financing options are available to them. You can bridge this awareness gap by displaying dynamic as-low-as monthly payment estimates directly beside your retail headline pricing. This level of transparency reassures shoppers before they even add an item to their cart. Promoting soft-pull pre-approvals early in the funnel builds immediate confidence, as customers know their buying power without any risk to their credit score. This upstream approach is one of the most effective ways to reduce cart abandonment with customer financing before hesitation even begins.
Omnichannel Promotion Across Digital and Physical Assets
Create a seamless promotional experience across every touchpoint. Leverage Touch-n-Buy promotional assets, including high-impact digital banners and professional physical point-of-sale displays. In a brick-and-mortar setting, utilize ready-made merchandising tools like window clings and counter cards to signal your partnership in the customer’s success. For digital shoppers, integrate financing pre-approval links into your abandoned cart recovery SMS and email sequences. Deploying QR codes in physical consultation environments allows for instant, self-service applications that respect the shopper’s privacy while accelerating the path to a finalized sale.
Consultative Sales Alignment and Staff Enablement
Empower your team to act as expert guides rather than just order-takers. Coach your retail associates to present financing proactively as a strategic budget-management asset. When staff members introduce soft-check pre-qualification guarantees early in a consultation, they remove the fear of rejection that often stalls high-ticket sales. Providing your team with direct access to customized portals ensures they can finalize purchases quickly once the customer is ready. If you’re looking to scale your conversion rates and broaden your market reach, partnering with Zip-Loan provides the multi-lender infrastructure necessary for sustainable growth.
Empowering Your Business Breakthrough
You’ve identified the psychological triggers behind checkout drop-off and mapped a clear trajectory for recovery. By aligning fixed-term installment credit and lease-to-own models with your specific vertical needs, you remove the financial friction that stalls high-value transactions. This comprehensive 2026 strategy ensures that you reduce cart abandonment with customer financing while simultaneously building long-term brand equity through transparent, accessible payment pathways.
The competitive advantage is clear. With access to a network of 30 lenders, you achieve approval rates exceeding 85% and recover up to 45% of previously lost high-intent shoppers. Because risk is entirely transferred to the lending network and funding is delivered within 24 hours, your focus remains where it belongs: on scaling your operations and serving your clients.
Your business is prepared for a significant evolution. Deploy these tools today to bridge the gap between your current performance and your idealized future of operational fluidity.
Frequently Asked Questions
How does offering customer financing directly reduce cart abandonment rates?
Offering flexible payments addresses the psychological barrier of payment shock at the final checkout step. Research shows that 30% of shoppers won’t complete a purchase if financing isn’t available. By breaking high-ticket totals into manageable monthly installments, you empower customers to say yes without depleting their liquid savings. This strategy helps reduce cart abandonment with customer financing by capturing motivated buyers who would otherwise walk away due to immediate cash flow constraints.
Will customer pre-qualification hurt my shoppers’ credit scores?
Shoppers can check their eligibility with total confidence because our platform uses a soft-pull pre-qualification process. This initial check doesn’t impact their credit score in any way. It allows customers to browse and see their potential purchasing power before they commit to a full application. By removing the fear of a credit inquiry, you encourage more shoppers to explore high-value items and move forward with their purchase journey without any negative financial consequences.
How quickly does our business receive payment after a customer finances?
Your business receives full funding quickly to maintain optimal operational liquidity and growth momentum. Once a customer transaction is finalized, funds are typically delivered to the merchant within 24 hours. This rapid settlement schedule eliminates the cash flow risks often associated with traditional payment plans or billing cycles. You don’t have to wait for the customer to pay their installments; instead, you get paid immediately while the lender network manages the repayment schedule.
What happens if a customer defaults on their loan or installment agreement?
Merchants enjoy a 100% risk-free financing environment because the lending network assumes all liability for non-payment or credit defaults. Once you receive your initial funding, you’re no longer responsible for the customer’s repayment performance. If a shopper fails to meet their obligations, the lenders manage the collections process directly. This protection allows you to focus on expansion and service delivery without the burden of credit management or financial loss from unpaid balances.
Can shoppers with low or non-prime credit scores get approved?
Our multi-lender platform significantly broadens approval possibilities for customers across the entire credit spectrum. We achieve approval rates exceeding 85% by routing applications through a network of 30 different lenders. This system often approves shoppers with credit scores as low as 550, including those previously declined by prime banks. In fact, 60% of our approvals come from individuals who couldn’t secure financing elsewhere, ensuring you don’t lose sales to rigid or outdated credit standards.
What size purchases can be covered using consumer financing platforms?
Flexible financing plans cover a wide variety of project sizes and retail ticket values to meet your business needs. The platform supports transactions ranging from under $1,000 to as high as $100,000 to suit different industries. Customers can receive instant approvals for amounts up to $65,000 in just seconds. This broad range makes it an ideal tool to reduce cart abandonment with customer financing for everything from emergency auto repairs to major residential remodeling projects.
How difficult is it to integrate point-of-sale customer financing?
Integration is designed to be a turn-key experience that avoids complex technical overhead or long development cycles. You can deploy financing triggers using simple web links, QR codes, or SMS prompts that customers access on their own devices. This frictionless approach means you don’t need a massive IT team to get started. The goal is to make offering payments as easy as a standard credit card transaction, allowing your business to scale quickly.