

Did you know that 60% of consumers declined by traditional prime lenders are still ready to invest in your business? It’s a staggering amount of revenue left on the table because the old financial guard hasn’t caught up to your customers’ needs. You likely feel the frustration of watching a high-value sale vanish at the finish line due to rigid credit requirements. It’s time to stop letting these hurdles dictate your trajectory and start offering a private label credit card for small business that empowers your growth.
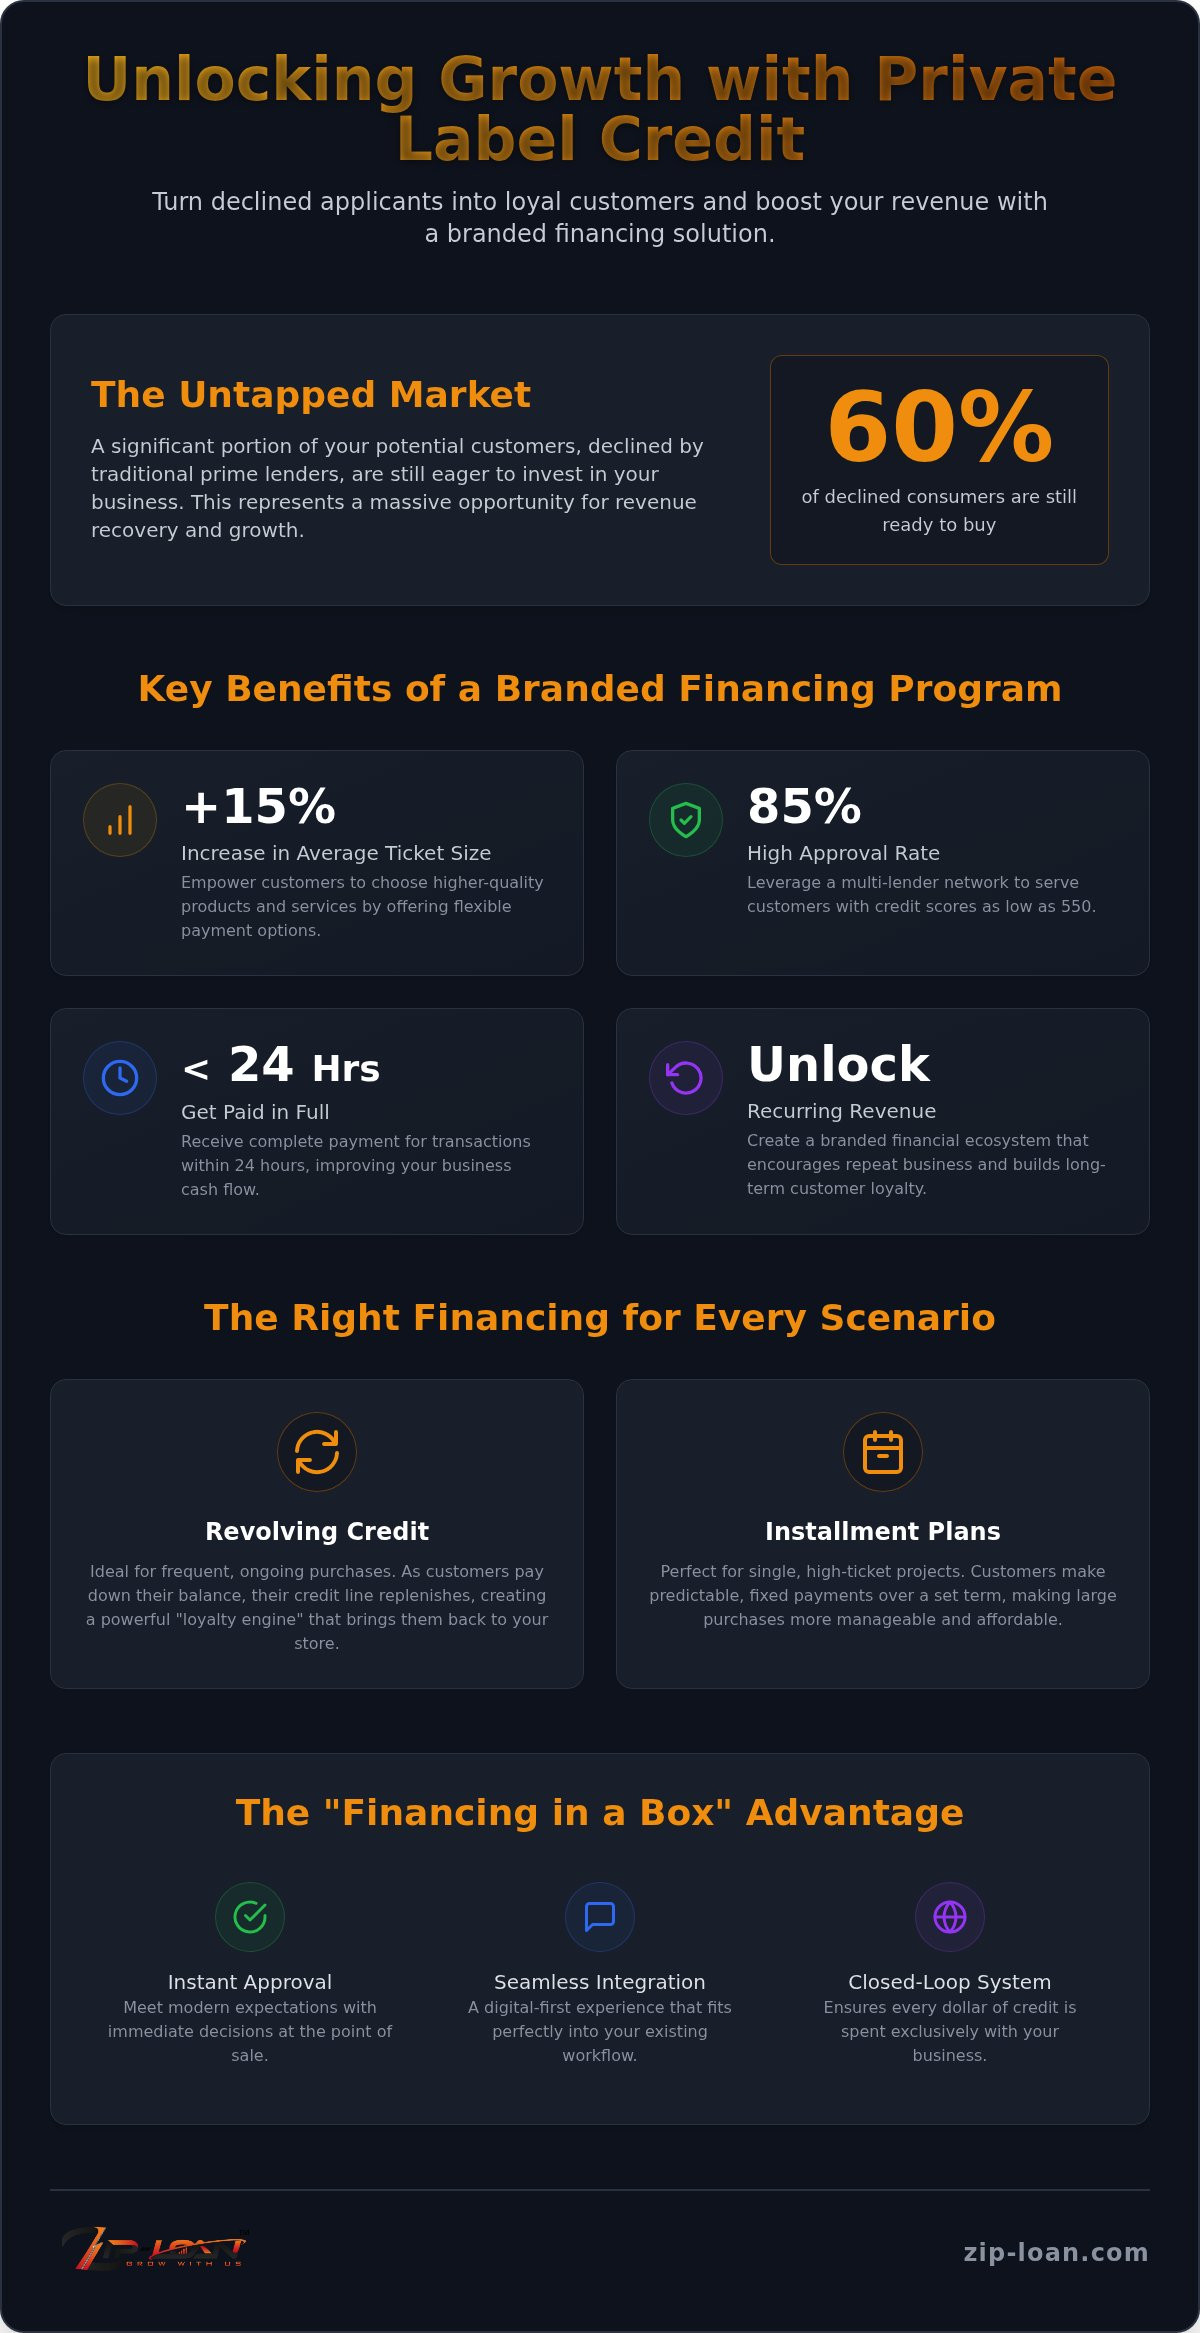
You agree that your business deserves a financing partner as ambitious as you are. This guide promises to show you how to implement a high-approval program that increases your average ticket size by 15%. We’ll explore how to provide a seamless, card-like checkout experience that captures sales from previously declined shoppers while ensuring you get paid in full within 24 hours. We’re going to dive into the technology and strategy needed to turn your point of sale into a powerful engine for expansion and long-term customer loyalty.
Key Takeaways
- Unlock recurring revenue by establishing a branded financial ecosystem that encourages customers to return specifically to your business for future needs.
- Maximize your profitability by implementing a private label credit card for small business, a strategic tool proven to increase average ticket sizes by 15%.
- Choose the ideal financing structure for every customer scenario, from revolving credit for frequent purchases to installment plans for one-off high-ticket projects.
- Integrate a seamless “Financing in a Box” solution into your existing workflow to ensure your business gets paid in full within 24 hours of a transaction.
- Leverage a multi-lender network to achieve an 85% approval rate, allowing you to capture sales from customers with credit scores as low as 550.
What is a Private Label Credit Card for Small Business?
Imagine giving your customers a dedicated key that unlocks your inventory whenever they need it. A private label credit card for small business is exactly that. It’s a closed-loop financing system designed to work exclusively within your storefront or digital platform. Unlike general-purpose credit cards that allow shoppers to spend anywhere, these branded tools ensure that the capital stays within your own business ecosystem. Understanding What is a Private Label Credit Card helps clarify why these systems are so effective at driving repeat traffic and brand dedication.
Private label credit is a branded revolving line that builds purchasing power exclusively with your brand. By offering a revolving line rather than a one-time loan, you create a permanent “loyalty engine.” As customers pay down their balance, their available credit refreshes, prompting them to return to your shop for their next purchase. This cycle transforms a single transaction into a long-term financial relationship that benefits both the merchant and the consumer.
To better understand this concept, watch this helpful video:
Closed-Loop vs. Open-Loop Systems
Distinguish your brand by offering a dedicated financing channel. Open-loop systems, such as co-branded Visa or Mastercard options, provide flexibility but often lead to capital leakage because customers can use that credit at your competitors. In contrast, closed-loop private label cards keep every dollar of purchasing power focused on your products. This creates a powerful psychological bond. When a customer carries your branded credit line, they don’t just see themselves as a shopper; they feel like a preferred member of your community. This sense of belonging is a primary driver for long-term retention and higher lifetime value.
The Evolution of Small Business Credit in 2026
The landscape of retail finance has shifted toward speed and accessibility. In 2026, the traditional plastic card is taking a backseat to digital-first “Financing in a Box” solutions. Modern shoppers move fast, and data shows that 9 in 10 customers now expect immediate approval at the point of sale. They won’t wait days for a bank to review an application. ZipLoan enables this “card-like” experience by removing the traditional banking hurdles that often stall growth when launching a private label credit card for small business. By using a multi-lender platform, you can offer instant approvals and seamless integration, positioning your business at the forefront of this digital evolution.
The Strategic Benefits of Offering Branded Revolving Credit
Unlock your business’s full potential by shifting the focus from price tags to purchasing power. When you provide a private label credit card for small business, you aren’t just offering another payment method; you’re providing a catalyst for larger transactions. Data shows that 4 in 10 shoppers would use financing if they knew it was an option at the point of sale. By making these funds accessible, you empower your customers to say “yes” to higher-quality products and more comprehensive services without the anxiety of a single large payment.
Implementing a branded revolving line typically leads to a 15% increase in average order size. This growth happens because customers feel confident expanding their project scope when they can manage the cost over time. Whether it’s a home renovation or a complex auto repair, flexible payment options remove the immediate financial barriers that often stall a sale. You can further incentivize these decisions by offering 0% promotional APR periods for 6, 12, or 18 months, effectively closing high-ticket deals that might otherwise be postponed or lost to a competitor.
Increasing Average Ticket Size and Sales Recovery
Transform your sales floor into a recovery engine. Many businesses lose up to 45% of potential sales because customers lack immediate cash on hand. For contractors, the correlation between financing availability and project scope is undeniable. ZipLoan partners report that project sizes are typically 16% larger when financing is integrated into the quote. In the automotive sector, shops often see average financed tickets reach $1,500, significantly increasing daily throughput and shop efficiency. By addressing the needs of the 60% of customers previously declined by prime lenders, you capture revenue that other firms simply ignore. If you want to see how this applies to your specific field, explore the industries we serve to find tailored solutions.
Building Brand Loyalty and Customer Lifetime Value
Foster a lasting connection that goes beyond a single transaction. A revolving credit line encourages repeat business far more effectively than one-time installment loans. Once a customer has a dedicated line of credit with your brand, you become their first choice for future needs. Launching a private label credit card for small business also allows you to gather valuable data on purchasing habits, which you can use to inform smarter marketing strategies. By focusing on low monthly payments, you reduce price sensitivity and keep your brand top-of-mind. This approach ensures that your business isn’t just a vendor, but a long-term partner in your customers’ success. Transitioning to this model is the key to unlocking consistent growth and securing your idealized future.
Private Label Credit vs. Installment Loans: Which is Right?
Selecting the correct financial toolset is a pivotal decision for your growth strategy. You must determine if your business model thrives on recurring interactions or high-impact, singular transactions. A private label credit card for small business excels in environments where customers benefit from a reusable line of credit. In contrast, installment loans provide a structured path for major, one-off projects. Understanding the nuances between these two options allows you to tailor your checkout experience to match customer behavior and maximize your sales potential.
The true breakthrough for your business comes from the ability to offer multiple credit products through a single, streamlined portal. Instead of forcing customers to navigate different applications for different needs, you can provide a unified “Financing in a Box” experience. This versatility ensures you never turn away a viable sale, regardless of the customer’s preferred repayment structure.
Revolving Credit for Retail and Healthcare
Retail and healthcare providers often see the highest ROI from revolving credit lines. Consider a dental practice or a specialized retail shop. When a patient secures a revolving line for an initial procedure, they’re far more likely to return for follow-up care because their financing is already established. This “re-use” factor is a powerful retention tool that builds long-term loyalty. Even with a standard 2.99% discount fee, the long-term value of a loyal, financed customer far outweighs the initial transaction cost. It creates a frictionless path for future spending that keeps your brand top-of-mind.
Installment and Lease-to-Own for Big-Ticket Items
Big-ticket industries like HVAC, roofing, and home remodeling typically lean toward installment credit or lease-to-own solutions. These sectors deal with essential, high-cost repairs where a fixed-term payment plan feels more manageable for the consumer. However, traditional lenders often leave a massive gap in the market by rejecting those with less-than-perfect scores. By integrating lease-to-own options, you can effectively serve the “No Credit Needed” segment. This is essential for capturing the 60% of customers previously declined by prime lenders. Learn more about the power of installment credit and how it serves as a foundation for these major sales.
ZipLoan’s multi-lender approach is why our partners achieve an 85% approval rate. By offering all three credit types in a single application, you provide a safety net for every shopper. You get paid in full within 24 hours of the transaction, while your customers get the flexibility they need to move forward with their projects today.
How to Launch a Private Label Credit Program in 2026
Accelerate your business evolution by moving from concept to execution in weeks, not months. Launching a private label credit card for small business has never been more accessible thanks to modular “Financing in a Box” technology. The first step involves a simple merchant enrollment where you define your specific financing parameters. Do you want to offer 6 month or 12 month interest free periods? You decide. Once enrolled, you can integrate your system via QR codes, text to pay, or direct web links, ensuring a frictionless experience for every shopper regardless of how they choose to browse your inventory.
Empower your sales process with soft pull pre-qualification. This technology allows customers to check their eligibility instantly without impacting their credit scores, which is a major concern for 2026 shoppers. By identifying eligible buyers early, you remove the fear of rejection and build immediate trust. Finally, ensure your team is trained to introduce these options at the start of the conversation. When financing is presented as a tool for expansion rather than a last resort, your close rates will soar. Teach your staff to lead with monthly payment amounts rather than total project costs to keep the focus on affordability and immediate gratification.
Seamless Integration and Merchant Onboarding
Experience the efficiency of a workflow designed for the modern merchant. Our “instant approval” system moves from application to full funding within 24 hours, keeping your cash flow consistent and predictable. You can monitor every step through a centralized Merchant Dashboard, providing real-time visibility into loan statuses and pending transactions. This transparency allows you to schedule work or ship products with total confidence. Perhaps most importantly, the multi-lender network absorbs 100% of the default risk. This zero risk nature for the merchant ensures your business remains protected while you focus on scaling your operations toward your idealized future.
Marketing Your New Financing Options
Visibility is the key to maximizing your program’s impact. Use high impact POS materials like window clings and brochures from the Touch-n-Buy program to signal your flexibility to every passerby. Digital presence is equally vital. Add financing banners to your website and include links in your email signatures to ensure every digital touchpoint reinforces your commitment to customer growth. Consistent branding across these channels tells your customers that you’re an established, supportive partner. You can easily find the best financing solutions for your industry to see how leaders in your field are currently leveraging these tools to capture more market share.
Why ZipLoan is the Ultimate Partner for Small Business Credit
Elevate your business by partnering with a platform that refuses to let sales slip through the cracks. Implementing a private label credit card for small business requires more than just a software link; it requires a robust financial engine capable of saying “yes” when others say “no.” ZipLoan provides this exact advantage by leveraging a powerful 30-lender network. While traditional single-bank programs often reject anyone without a perfect credit history, our multi-lender approach ensures that one application reaches dozens of potential backers. This competition among lenders is what allows our partners to achieve an 85% approval rate, even for customers with credit scores as low as 550.
Capture the massive segment of the market that your competitors are currently ignoring. Data shows that 60% of our approved customers were previously declined by prime-only lenders. By serving these “credit-challenged” but motivated buyers, you tap into a latent revenue stream that can transform your annual performance. This is especially critical considering that 27% of households now use these types of programs to finance entire projects rather than just small individual items. Multi-lender platforms outperform single-bank store cards because they offer a wider net, allowing you to serve the “No Credit Needed” market without increasing your own business risk.
Growth-Focused Support and Tools
Build trust through radical transparency. We provide you with an integrated APR calculator to ensure your customers understand their terms before they commit. Clarity is a powerful sales tool; approximately 95% of consumers rate clear, easy-to-understand terms as an essential factor in their final purchase decision. By removing the mystery from the financing process, you position your brand as a supportive and client-centric partner. This approach doesn’t just close a single deal; it builds the foundation for a lifetime of customer loyalty. Are you ready to expand your possibilities and reach your idealized future? Contact ZipLoan to start your merchant enrollment today and unlock the full potential of your business.
Accelerate Your Business Growth Today
Stop letting rigid lending criteria dictate your success. Implementing a private label credit card for small business turns your point of sale into a high-performance engine for sales recovery and long-term loyalty. You now possess the strategic tools to convert 60% of previously declined shoppers into loyal, high-ticket buyers. Why settle for lost opportunities when you can empower your customers to invest in their goals today?
Experience the immediate confidence that comes with an overnight 15% increase in average ticket size. This multi-lender platform removes the financial friction that often stalls growth, while the security of 24-hour funding keeps your operations fluid. You’re no longer just a vendor; you’re an essential facilitator of progress for your clients.
Your business is ready for its next significant breakthrough. Seize this opportunity to redefine your trajectory and secure the tangible results you’ve worked so hard to achieve. We’re here to help you bridge the gap between your current state and your idealized future.
Frequently Asked Questions
Can a small business have its own private label credit card?
Yes, small businesses can launch these programs using modular “Financing in a Box” platforms. Historically, these were reserved for big-box retailers, but modern multi-lender networks have democratized access. You can now provide a branded revolving line that builds purchasing power exclusively with your brand. This allows you to offer a private label credit card for small business without the need for a massive internal bank or complex infrastructure.
What is the difference between a private label and a co-branded card?
Private label cards are closed-loop systems that only work at your specific business. Co-branded cards carry a logo like Visa or Mastercard and can be used anywhere. The primary advantage of a private label card is that it ensures capital stays within your ecosystem. It prevents capital leakage to competitors. By focusing the customer’s spending power on your products, you create a more powerful loyalty engine than a generic card provides.
Do I need to check my customer’s credit score to offer financing?
You don’t need to perform manual credit checks because the platform handles everything through a soft-pull pre-qualification. This process identifies eligible buyers instantly without impacting their credit scores. It reduces customer anxiety and allows your team to focus on the sale rather than the paperwork. By using this automated system, you provide a seamless checkout experience while the multi-lender network makes the final decision on approval.
How does a private label credit card increase my sales?
These programs increase sales by removing the immediate financial barriers that cause customers to hesitate. A private label credit card for small business is proven to increase average ticket sizes by 15% overnight. When customers have a dedicated revolving line, they feel more confident expanding their project scope or choosing premium upgrades. It also helps you recover up to 45% of lost sales from shoppers who lack immediate cash on hand.
Is there any financial risk to my business if a customer doesn’t pay?
There is zero financial risk to your business because the lender network absorbs 100% of the default risk. Once a transaction is approved and funded, you’re protected from any future non-payment by the consumer. This allows you to scale your financing options aggressively without worrying about debt collection or credit losses. You focus on delivering your services while the financial partners manage the underlying credit risks.
How quickly does my business get paid after a customer uses their credit line?
Your business receives full payment within 24 hours of a transaction. This rapid funding cycle ensures that your cash flow remains fluid and predictable, allowing you to pay for materials or labor without delay. Unlike traditional billing cycles that can take 30 days or more, this system prioritizes your operational needs. You get the capital you need to move on to the next project or order immediately.
What credit scores are typically required for approval?
Approvals are available for a wide range of credit tiers, including scores as low as 550. Because we utilize a 30-lender network, we can achieve an approval rate higher than 85%. This is significantly better than single-bank store cards that only target prime borrowers. We specialize in serving the 60% of customers who were previously declined by prime lenders, ensuring that credit-challenged but motivated buyers can still invest in your services.