
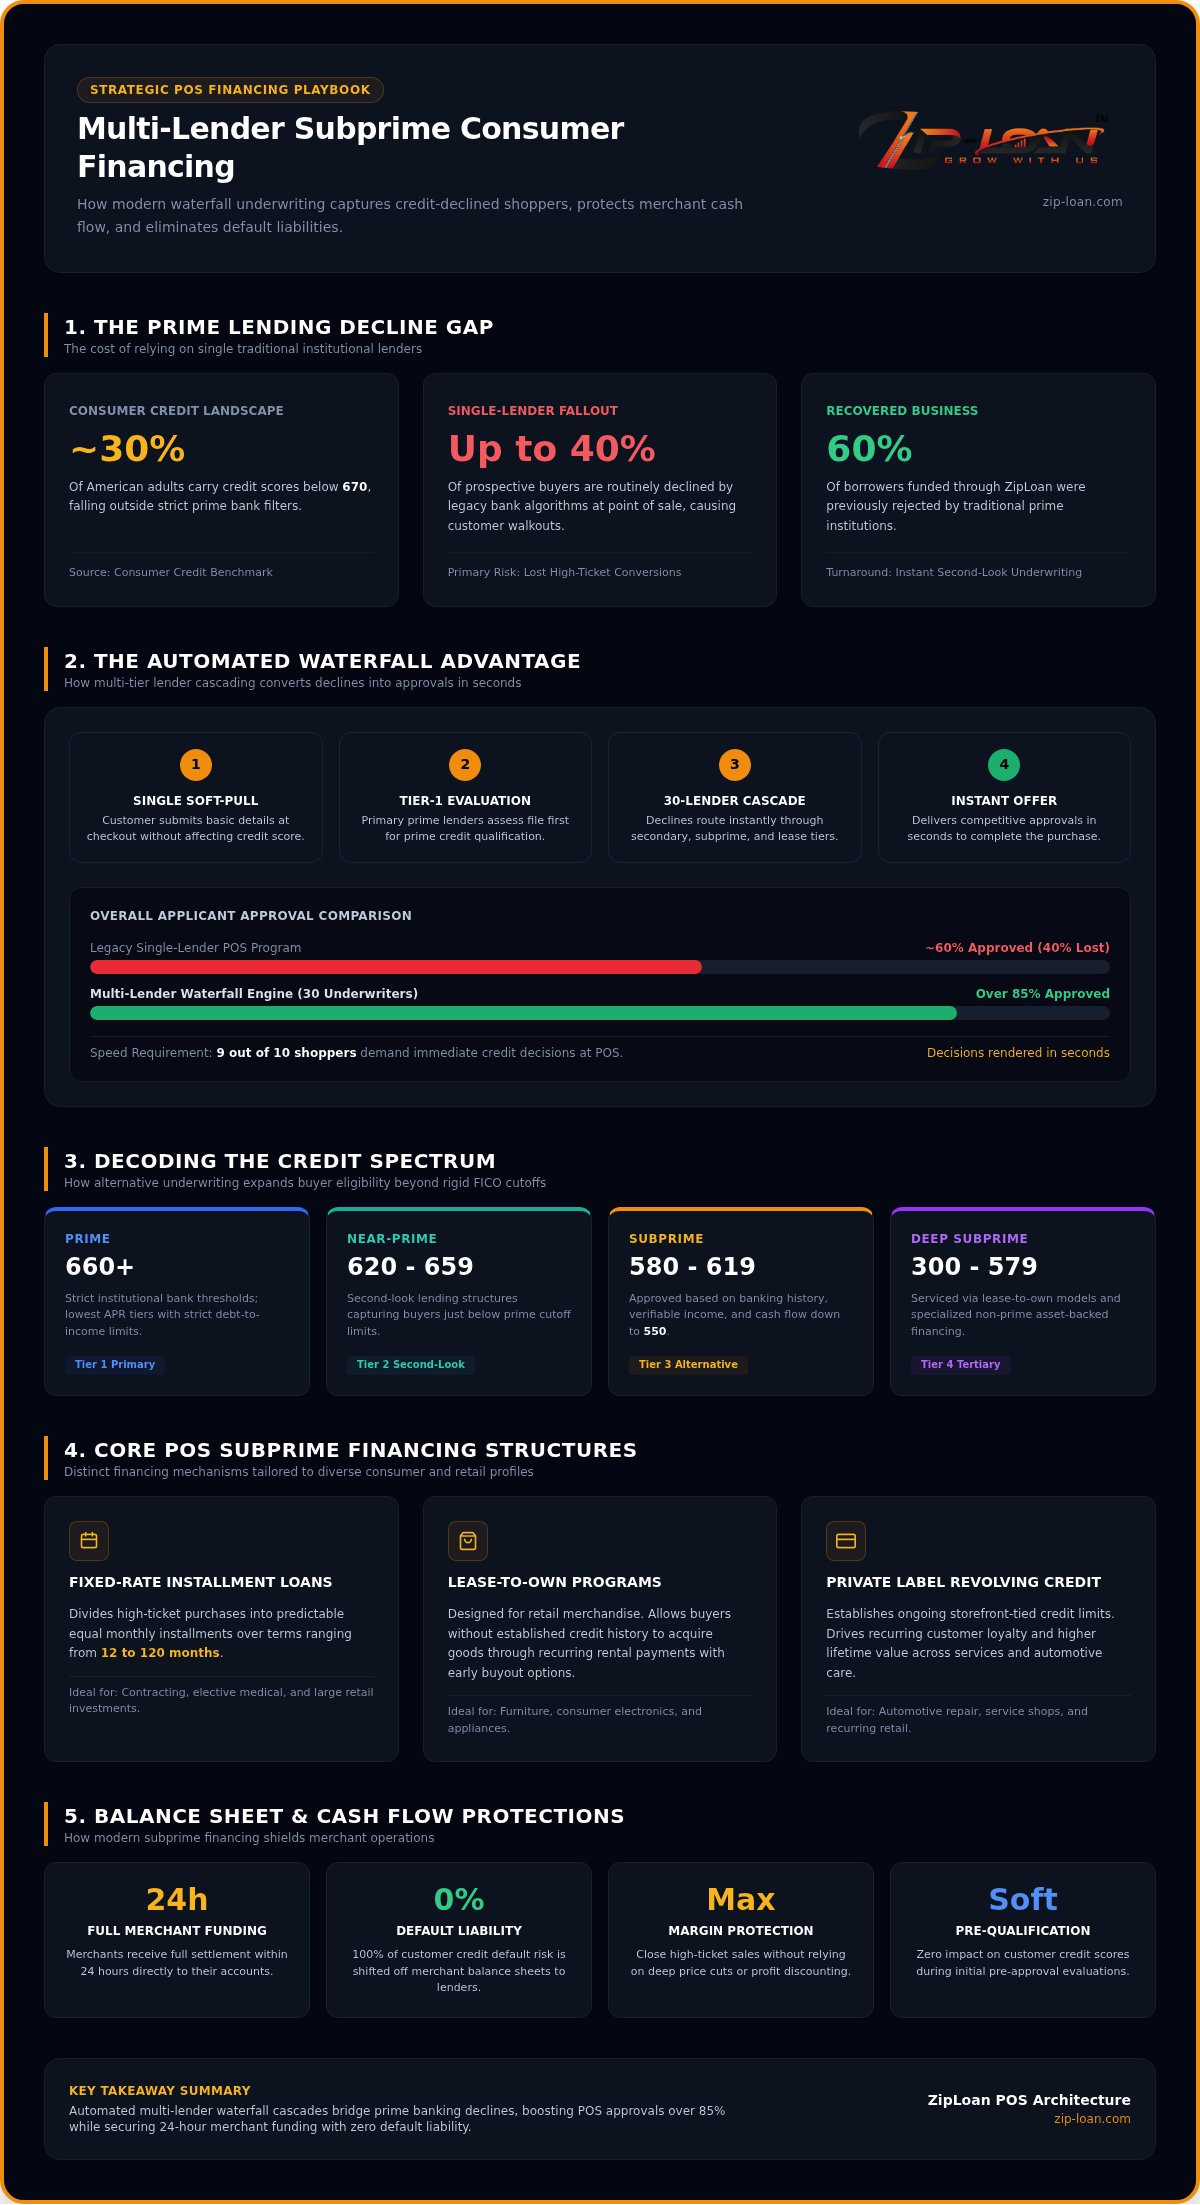
Nearly 30% of American adults carry credit scores below 670, which means traditional prime lenders routinely decline up to 40% of your prospective buyers. Watching motivated shoppers walk away simply because of rigid bank algorithms is frustrating. You want to close every deal, but you can’t afford balance-sheet default liabilities, steep merchant fees, or embarrassing checkout delays. Adopting strategic subprime consumer financing for merchants changes this dynamic entirely, transforming credit-declined shoppers into profitable, closed business.
Discover how multi-lender subprime consumer financing unlocks hidden revenue, captures credit-declined shoppers, and protects merchant cash flow. By routing a single soft-pull pre-qualification through an automated waterfall network, your business can safely approve over 85% of applicants across diverse credit profiles. Better yet, you receive full funding within 24 hours while shifting all customer default risk off your ledger. This 2026 playbook reveals how to elevate your point of sale, expand average order value, and scale top-line growth without discounting your margins.
Key Takeaways
- Bridge prime lender decline gaps by adopting second-look and tertiary financing solutions that turn walkouts into closed revenue.
- Implement subprime consumer financing for merchants through automated waterfall networks to effortlessly capture high-intent buyers rejected by legacy banks.
- Protect your cash flow and balance sheet by transferring all customer default risk to underwriting partners while securing full merchant funding within 24 hours.
- Elevate average order values and close high-ticket service contracts without sacrificing profit margins to price discounting.
- Deploy soft-pull pre-qualification tools at checkout to give customers immediate purchasing clarity without impacting their credit scores.
What Is Subprime Consumer Financing for Merchants and How Does It Work?
Decoding the Credit Spectrum: Prime vs. Near-Prime vs. Subprime
Traditional banks segment applicants into narrow risk bands. While prime borrowers maintain scores of 660 and above, near-prime applicants register between 620 and 659, and subprime buyers land between 580 and 619. Deep subprime extends below 580 down to 300. In foundational subprime lending structures, traditional institutions deploy rigid debt-to-income cutoffs that automatically disqualify credit-building consumers. Modern alternative underwriters bypass these restrictive filters by assessing cash flow consistency, banking history, and verifiable income, allowing merchants to confidently approve buyers who possess steady purchasing power despite credit scores as low as 550.
Core Subprime Financing Structures for Modern Point-of-Sale
Modern point-of-sale platforms deploy distinct financing mechanisms to accommodate diverse consumer profiles while shielding merchant cash flow:
- Fixed-Rate Installment Loans: These structures divide large purchases into transparent, equal monthly payments over fixed terms ranging from 12 to 120 months. Shoppers gain immediate predictability, making mid-to-high ticket investments manageable.
- Lease-to-Own Programs: Tailored for merchandise and retail goods, lease-to-own models allow consumers without strong credit histories to acquire essential products through recurring rental payments with early buyout incentives.
- Private Label Revolving Credit: Revolving lines establish ongoing credit limits directly tied to your storefront. This structure encourages repeat store visits and creates long-term customer loyalty across contracting, automotive, and elective care services.
Implementing targeted subprime consumer financing for merchants equips your business with multiple financial safety nets. To explore how non-prime financing models expand buyer reach across diverse commercial sectors, review the specialized solutions detailed across industries we serve.
The Waterfall Advantage: Why Single-Lender Financing Fails Merchants
Relying on a single primary bank creates an artificial ceiling on your business growth. When that lone lender issues a decline, up to 40% of your prospective applicant traffic walks out the door empty-handed. This legacy structure forces staff into awkward conversations and leaves high-margin sales on the table. Modern subprime consumer financing for merchants replaces this single point of failure with automated multi-lender waterfall cascades. By connecting a single application to 30 diverse lenders simultaneously, waterfall technology drives total approval rates above 85%, ensuring specialty retailers, contractors, and service providers never discard viable revenue.
How Multi-Lender Waterfall Cascades Route Applications in Seconds
The waterfall sequence triggers the moment a customer submits basic transaction details. The platform evaluates tier-one prime criteria first. If the applicant falls short of stringent bank thresholds, the engine cascades the file instantly down through near-prime, subprime, and lease-to-own tiers without requiring manual re-entry. Verified CFPB consumer credit research confirms that non-prime consumers generate a substantial share of total point-of-sale financing demand. Speed remains vital to closing these deals. Nine out of ten shoppers demand immediate credit decisions at checkout, and waterfall cascades deliver multiple competitive lender offers in just seconds.
Protecting Shopper Credit via Soft-Pull Pre-Qualification
Checkout friction often stems from shopper anxiety around hard credit checks. Legacy paper applications with mandatory hard inquiries cause immediate cart abandonment. Modern platforms remove this barrier by routing initial pre-qualifications through soft credit pulls that carry zero impact on customer credit scores. Shoppers can scan an in-store QR code, tap an SMS invite, or pre-qualify online directly from their personal mobile device. Clear approval terms display instantly, removing embarrassment and building trust at the point of sale. Business owners ready to eliminate customer drop-offs can explore how flexible customer financing solutions systematically turn declined traffic into profitable transactions.
Business Benefits: How Subprime Financing Drives Revenue and Cash Flow
Expanding your credit reach directly elevates your bottom line. Integrating subprime consumer financing for merchants drives an average 15% increase in order values across diverse industries. The impact on service trades is even more pronounced, with home improvement contractors securing 21% more closed deals simply by presenting structured installment options during project estimates. Customer behavior explains this surge: 30% of consumers explicitly confirm they would abandon major purchases without monthly payment plans. Presenting accessible financing directly at checkout recovers up to 45% of transactions that would otherwise be lost to prime credit roadblocks.
Eliminating Default Risk with Non-Recourse Merchant Settlement
Operational stability depends on maintaining predictable working capital. Some merchants mistakenly believe that accommodating non-prime buyers requires taking on personal balance-sheet liability or chasing unpaid invoices. Modern multi-lender networks remove this risk completely. Underwriting partners assume 100% of customer default risk under non-recourse funding agreements, protecting your business from missed payments or collection headaches. You receive full funding in your business account within 24 hours of project completion or customer checkout, preserving liquidity while shifting non-payment liability away from your books.
Closing High-Ticket Sales Without Margin-Killing Discounts
Price resistance vanishes when total cost shifts into predictable monthly payments. Instead of slashing prices by 10% or 20% to win price-sensitive shoppers, merchants present affordable terms that maintain full retail margins. As detailed in the Federal Reserve point-of-sale credit overview, consumers increasingly prefer extended-term installment credit to handle significant outlays without depleting household liquidity. Point-of-sale networks accommodate transactions spanning from $1,000 up to $100,000, with instant approvals reaching up to $65,000. For qualified buyers, promotional 0% interest programs lasting 6, 12, 18, or 24 months provide compelling purchase incentives without eroding profitability.
Strategic subprime consumer financing for merchants transforms customer affordability into a decisive competitive advantage. To discover how structured financing tools maximize cash flow and operational scale across retail and service models, explore our comprehensive guidance on consumer financing services.
Industry Applications: Where Non-Prime Financing Delivers Maximum ROI
High-ticket investments, emergency repairs, and elective procedures represent the largest revenue opportunities for growing businesses. When consumers face sudden expenditures, traditional savings accounts and revolving credit cards are often insufficient. Providing dedicated subprime consumer financing for merchants allows companies to serve households navigating urgent repairs or planned lifestyle upgrades without delay. With lending networks supporting terms extending up to 20 years for major capital improvements, businesses can structure affordable monthly commitments that align directly with household budgets nationwide.
Home Improvement, HVAC, Roofing, and Emergency Contracting
Home systems fail without warning, creating immediate stress for property owners. Verified industry benchmarks show that 27% of households finance major home improvement projects rather than paying out of pocket. When an air conditioning unit fails in midsummer or a roof begins leaking, sticker shock can freeze homeowners into inaction. Offering extended repayment terms spanning 12 to 120 months eases immediate budgetary tension, enabling trade contractors to close high-value bids on the spot.
Automotive Repair Shops and Aftermarket Upgrades
Automotive repair shops face unique checkout challenges when unexpected mechanical issues arise. With the average financed auto-repair ticket reaching $1,500, customers frequently discover that their existing credit cards are maxed out or lack sufficient limits. Flexible point-of-sale financing steps in immediately to bridge the difference. By providing accessible terms at the counter, service centers keep bays turning over, eliminate stalled jobs, and get drivers back on the road quickly.
Elective Healthcare, Dental, and Medical Procedures
Elective medical procedures, cosmetic dentistry, and advanced wellness therapies frequently fall outside standard health insurance coverage. Subprime consumer financing for merchants removes financial hurdles that cause patients to postpone essential treatment plans. Modern medical financing structures eliminate hidden costs, carrying no prepayment penalties or retroactive interest traps. Practices benefit from reliable daily settlement schedules, allowing clinical staff to prioritize patient outcomes while maintaining steady cash flow.
Business owners across retail, trade services, and clinical care can discover how tailored programs adapt to their specific business model by reviewing the diverse industries we serve.
Schedule a consultation to activate multi-lender financing for your business
Evaluating and Implementing a Subprime Financing Program in 2026
Executing an effective rollout requires a structured, step-by-step approach. Begin by auditing your historical checkout declines to quantify lost top-line revenue. Next, replace restrictive single-lender tools with an agile multi-lender waterfall cascade. Compare fee arrangements and settlement speeds to ensure your operational margins stay intact. Finally, equip your team with straightforward customer talk tracks and physical collateral. Reviewing diverse retail financing options ensures your program aligns with customer expectations while establishing subprime consumer financing for merchants as an active growth channel.
Essential Criteria for Selecting a Merchant Financing Partner
Selecting the right lending partner dictates your ultimate approval success. First, verify that the platform’s underwriting footprint accommodates credit-building customers down to a 550 score. Second, demand rapid settlement schedules that transfer full, non-recourse merchant funding within 24 hours of completed sales. Finally, prioritize transparent agreements and zero dealer fee structures that protect profitability on non-prime customer financing, avoiding predatory rate traps that erode gross margins.
Staff Onboarding and In-Store Point-of-Sale Enablement
Empowering your team turns financing into an everyday sales asset. Train sales professionals and front-line technicians to introduce financing early in the consultation as a standard monthly budgeting tool rather than a last-ditch credit fallback. Deploy free Touch-n-Buy POS marketing assets, including register displays, window decals, and QR code signage, directly within consumer sightlines. Comprehensive digital dashboards allow your administration to monitor application volume, track approval statuses, and verify automated disbursements in real time.
Accelerate Business Growth with the Zip-Loan Financing Platform
Zip-Loan provides a modern, turnkey solution that streamlines subprime consumer financing for merchants across contracting, automotive, retail, and healthcare. A single integrated portal connects your buyers to 30 competitive lenders, generating decisions in seconds and unlocking approvals up to $65,000. Your business gets paid quickly with zero balance-sheet liability, ensuring credit declines never limit your commercial potential again. Take the next step to optimize your conversion rates and learn why financing powers growth today.
Scale Your Revenue and Eliminate Credit Barriers in 2026
Leaving qualified customers behind is no longer an acceptable cost of doing business. Restrictive legacy banks discard high-intent shoppers every day, but modern subprime consumer financing for merchants transforms that friction into immediate, predictable revenue. By integrating a dynamic multi-lender network featuring 30 top lending partners, your counter effortlessly achieves over 85% approval rates across diverse credit profiles. Applicants access instant approvals up to $65,000 with repayment terms extending up to 20 years. Meanwhile, your enterprise enjoys 100% risk-free financing supported by reliable 24-hour merchant settlement.
Step boldly into the future of point-of-sale commerce. When you remove financing hurdles, you preserve hard-earned margins, elevate average order values, and ensure every motivated buyer finds an affordable path to say yes. Your business is ready for sustained growth, and modern financing provides the key to unlocking it.
Frequently Asked Questions
What credit score is considered subprime for point-of-sale customer financing?
Is my business financially liable if a subprime customer defaults on their loan?
No, your enterprise carries zero financial liability if a buyer fails to make scheduled payments. Under non-recourse merchant agreements, the third-party underwriting network assumes 100% of consumer default risk. Your business gets paid in full upfront, which means your ledger remains completely isolated from customer defaults, late fees, or collections management.
How fast does my business receive payment after a customer financing approval?
Your business receives direct merchant funding within 24 hours of transaction completion. Trade contractors receive full settlement immediately upon customer sign-off, while retail and medical providers benefit from predictable daily funding distributions. This rapid turnaround protects working capital and supports healthy operational cash flow without delaying project delivery.
Can customers with credit scores as low as 550 get approved through ZipLoan?
Yes, applicants with credit scores as low as 550 regularly qualify for approvals through our platform. By connecting shoppers to specialized lenders that assess cash flow consistency and verifiable income rather than relying solely on legacy bureau scores, the network secures approvals across diverse credit profiles. In fact, 60% of approved borrowers were previously rejected by conventional prime banks.
Does applying for subprime consumer financing damage the customer’s credit score?
Initial pre-qualification produces zero negative impact on consumer credit scores. Customers evaluate their purchasing power using a soft credit inquiry accessed via text message, QR code, or online checkout link. The system only triggers a formal hard inquiry after the buyer reviews their tailored repayment options and formally accepts an underwriting offer.
How does a multi-lender waterfall platform differ from a standard bank program?
A single-bank model relies on one rigid underwriting standard, resulting in immediate transaction declines for up to 40% of applicants. In contrast, an automated waterfall platform routes a single submission across 30 distinct lending institutions. Modern subprime consumer financing for merchants uses this cascading engine to find the exact prime, near-prime, or lease-to-own match, lifting total approvals above 85%.
What ticket sizes and repayment loan terms can merchants offer their customers?
Merchants can finance ticket sizes ranging from under $1,000 up to $100,000, with instant platform approvals reaching up to $65,000. Available repayment structures span 12 to 120 months for standard purchases and up to 20 years for major capital home improvement contracts. Qualified consumers can also leverage promotional 0% interest programs spanning 6, 12, 18, or 24 months.
How difficult is it to integrate subprime financing into an existing checkout process?
Integrating subprime consumer financing for merchants is straightforward and requires zero complex software engineering or IT modifications. Point-of-sale staff can send digital pre-qualification links via SMS, place scannable Touch-n-Buy counter displays, or direct shoppers to an online application link. Your team tracks live application statuses and automated funding disbursements through an intuitive, cloud-based merchant dashboard.