
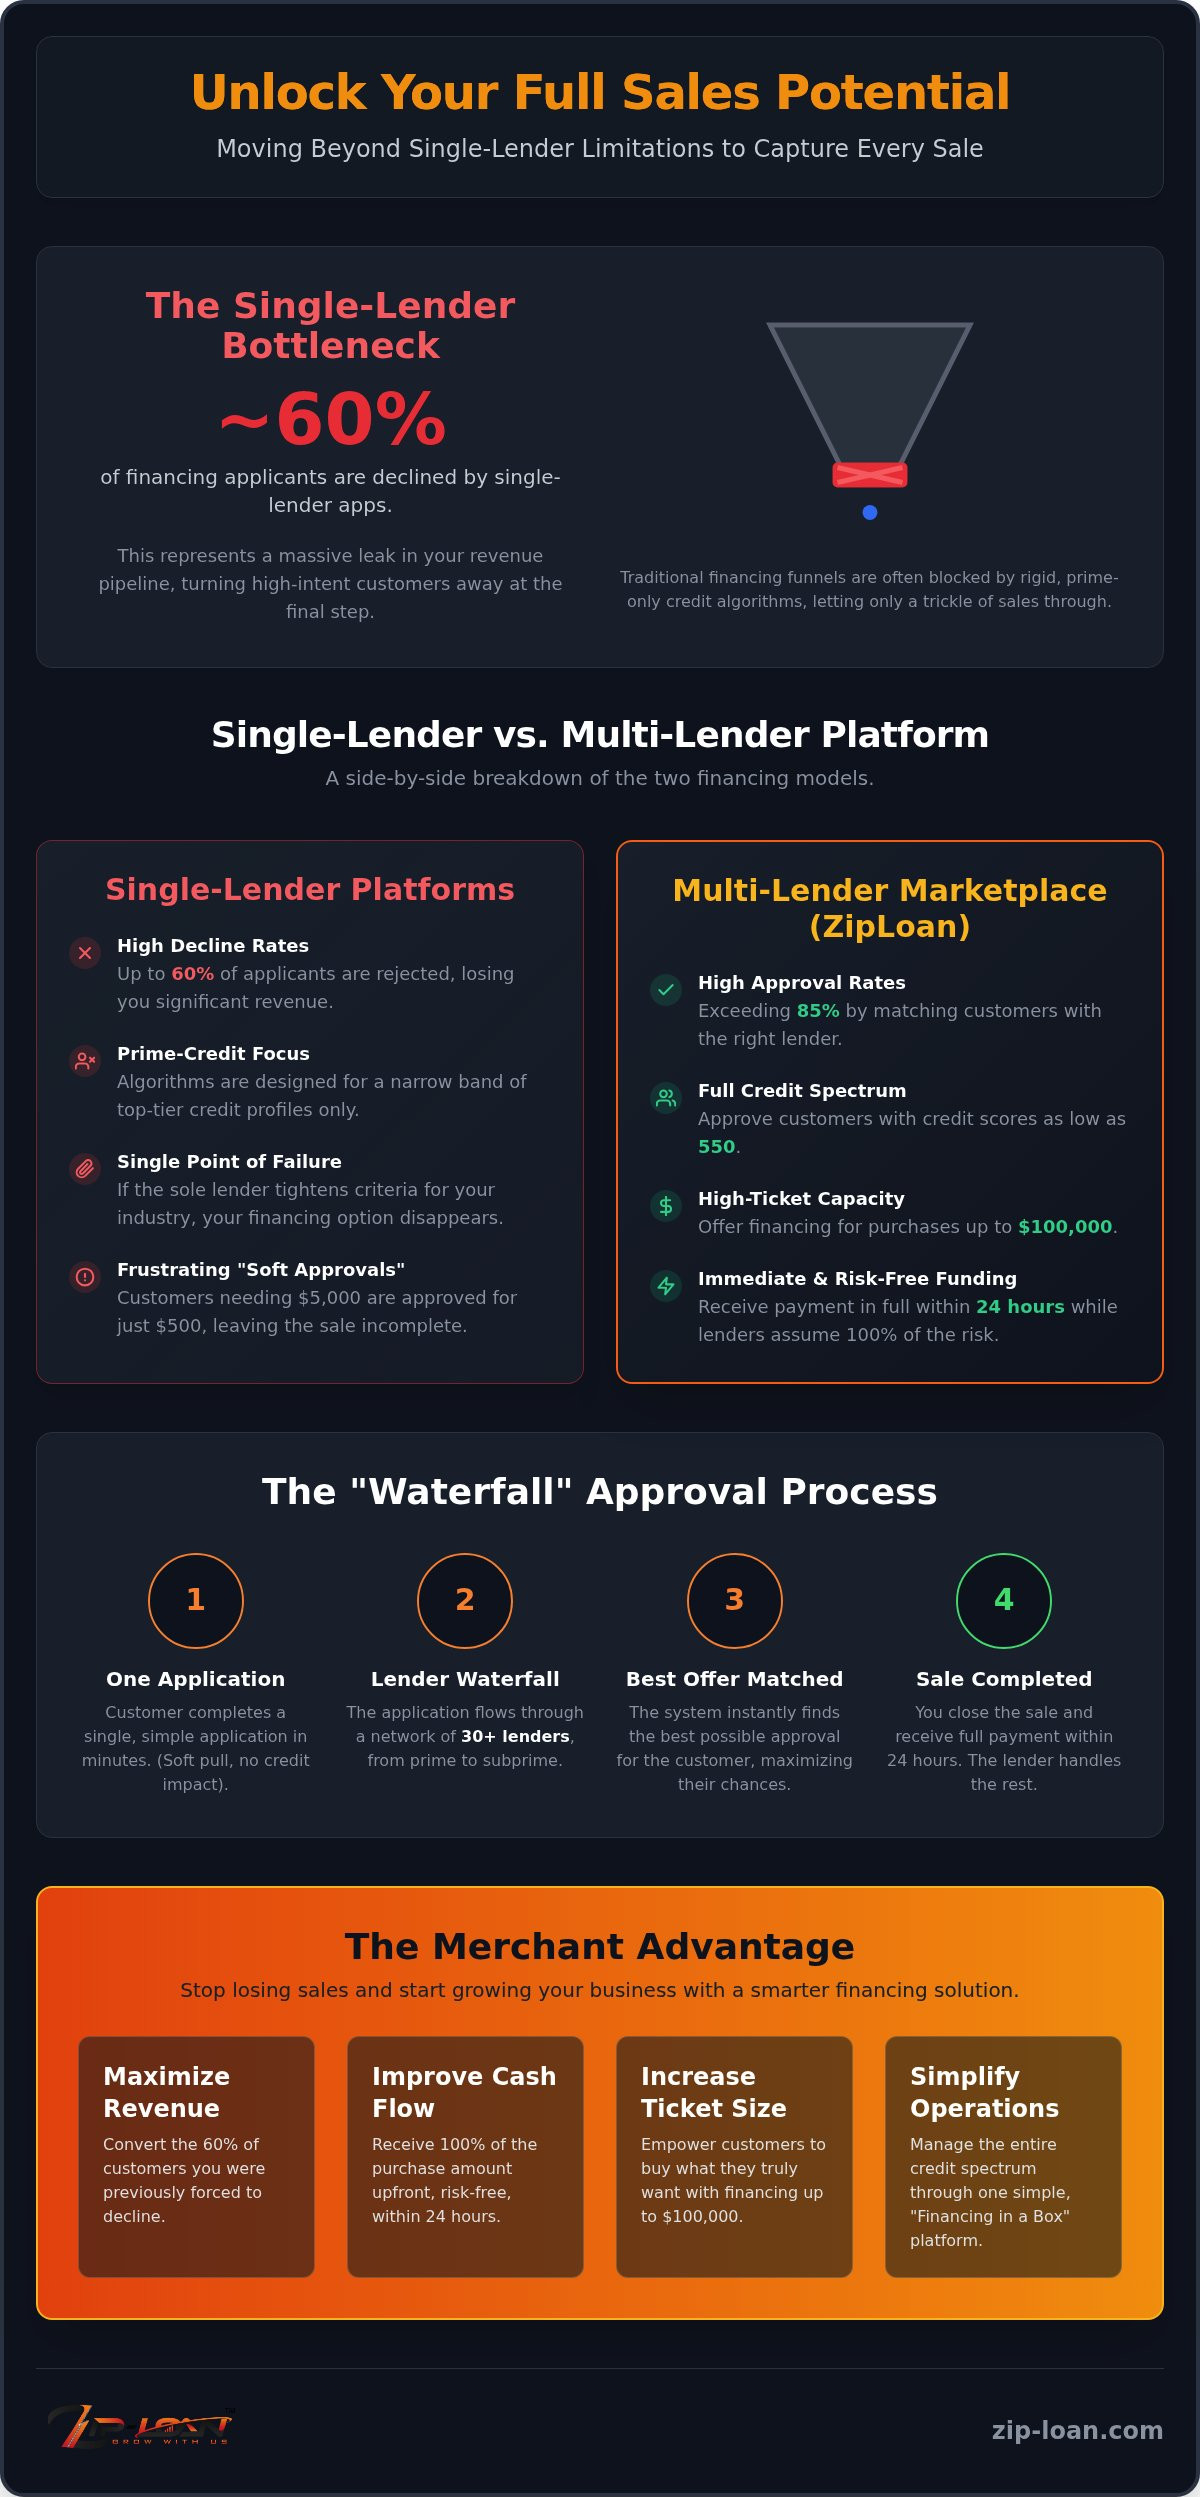
Did you know that roughly 60% of shoppers who seek financing through single-lender apps are declined? For a growing business, that isn’t just a statistic; it represents a massive amount of latent potential left on the table. It’s frustrating to watch high-intent customers abandon their carts simply because a rigid credit algorithm failed to see their value. You’ve built a brand designed for expansion, yet traditional bottlenecks continue to stifle your momentum and hurt your daily cash flow.
This guide explores the most effective Klarna alternatives for merchants looking to move beyond prime-only limitations and optimize their checkout experience. We’ll show you how a multi-lender financing engine like Zip-Loan can unlock near-total customer approval and expand your sales capacity up to $100,000. You’re about to discover how to capture every possible sale, secure immediate funding, and finally align your payment options with your highest aspirations for 2026. We’ll break down the transition from restrictive single-lender models to a versatile platform that welcomes customers across the entire credit spectrum, ensuring that no qualified buyer is turned away at the point of sale.
Key Takeaways
- Break free from the prime-only decline cycle that leaves up to 60% of your potential revenue behind.
- Explore advanced Klarna alternatives for merchants that utilize a multi-lender “waterfall” engine to reach approval rates exceeding 85%.
- Scale your sales capacity by offering flexible financing for high-ticket purchases reaching up to $100,000.
- Optimize your cash flow with immediate funding cycles that deposit payments in full within 24 hours.
- Deploy a “Financing in a Box” solution in minutes to provide tailored installment credit and lease-to-own programs for any industry.
Why Merchants are Seeking Klarna Alternatives in 2026
Stop settling for “no” at the finish line. Relying on a single-lender platform often means turning away half of your potential customers. Many businesses find that Klarna declines 50% or more of applicants because their risk appetite is strictly limited to prime credit profiles. To stay competitive, many businesses are evaluating Klarna alternatives for merchants that can handle a broader range of credit profiles. This prime-only barrier creates a massive revenue leak. When a customer is ready to buy but receives a rejection, it doesn’t just lose you a sale. It damages brand trust and demotivates your sales team. They eventually stop offering financing altogether because they expect a decline, creating a cycle of missed opportunities.
The evolution of Buy Now, Pay Later (BNPL) has shifted consumer behavior permanently. Shoppers no longer view these options as a retail luxury; they see them as a standard requirement for professional services and high-ticket items. Merchants are also facing the frustration of “soft approvals.” This occurs when a customer needs $5,000 for a project but is only approved for $500. This gap leaves the merchant and the buyer in limbo, unable to complete the transaction despite a partial approval. High decline rates and low limits are no longer acceptable in an era where growth depends on accessibility.
The Problem with Single-Lender Limitations
A single credit algorithm acts as a bottleneck for your growth. If that one lender feels cautious about a specific industry or credit tier, your sales stop instantly. This is why savvy business owners are searching for Klarna alternatives for merchants that offer more than a one-size-fits-all approach. You need a system that looks beyond the surface. By accessing a wider network, you can approve customers with credit scores as low as 550. This flexibility turns a rejection into a milestone for your business and ensures you aren’t capped by someone else’s rigid risk appetite.
Consumer Demand for Instant POS Approval
Speed is the new currency in the modern marketplace. In 2026, 9 in 10 consumers expect immediate approval at the point of sale. They aren’t looking for vague credit limits or complex hoops; they want clear, fixed terms that provide confidence for major investments. High-ticket buyers rarely have $10,000 of open room on a single credit card, making simple card-based solutions insufficient for industries like home improvement or healthcare. Understanding why financing is essential for modern business becomes easy when you see it as a bridge. Professional installment credit connects a customer’s immediate needs with your premium services, removing the financial barriers to expansion.
Single-Lender vs. Multi-Lender Platforms: Which Wins?
Imagine your business as a high-performance engine restricted by a single fuel line. That’s the reality of using a single-lender platform. When evaluating Klarna alternatives for merchants, the most significant shift you can make is moving from a single balance sheet to a multi-lender marketplace. This approach connects your checkout portal to 30+ lenders simultaneously. The Zip-Loan platform triggers a competitive environment where multiple institutions vie for your customer’s business, ensuring you aren’t at the mercy of one lender’s changing risk appetite.
This is the “waterfall” approval process. One application flows through a hierarchy of lenders, starting with prime institutions and moving through subprime and lease-to-own options. This diversity is the only way to achieve near-total approval rates. According to research from the Federal Reserve Bank of Boston, BNPL users come from varied financial backgrounds, meaning a single-lender’s rigid criteria will inevitably exclude qualified buyers who don’t fit a narrow profile. Achieving true 100% approval programs requires this diverse network of prime and subprime lenders working in tandem.
The Mechanism of a Financing Marketplace
Think of this as “Financing in a Box.” You manage the entire credit spectrum through one portal without the administrative headache. The system performs a soft-pull pre-qualification, which protects the customer’s credit score while determining their maximum limit. Speed is essential here. The platform processes checks across 30+ lenders in under 60 seconds, delivering a decision before the customer has a chance to second-guess their purchase.
Merchant Benefits: Risk-Free Growth
Eliminate the fear of non-payment. In this model, the lenders assume 100% of the risk. You receive payment in full, typically within 24 hours of the transaction, ensuring your cash flow remains fluid and predictable. Professional high-ticket merchants benefit from a standardized 2.99% discount fee, making it a cost-effective way to adopt Klarna alternatives for merchants that prioritize scalability. If you’re ready to remove the barriers to your next breakthrough, consider how implementing a multi-lender portal can transform your revenue overnight.
Top Klarna Alternatives for High-Ticket Merchants
High-ticket merchants face a unique challenge that small-ticket retail apps aren’t equipped to handle. When you’re selling a $15,000 HVAC system or a $50,000 remodeling project, you need Klarna alternatives for merchants that offer more than just a “pay in 4” option. Zip-Loan fills this gap by specializing in large-ticket transactions that prime-only lenders typically avoid. As the Consumer Financial Protection Bureau (CFPB) indicates, clear communication regarding loan terms is essential for consumer confidence, especially when the financial stakes are high.
Many businesses have attempted to use card-based installment plans, but these often fail because they rely on the customer’s existing credit limit. If a buyer doesn’t have $20,000 of available room on their current card, the transaction dies at the point of sale. This is why a dedicated multi-lender engine is superior; it creates new credit capacity rather than tapping into what’s already there. By capturing the 60% of shoppers typically declined by prime-only apps, you ensure your business isn’t leaving massive revenue on the table due to outdated lending models.
Zip-Loan: Scaling from $1,000 to $100,000
Growth requires a partner that can scale alongside your most ambitious projects. Zip-Loan offers the flexibility of repayment terms ranging from 12 months all the way up to 20 years. This longevity makes even the largest investments feel manageable for the average household. You can provide instant approval for tickets up to $65,000, ensuring your sales process remains fast and efficient. For a deeper look at how these tools apply to your specific field, review our guide on consumer financing services for diverse industries.
Comparing Approval Tiers and Credit Access
Accessibility is the ultimate differentiator in a crowded market. While many Klarna alternatives for merchants focus exclusively on the top tier of credit, Zip-Loan empowers you to serve the “credit-challenged” segment with scores as low as 550. This inclusivity expands your reach significantly and builds long-term loyalty. To seal the deal, you can offer 0% promotional APR for 6 to 24 months, providing an irresistible incentive for hesitant buyers. Learn more about these strategies in The Ultimate Merchant’s Guide to Retail Financing Options in 2026. By prioritizing broad credit access, you position your business as a facilitator of solutions rather than a gatekeeper.
Choosing an Alternative Based on Your Industry
Select a solution that matches the scale of your transactions. If your business handles $50,000 roofs or intricate HVAC installations, a basic retail app designed for clothing simply won’t suffice. Finding effective Klarna alternatives for merchants means identifying platforms that can bridge the gap between high costs and customer affordability. Auto repair shops and specialized retail boutiques often see their average ticket sizes climb by 15-30% when they implement professional installment credit. This isn’t just about making a sale; it’s about enabling your customers to invest in quality without the immediate financial strain.
Healthcare and patient services demand a higher level of sensitivity and transparency. Patients want to prioritize their health and wellness without facing the threat of pre-payment penalties. Offering a clear path to care through flexible lease-to-own programs or revolving credit creates a supportive environment. It transforms the provider-patient relationship from a transactional one into a partnership focused on long-term success. To understand how these tools fit your specific business model, explore the industries we serve and see the difference a tailored engine makes.
Contractor Financing: Closing the Budget Gap
Eliminate the financial barriers that cause you to lose approximately 45% of sales to budget constraints. In the contracting world, timing is everything. You need access to immediate funding to cover upfront materials and labor costs, ensuring the project moves forward without delay. By utilizing a multi-lender portal, you can offer terms that make sense for large-scale renovations. Some merchants report a 21% increase in deals closed after switching to a platform that handles the entire credit spectrum. This shift allows you to focus on your craft while the financing engine handles the revenue.
Patient and Professional Services
Provide your clients with the digital tools they need to manage their financial journey with confidence. Secure dashboards allow patients to track their own payment plans, reducing the need for awkward billing conversations. Daily funding cycles keep your practice liquid and operational, while soft-pull pre-qualification significantly lowers “consultation anxiety.” When patients know their approval status within seconds without affecting their credit score, they’re much more likely to move forward with recommended treatments. This proactive approach ensures that care is never delayed by financial uncertainty.
Connect with an expert to scale your industry-specific financing
How to Implement Zip-Loan: The “Financing in a Box” Solution
Deploying a high-performance financing engine shouldn’t be a complex technical hurdle that slows your momentum. Zip-Loan provides a streamlined “Financing in a Box” approach that allows you to activate Klarna alternatives for merchants without the usual administrative friction. The journey from setup to your first funded transaction is designed for speed and simplicity, ensuring your focus remains on growth rather than logistics.
The implementation follows four clear steps to success:
- Step 1: Enrollment. Complete your setup and get your multi-lender portal live in minutes. There’s no need for lengthy IT integrations or complex coding.
- Step 2: Marketing. Leverage physical and digital assets to signal your new capabilities. Zip-Loan provides window clings, QR codes, and brochures to catch the customer’s eye at the point of sale.
- Step 3: Pre-Qualification. Empower your customers to check their limits via a simple text or email link. This soft-pull process allows them to explore their buying power without affecting their credit score.
- Step 4: Closing and Funding. Complete the sale with confidence. Once the customer accepts an offer, you receive your funds in full within 24 hours.
Marketing Your New Financing Capabilities
Visibility is the primary driver of conversion in high-ticket industries. Research indicates that 4 in 10 shoppers would utilize financing if they knew it was an option from the very beginning of their journey. By placing QR codes strategically at your checkout or in consultation rooms, you allow customers to discover their eligibility privately and instantly. You can also use the APR calculator as a consultative sales tool. Showing a client how a premium project fits into a manageable monthly budget shifts the focus from the total cost to the immediate value you provide.
Scaling with Real-Time Data
Knowledge serves as the foundation for any successful expansion. Your merchant dashboard provides a real-time view of loan statuses and sales conversion rates, allowing you to see exactly how your financing options are performing. This data is invaluable for refining your approach. You can use these insights to optimize your sales team’s scripts, ensuring they lead with the most effective payment terms for your specific audience. If you’re ready to move beyond the limitations of single-lender apps, you can start your merchant enrollment today and unlock the full potential of your business.
Accelerate Your Growth with Boundary-Free Financing
Transitioning to a multi-lender model isn’t just a technical upgrade; it’s a strategic move that removes the ceiling from your revenue potential. You’ve discovered how moving beyond the bottlenecks of single-lender platforms allows you to capture the 60% of customers that prime-only apps routinely decline. This shift provides the accessibility your customers demand while securing the immediate cash flow your business needs to scale. You’re no longer limited by a single credit algorithm; you’re empowered by a marketplace designed for your success.
When evaluating Klarna alternatives for merchants, the choice becomes clear. You need a catalytic engine that achieves over 85% approval rates by connecting to 30 lenders in one portal. With immediate funding within 24 hours, you can reinvest in your operations and focus on results without worrying about slow cycles or high-ticket rejections. Your business is on the verge of a significant breakthrough, and the right financing partner acts as the bridge to that idealized future.
Empower your business with ZipLoan’s multi-lender financing-enroll now!
Take the next step toward mutual success and watch your possibilities expand. Your growth journey starts with a single, optimized choice.
Frequently Asked Questions
How does Zip-Loan compare to Klarna for merchant fees?
Zip-Loan charges a transparent 2.99% discount fee. This compares favorably with many single-lender apps that often hide higher costs in complex tiers or variable rates. This flat fee allows you to transfer the risk of non-payment to the lender network while securing immediate payment. It’s a predictable model designed to help high-ticket merchants maintain strong margins as they explore Klarna alternatives for merchants.
Can Zip-Loan approve customers with a credit score below 600?
Yes, Zip-Loan can approve customers with credit scores as low as 550. While prime-only lenders often have a rigid cutoff at 660 or higher, our multi-lender engine includes subprime and lease-to-own options. This flexibility is why 60% of our customers were previously declined by traditional prime lenders. We look at the entire credit spectrum to ensure you don’t lose sales to strict algorithms.
How quickly do merchants get paid after a customer is approved?
Merchants receive their funds in full within 24 hours of a transaction. For healthcare providers, we offer daily funding cycles to ensure your practice remains liquid and operational. This rapid funding is a significant advantage over platforms with slower settlement cycles. It allows you to pay for materials, labor, or inventory immediately after closing a deal, keeping your business moving at full speed.
Is there an impact on the customer’s credit score for pre-qualification?
There’s no impact on the customer’s credit score during the pre-qualification stage. We utilize a soft-pull credit check to determine eligibility and buying power instantly. This allows shoppers to explore their financing options with confidence and without the fear of a hard inquiry lowering their score. A hard pull only occurs if the customer decides to move forward and accept a specific loan offer.
What industries are best suited for Zip-Loan’s multi-lender platform?
Zip-Loan is specifically optimized for high-ticket industries like home improvement, auto repair, healthcare, and specialized retail. Our platform handles everything from small retail purchases to major $100,000 projects. Because we offer terms up to 20 years, we’re the ideal choice for contractors and medical professionals who need more than the simple “pay in 4” models found in other Klarna alternatives for merchants.
Does Zip-Loan offer 0% interest promotional periods like Klarna?
Yes, we offer 0% promotional APR options for qualified applicants. These same-as-cash periods typically range from 6 to 24 months, giving your customers the flexibility to pay over time without incurring interest charges. Offering these promotions is a powerful way to increase your average ticket size. It encourages hesitant buyers to invest in higher-quality services by making the monthly payments feel much more manageable.
What is the maximum financing amount available for a single transaction?
You can provide financing for a single transaction up to a total ticket price of $100,000. Our platform offers instant approval capabilities for amounts reaching as high as $65,000. This massive range far exceeds the limits of standard retail BNPL apps. It empowers contractors and professional service providers to fund entire home renovations or complex medical procedures through a single, streamlined digital portal.
How does the “100% approval program” actually work for my business?
This program works by utilizing a “waterfall” of 30+ lenders to find a match for nearly every applicant. When a customer applies, our engine automatically checks prime, subprime, and lease-to-own lenders in seconds. If the first lender declines, the application instantly moves to the next. This competitive marketplace environment is designed to maximize your approval rates and ensure that every high-intent customer has a path to purchase.