
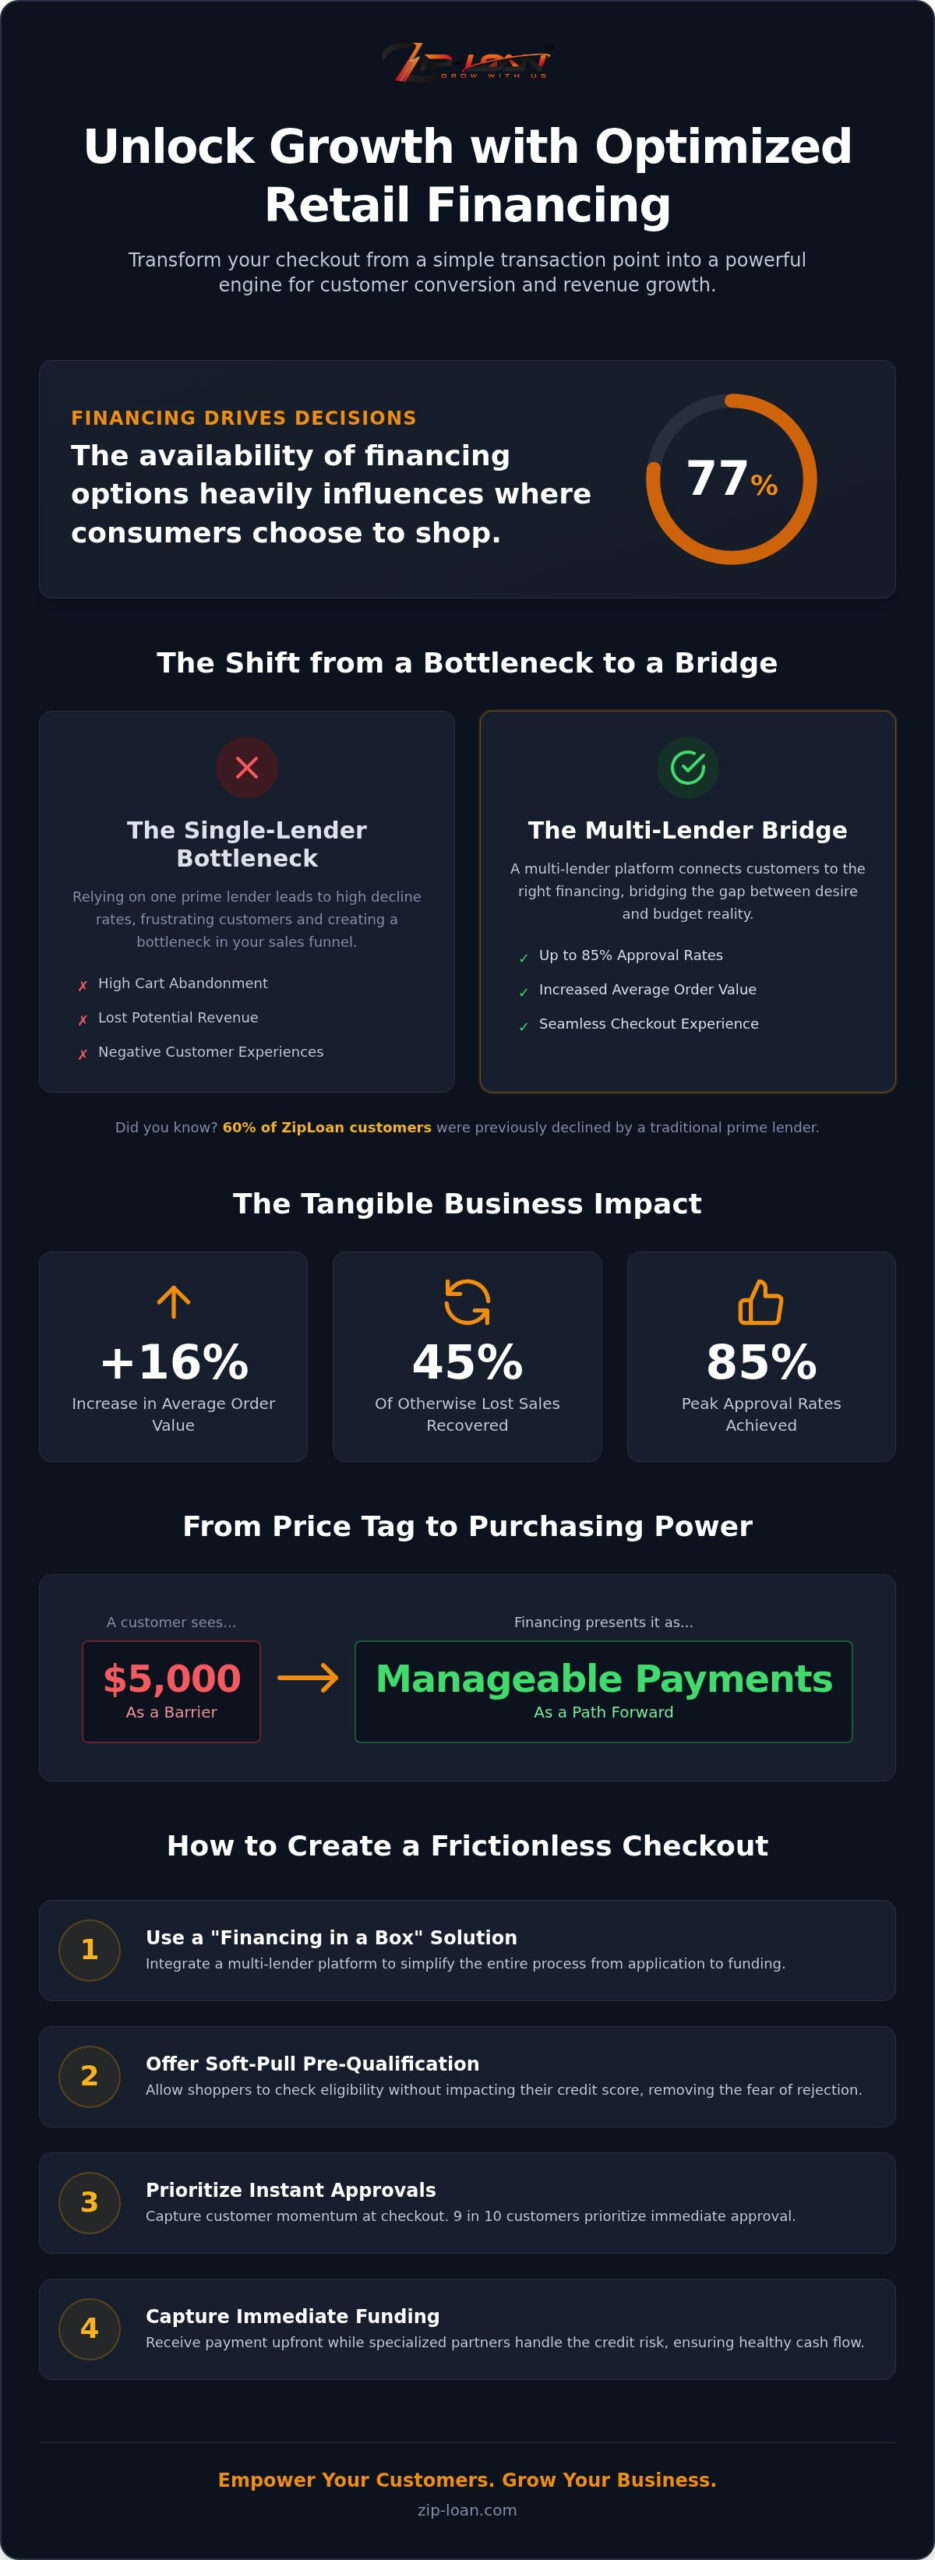
77% of consumers state that the availability of financing options heavily influences where they choose to shop. If your business still relies on a single prime lender, you’re likely watching a massive portion of your potential revenue walk out the door. High cart abandonment and frustrating credit declines shouldn’t be the standard for your brand. By strategically optimizing your retail financing options, you can bridge the gap between customer desire and their current budget reality.
You already understand that a seamless checkout is the heartbeat of your sales cycle. Yet, managing a complex web of lending relationships often feels like a barrier to your growth rather than a tool for expansion. This guide will show you how to transform your checkout experience into a catalytic growth engine that boosts average ticket sizes and secures immediate funding. We’ll explore the critical 2026 regulatory shifts and the rise of multi-lender platforms that empower you to reach approval rates as high as 85% even for customers previously declined by traditional banks.
Key Takeaways
- Transition your mindset from simple payment processing to providing true purchasing power that bridges the gap between customer desire and budget reality.
- Evaluate various retail financing options to select the specific credit structures, such as installment or revolving credit, that align with your industry’s unique sales cycle.
- Implement a “Financing in a Box” solution to create a frictionless checkout experience that minimizes cart abandonment and maximizes customer satisfaction.
- Leverage multi-lender platforms to achieve approval rates of 85%, ensuring that customers previously declined by prime lenders can still complete their purchase.
- Capture immediate funding and increase your average order value by 16% while allowing specialized partners to handle the underlying credit risk.
The Shift from Retail Payment Processing to Purchasing Power
Stop thinking about your checkout as a simple point of transaction. Modern retail payment processing has moved far beyond the swipe and the chip; it’s now about equipping your customers with the ability to say “yes” to the things they truly want. When a customer sees a $5,000 price tag, their brain often registers a barrier. Presenting that same cost as a series of manageable monthly installments changes the psychological calculation entirely. This shift from total price to affordable payments is a core advantage of modern retail financing options. By integrating these solutions, businesses can recover up to 45% of sales that would otherwise be lost to budget constraints. Instead of seeing a barrier, the customer sees a path forward.
Many modern consumers are already familiar with Buy Now, Pay Later (BNPL) services, which have redefined how people manage their cash flow at the point of sale. This model has shifted the focus from the merchant’s ability to process a card to the customer’s ability to expand their purchasing power instantly. It’s a catalytic change that turns a standard vendor-client relationship into a partnership centered on mutual growth.
Why Traditional Credit is Failing Your Customers
Traditional banks and prime lenders are tightening their belts. This means many of your most loyal customers are being turned away at the very moment they’re ready to buy. Did you know that 60% of Zip-Loan customers were previously declined by a traditional prime lender? Relying on a single, rigid lending source creates a bottleneck in your sales funnel. Providing a variety of retail financing options ensures that you don’t penalize customers for not having a perfect credit score. By utilizing soft-pull pre-qualification, you allow shoppers to check their eligibility without impacting their credit rating. This removes the fear of rejection and builds immediate trust during the sales process.
The ROI of Offering Flexible Payment Plans
What happens when you remove the barrier of a high upfront cost? You unlock latent potential in your customer base. Partners using advanced financing platforms report 16% larger project sizes on average. This isn’t just about closing a deal; it’s about closing a better deal. Speed is also a critical factor in this equation. Statistics show that 9 in 10 customers prioritize immediate approval when they’re at the checkout. If the process is slow or cumbersome, the momentum dies. Transforming your payment strategy into a growth engine means providing instant gratification and financial flexibility in one seamless motion. This approach ensures immediate funding for your business, allowing you to maintain healthy cash flow while your customers enjoy their purchases.
Exploring Core Retail Financing Options: Installments, Leases, and Revolving Credit
Selecting the most effective retail financing options involves more than just picking a provider; it requires a strategic alignment between your products and your customers’ financial habits. The Federal Reserve classifies most consumer debt into revolving and nonrevolving credit, and understanding these categories helps you build a more resilient checkout experience. By offering a mix of installments, leases, and revolving lines, you remove the barriers that prevent different types of shoppers from completing their purchase. You aren’t just selling a product; you’re facilitating an investment in their lifestyle or home. Providing this variety ensures that you have a solution for every person who enters your store or visits your site.
Installment Loans for High-Ticket Purchases
Installment loans are the gold standard for high-ticket items like roofing, remodeling, or elective medical procedures. These fixed-rate loans offer a level of predictability that helps customers budget for major life improvements without the stress of variable interest rates. Depending on the project scope, terms can stretch from a quick 12-month plan to comprehensive 20-year repayment options. This flexibility allows you to present a $15,000 project as a manageable monthly figure, making the “dream purchase” feel immediately attainable. Transparency is the key here; when a customer understands their total cost of borrowing upfront, their confidence in the transaction skyrockets. This clarity is essential for closing larger deals where the total price might otherwise cause hesitation.
Lease-to-Own and Revolving Lines
Not every customer fits into the traditional credit box. Lease-to-own programs serve as a vital bridge for consumers with credit scores as low as 550, focusing on the utility of the goods rather than just a historical score. This is particularly effective for furniture, appliances, and electronics where the item itself acts as collateral. Offering a variety of retail financing options like these allows you to capture a broader market share while reducing the risk of a single-lender bottleneck. On the other end of the spectrum, revolving credit lines act as a loyalty catalyst. By providing a dedicated line of credit for your brand, you encourage repeat visits and long-term engagement. This “private label” approach ensures that when the customer needs an upgrade, your store is their first destination. To better understand how to structure these offerings, consult our Small Business Customer Credit Lines: 2026 Guide.
Integrating these diverse structures into your workflow doesn’t have to be complex. If you’re looking to optimize your sales funnel and remove friction, it’s worth taking a moment to evaluate your current lending mix to ensure you aren’t leaving revenue on the table.
Industry-Specific Financing: Tailoring Solutions for Your Business
Empowering Contractors and Home Improvement Pros
High-ticket home projects demand significant upfront capital for materials and labor. Providing flexible consumer financing options allows homeowners to commit to more comprehensive upgrades without draining their savings. Partners using these tailored tools report 16% larger project sizes, turning basic repairs into complete renovations. Immediate funding is the lifeblood of this sector; receiving capital within 24 hours ensures that your crews stay on schedule and your supply lines remain open. This speed eliminates the friction of waiting for checks to clear. Explore the industries we serve with tailored financing to see how these solutions align with your specific trade.
Patient Financing for Healthcare Providers
High deductibles often force patients to delay essential care, creating a “deductible gap” that hurts both the patient’s health and the practice’s revenue. Offering plans with no pre-payment penalties encourages patients to prioritize their wellness while managing their payments on their own terms. This transparency builds long-term trust and significantly reduces the administrative burden of chasing collections. Daily funding is essential for medical practices to maintain consistent operational liquidity and cover immediate overhead costs. By removing the cost barrier, you position your practice as a supportive partner in your patient’s healthcare journey. For a comprehensive look at how to offer payment plans to patients without taking on financial risk, our 2026 resource guide walks through the full implementation process for providers.
Auto-Repair Financing: Managing the Unexpected
Auto-repair shops face a distinct challenge: the emergency. When a vehicle breaks down, the cost of repair is rarely a planned expense, leading to high stress and potential lost work for the customer. Turning these urgent repairs into manageable monthly plans through diverse retail financing options ensures your customers get back on the road safely without financial ruin. This proactive approach turns a crisis into a manageable solution, securing your role as a dependable community partner. When you offer a way to pay for a new transmission over time, you aren’t just fixing a car; you’re restoring a customer’s mobility and peace of mind.
The Merchant’s Guide to Implementing Seamless Customer Financing
Integrating retail financing options shouldn’t feel like an overhaul of your existing operations. It’s about a seamless addition that enhances your current retail payment processing flow without adding administrative weight. The “Financing in a Box” concept allows for rapid enrollment and instant deployment, meaning you can start offering flexible terms to your clientele within hours. By utilizing modern tools like QR codes, text-to-apply, and direct email links, you give customers the privacy to apply on their own mobile devices. This contactless approach removes the social friction often associated with credit applications and allows the shopper to maintain control over their financial decisions.
Your sales team acts as the primary bridge between a customer’s desire and their final purchase. Train your staff to present financing as a proactive solution rather than a last resort for saving a failing sale. When your team leads with monthly payment options, they empower the customer to focus on the immediate benefits of the purchase rather than the weight of the total price. This shift in perspective is catalytic, turning a potential budget barrier into a manageable path forward. It’s about moving the conversation from “Can I afford this?” to “How does this best fit my monthly budget?”
Reducing Friction with Instant Approvals
Seconds matter in the digital age. Multi-lender portals change the game by sending one application to 30+ lenders simultaneously. This technology ensures your customers receive the highest possible approval rates in real-time, often with a soft-pull that protects their credit score. Capturing that initial impulse to buy is critical; if a customer leaves to “think about it” because of a slow or cumbersome approval process, the momentum is lost. For a deeper look at optimizing these specific moments in the sales cycle, see our Approve More Customers: Guide to Financing Conversions.
Marketing Your Financing Options
You can’t leverage the power of retail financing options if your customers don’t know they exist. Strategic placement of “Touch-n-Buy” assets like window clings, brochures, and digital banners ensures that flexibility is part of the customer journey from the first interaction. Messaging that highlights “0% Promotional APR” acts as a powerful magnet for budget-conscious shoppers looking for the best value. It’s a proven fact that 4 in 10 customers would choose to use financing if they were simply made aware of the option at the point of sale. Making your programs visible is the simplest way to unlock your business’s latent revenue potential.
Speak with a consultant about your enrollment today
Unlocking Growth with ZipLoan’s Multi-Lender Platform
The Technology Behind the 100% Approval Program
How do we capture the 60% of customers typically declined by traditional banks? Our technology instantly routes applications to the lenders most likely to approve them based on specific credit criteria and historical data. You don’t have to manage these relationships individually; the system does the heavy lifting for you. The merchant dashboard provides a clear, real-time view of every application, allowing you to track loans from submission to funding with total transparency. This level of insight is a cornerstone of any successful high-ticket sales strategy for 2026. By removing the mystery from the lending process, you gain the confidence to pitch larger projects to every customer who walks through your door.
Getting Started with ZipLoan
Joining the platform is a straightforward, frictionless process designed for busy business owners who value their time. Merchant enrollment is free, with no hidden fees or complex contracts designed to trap you in a restrictive partnership. Once onboarded, you gain immediate access to our professional suite of growth tools, including an integrated APR calculator and high-impact marketing assets. These resources help you communicate the value of your retail financing options clearly and effectively to your clientele. Our team is ready to act as your expert guide, helping you bridge the gap between your current sales volume and your idealized future. Contact our team to start offering financing and discover how a partnership built on mutual success can redefine your business’s trajectory.
Secure Your Competitive Edge in the Future of Retail
Mastering retail financing options is no longer just a perk; it’s a fundamental requirement for scaling in 2026. You’ve seen how bridging the gap between total price and manageable payments can recover nearly half of your lost sales. By moving away from restrictive single-lender models, you unlock the latent potential of every customer who walks through your door. Providing instant approvals up to $65,000 ensures that even your most ambitious projects get the green light without delay. With funds delivered within 24 hours, your operational cash flow remains as fluid as your sales process. Achieving approval rates over 85% means you can finally stop turning away viable customers and start building long-term brand loyalty.
Transforming your checkout experience is the key to removing the final barriers to your success. When you empower your shoppers with purchasing power, you aren’t just closing a deal; you’re facilitating their idealized future. This proactive approach positions your brand as a visionary leader in your industry and a true partner in your customers’ lives.
The breakthrough your business has been waiting for is just a few clicks away. Step into a future where every transaction is an opportunity for mutual growth and boundless expansion.
Frequently Asked Questions
What are the most common retail financing options for small businesses?
Choose between installment credit, lease-to-own programs, and private label revolving credit to best suit your specific sales model and customer needs. These structures empower your customers to manage their budgets through fixed monthly payments or flexible lines of credit that encourage repeat visits. By offering diverse retail financing options, you remove the financial barriers that typically prevent high-ticket sales from closing in a competitive market.
How does offering financing to customers affect my business’s credit risk?
Eliminate your credit risk entirely by partnering with a platform that handles the underlying debt and customer collections. Modern financing solutions operate on a zero-risk basis for the merchant, meaning the lender assumes all responsibility for the repayment schedule. You receive the full purchase amount upfront, which protects your business from the negative impact of customer defaults or late payments while ensuring consistent cash flow.
Can I offer retail financing if my customers have bad credit or no credit history?
Expand your market reach to include customers with credit scores as low as 550 through specialized lease-to-own programs and multi-lender platforms. These systems are designed to capture the 60% of shoppers typically declined by prime banks, ensuring that a thin credit file doesn’t stop a sale. This inclusive approach turns a potential rejection into a growth opportunity for a much larger portion of your target audience.
How long does it take for a merchant to get funded after a customer is approved?
Expect the delivery of funds into your business account within 24 hours of a completed and verified transaction. This rapid delivery of capital ensures that your business maintains the strength needed to cover immediate overhead, purchase materials, or pay labor costs. You won’t have to wait for the customer’s monthly payment cycle to begin before you realize the full financial benefit of the sale.
Is there a minimum or maximum transaction size for retail financing?
Scale your financing offers from $1,000 retail purchases up to $65,000 for major capital investments like home remodeling or elective medical procedures. This broad range ensures that whether you are fixing an emergency auto repair or replacing a roof, the financing fits the project size perfectly. Flexible terms stretching up to 20 years further enhance the long-term affordability and satisfaction for your customers.
Does applying for retail financing impact the customer’s credit score?
Utilize soft-pull pre-qualification technology to protect your customer’s credit score during the initial application phase. This allows shoppers to explore their retail financing options with total confidence and zero penalty to their historical record. A hard inquiry only occurs if they choose to accept a specific offer, making the entry point into your sales funnel entirely frictionless and building immediate trust.
What is a merchant discount fee and how is it calculated?
Calculate the merchant discount fee as a 2.99% fixed percentage of the total transaction value. This fee covers the cost of the lender’s risk and the administrative platform, and it is deducted automatically before your funds are delivered within 24 hours. It is a predictable cost of doing business that effectively replaces the uncertainty of traditional collections or the high cost of lost sales.
How do I integrate retail financing into my existing point of sale system?
Integrate financing into your existing workflow using simple web-based portals, QR codes, or text-to-apply links. These “Financing in a Box” solutions require no complex hardware and can be deployed instantly alongside your current retail payment processing tools. This digital-first approach allows customers to apply privately on their mobile devices, maintaining the professional speed and efficiency of your checkout experience.