
Customer financing fails the moment your team treats it as an emergency backup plan. When reps only pitch monthly payments after a buyer balks at the total price, they project hesitation instead of value. Properly training sales staff to offer financing transforms this dynamic entirely, turning payment terms from a defensive reaction into a proactive consultative tool that builds immediate trust.
You already know the frustration of watching high-ticket deals stall simply because reps dread awkward credit conversations or confusing application workflows. It’s painful to see capable staff default to traditional credit cards and lose sales they should have won, all because they fear putting a customer on the spot at the point of sale.
This comprehensive guide will show you how to equip your team to introduce financing options early, handle objections effortlessly, and close larger deals with confidence. We explore proven scripts, modern pre-qualification tactics, and the exact step-by-step framework you need to turn payment options into an engine for business growth.
Key Takeaways
- Effective training sales staff to offer financing starts with reframing flexible payment terms as customer buying power rather than an awkward debt pitch.
- Discover how introducing low monthly estimates during early product discovery expands purchasing budgets and prevents price resistance before it begins.
- Master conversational scripts that tackle common customer friction points, turning objections like “I don’t need credit” into cash-flow preservation opportunities.
- Remove point-of-sale friction by implementing private QR codes and text-to-apply links that allow shoppers to pre-qualify discreetly on their own smartphones.
- Boost team confidence by transitioning to a multi-lender platform that secures approvals exceeding 85%, eliminating the fear of embarrassing declines.
Why Sales Teams Hesitate to Offer Financing (and What It Costs You)
Most business owners view point-of-sale customer financing as a straightforward payment mechanism. High-performing organizations see it differently: financing functions as an upfront buying-power tool rather than a debt product. When representatives fail to introduce flexible payment terms early in a standard sales process, customer purchasing power stays restricted to available liquid cash. Integrating installment credit transforms how shoppers perceive affordability across big-ticket purchases.
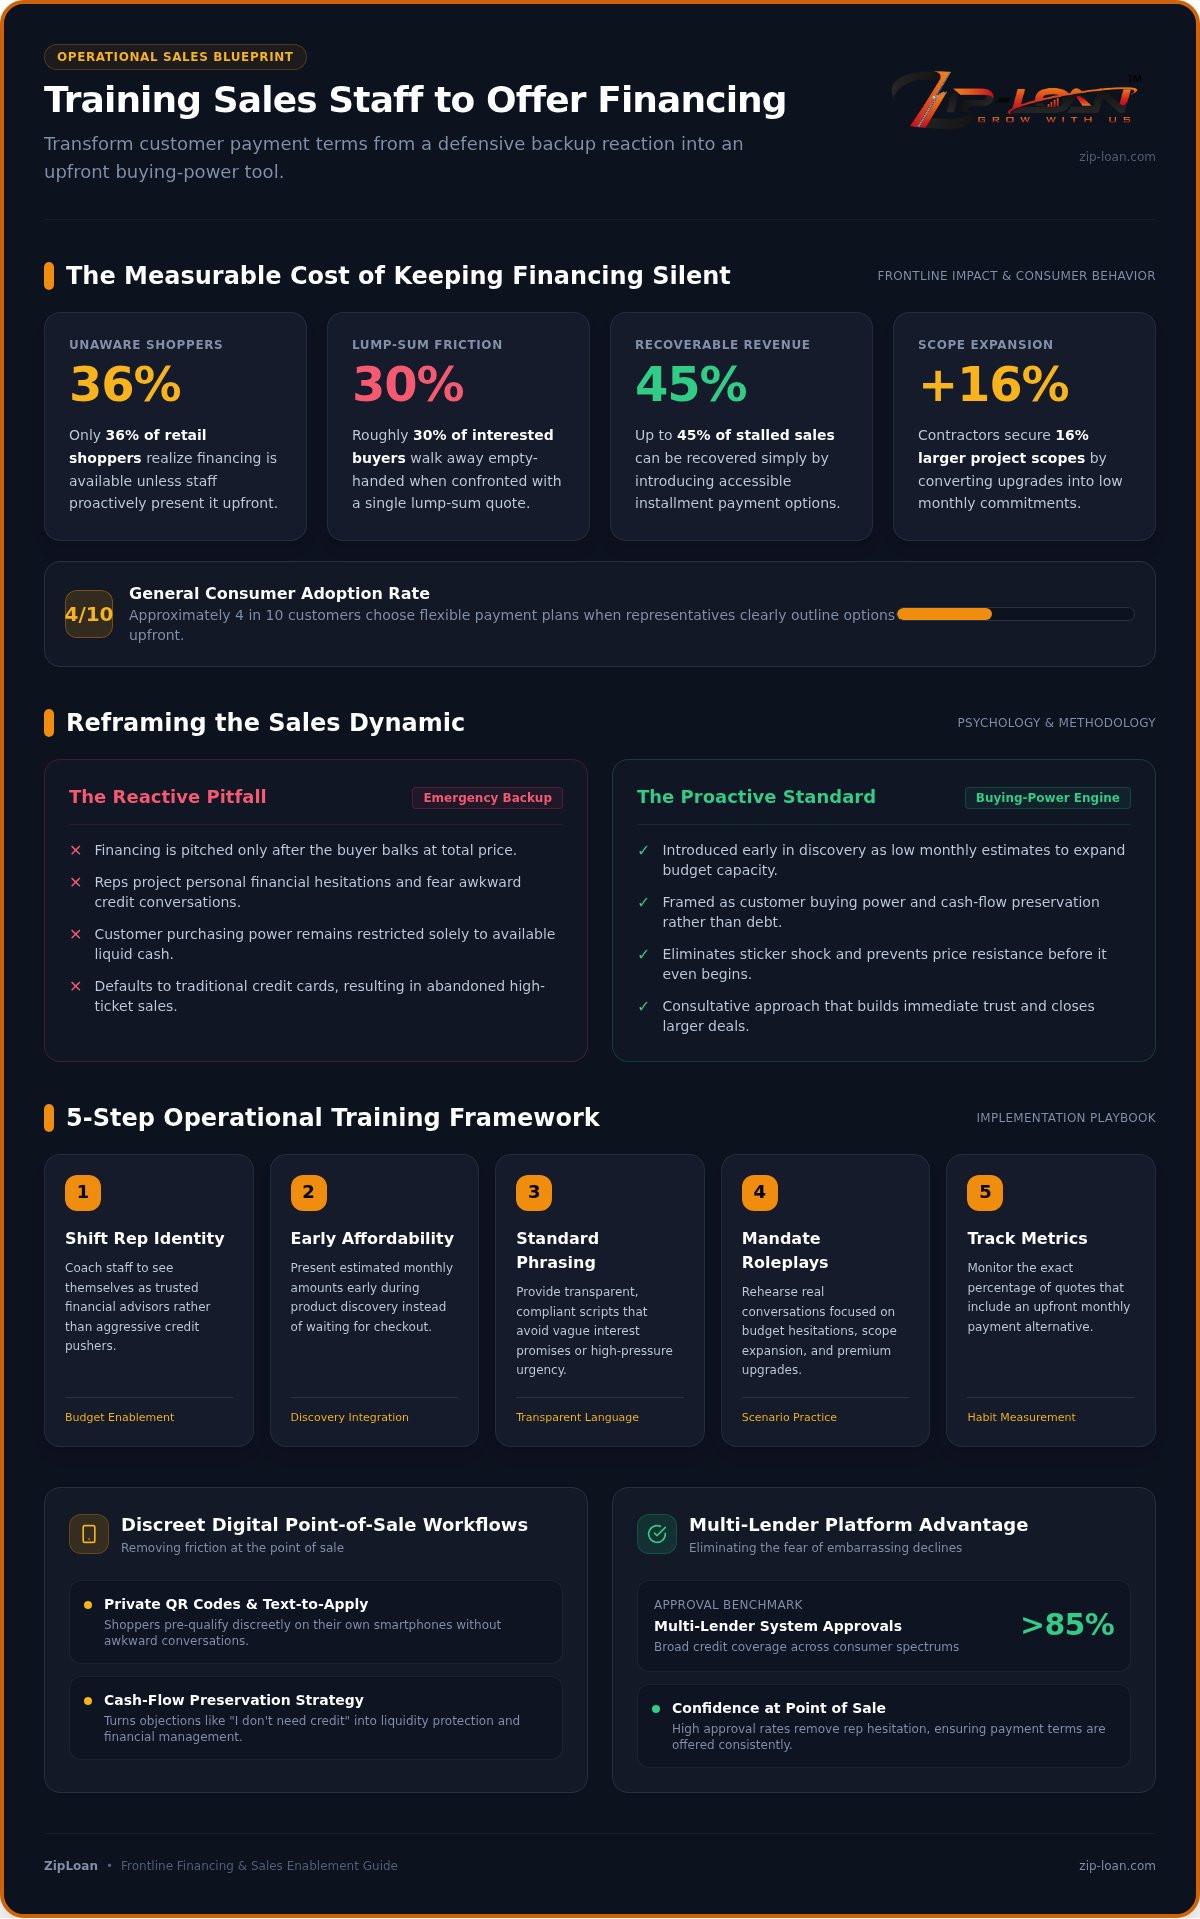
Staff members frequently keep quiet because they assume buyers will feel insulted by an offer to finance. That assumption is costly. Market research indicates that only 36% of retail shoppers realize financing is an option unless a representative proactively presents it. When staff conceal flexible payment options until final checkout, customers experience severe price shock. Equipping your frontline team through comprehensive training sales staff to offer financing shifts this dynamic, preventing immediate deal abandonment. In fact, up to 45% of stalled or abandoned sales can be recovered simply by presenting accessible installment options.
To see how top closers naturally introduce payment structures during the sales conversation, watch this breakdown:
The Psychology Behind Sales Rep Avoidance
Frontline reps routinely assume that customers prefer paying via cash or traditional credit cards. In reality, representatives project their own personal financial hesitations onto prospects. Reps dread the social awkwardness of a declined application, choosing complete silence over potential embarrassment. Effective education reframes point-of-sale financing as an essential budget enablement skill. When reps realize payment options protect customer cash flow, hesitation disappears.
The Measurable Cost of Keeping Financing Silent
Remaining silent on monthly payment alternatives drains revenue across every channel:
- Higher abandonment rates: Roughly 30% of interested buyers walk away empty-handed when confronted with a single, intimidating lump-sum quote.
- Contracted project sizes: In-depth training sales staff to offer financing empowers contractors to secure 16% larger project scopes by converting major upgrades into low monthly commitments.
- Missed consumer adoption: Approximately 4 in 10 customers choose flexible payment plans when representatives clearly outline options upfront.
A 5-Step Framework for Training Sales Staff to Offer Financing
Transforming your sales team into payment-confident consultants requires a repeatable operational playbook. Relying on casual reminders during team meetings won’t change frontline behavior. To achieve consistent results, execute this five-step curriculum:
- Shift rep identity: Coach staff to see themselves as financial advisors rather than aggressive credit pushers.
- Introduce early affordability: Present estimated monthly amounts early during product discovery rather than saving numbers for closing.
- Standardize transparent phrasing: Provide clear, compliant language that avoids vague interest promises and eliminates high-pressure urgency.
- Mandate practical roleplays: Rehearse real-world conversations focusing on budget hesitations, scope expansion, and premium upgrades.
- Track presentation metrics: Monitor the exact percentage of customer quotes that include an upfront monthly payment option.
A systematic methodology turns ad-hoc pitches into an embedded operational habit across your entire organization.
Introducing Monthly Payments Early in the Sales Conversation
Train your team to open discovery calls by exploring overall investment parameters. Instead of asking, “What is your total budget?”, teach reps to ask, “What monthly range feels most comfortable for this project?”
Framing purchases around monthly installments immediately removes price friction on premium tiers. When reps quote a comprehensive package, have them present the monthly figure side-by-side with the lump-sum total. Reviewing the foundational concepts behind why financing works helps reps understand how low installment breakdowns expand buying power without eroding margins. If a merchant experiences a 15% increase in average ticket size through installment credit, it stems directly from reps framing total scope around digestible monthly terms from minute one.
Structuring Roleplay Sessions That Build Frontline Confidence
Skill acquisition accelerates through deliberate practice. Pair emerging reps with seasoned closers twice weekly to master natural conversational pivots. These structured rehearsals should focus specifically on overcoming customer objections when prospects reflexively ask for price discounts.
Equip reps with exact phrasing:
- “Most of our clients keep their cash reserves intact by taking advantage of our flexible installment credit options. We can easily spread this across manageable monthly payments so you don’t compromise on project quality.”
- “Before we trim down the project scope to meet a cash target, let’s look at how an affordable monthly breakdown keeps every feature you actually want.”
Combine verbal drills with direct hands-on practice in your point-of-sale software. Reps who know how to generate an estimate in under thirty seconds never hesitate at the counter. When you commit to structured training sales staff to offer financing, your team stops conceding margin and starts closing larger deals with authority.
Overcoming Common Customer and Employee Objections Around Credit
Friction at the point of sale rarely stems from interest rates alone. More often, it arises because neither the customer nor the representative knows how to navigate payment discussions without awkwardness. When frontline staff lack objection-handling frameworks, they retreat into silence the moment a buyer hesitates. Comprehensive customer financing solutions give reps the verbal tools needed to reframe credit from an uncomfortable barrier into a strategic liquidity decision.
Targeted training sales staff to offer financing prepares your team to handle pushback calmly. When a shopper demands a steep cash discount, an untrained rep often caves and cuts into gross margin. A trained advisor, however, counters by showing how low installment structures deliver the same immediate monthly comfort without sacrificing the sale price.
Addressing the “I Prefer to Pay Cash” Hesitation
Buyers frequently announce, “I don’t need credit, I’ll just pay cash.” Sales representatives often take this as a hard dismissal and drop the topic immediately.
Teach your team to validate the buyer’s financial strength first, then introduce liquidity preservation. Reps can respond with a consultative pivot:
- “That makes total sense, and it’s great you have the capital ready. Many of our clients prefer to keep their cash in high-yield reserves or available for unexpected emergencies by taking advantage of our promotional same-as-cash terms for 12 months.”
Positioning installment terms as cash management appeals directly to financially savvy buyers. Rather than borrowing out of desperation, customers use zero-percent promotional windows as a calculated tool to protect everyday cash flow.
Removing the Fear of Credit Score Damage and Denials
Customer anxiety about credit checks runs parallel to employee anxiety about delivering rejections. Shoppers worry that exploring terms will trigger a hard credit inquiry and damage their credit score. Frontline staff, meanwhile, dread the social embarrassment of breaking bad news to an applicant.
Eliminate both concerns by teaching the mechanics of modern digital applications. Train reps to emphasize that soft-pull pre-qualification allows buyers to review rates with zero score impact. Recent consumer finance market analysis shows that frictionless, card-like checkouts dramatically lower buyer resistance across all ticket sizes.
Equally vital, staff need to know that robust multi-lender platforms approve over 85% of applicants, accommodating scores down to 550. When reps realize nearly nine out of ten customers get approved, their fear of an awkward denial evaporates. Through ongoing training sales staff to offer financing, conversations shift from high-risk interrogation to everyday customer service.
Integrating Digital Financing Tools into Everyday Point-of-Sale Workflows
Frictionless technology turns payment conversations from stressful interruptions into natural touchpoints. When sales reps have to fill out clunky paper forms or ask intrusive questions out loud, they abandon the process altogether. Equipping staff with scannable QR codes and direct text-to-apply links solves this operational bottleneck instantly. With digital workflows in place, comprehensive training sales staff to offer financing focuses on facilitating a quick, comfortable checkout rather than managing administrative red tape.
Modern point-of-sale setups give reps real-time visibility through clean merchant dashboards. Once a buyer clicks submit on their device, the advisor sees pre-approval totals, approved terms, and transaction statuses within seconds. Train staff to print physical estimate sheets, work orders, and invoices that automatically feature an estimated monthly payment line alongside the total invoice amount. This visual anchor guarantees every prospect sees affordable terms before signing.
Empowering Customers Through Private Mobile Pre-Qualification
Place scannable QR codes strategically across your physical location, including counter displays, desk plaques, and take-home brochures. Allowing buyers to scan a code and complete a soft-pull pre-qualification on their own smartphone safeguards their personal data. Staff never have to handle sensitive details like Social Security numbers or household income figures across a crowded showroom.
Self-guided mobile applications resolve privacy anxiety on both sides of the register. Over 90% of modern consumers expect immediate digital decisions when applying for payment options. When reps can simply say, “Scan this quick code to check your options without impacting your credit,” the barrier to entry disappears.
Aligning Point-of-Sale Workflows Across Industry Verticals
Execution looks different depending on the operational environment:
- Retail showrooms: Associates point out monthly installments on price tags, guiding buyers to scan desk codes while exploring options.
- Contracting and in-home trades: Estimators send a text-to-apply link directly to the homeowner’s phone during the initial consultation so approvals are ready before drafting the quote.
- Automotive repair facilities: Service advisors text estimated breakdown options alongside digital multi-point inspection reports before turning a wrench.
Adapting workflows across various industries we serve ensures that flexible terms become a natural operational standard rather than an afterthought. Seamless digital integration turns payment terms into a daily habit. Consistent training sales staff to offer financing guarantees your team leverages these digital assets on every single sales call.
Get started with Zip-Loan point-of-sale financing tools today
Scaling Business Revenue with Multi-Lender Systems and Ongoing Coaching
Single-lender financing setups quietly sabotage frontline motivation. When a business relies on a single underwriting provider, nearly 40% of applicants face outright rejection. Each declined application bruises rep confidence, making staff hesitant to present monthly options on future interactions. Connecting your business to a multi-lender network accessing 30 providers changes this dynamic completely. Securing approval rates above 85% gives your team the certainty required to present flexible terms on every single interaction.
Long-term revenue expansion requires pairing reliable lender infrastructure with continuous managerial coaching. Leaders who track financing presentation frequency alongside standard conversion ratios consistently outpace competitors who leave payment discussions to chance.
Why Multi-Lender Technology Protects Sales Team Morale
Sales representatives hold back when they fear point-of-sale friction. Traditional prime lenders enforce strict underwriting boxes, shutting out solid buyers who carry minor credit blemishes. In fact, over 60% of customers approved through multi-lender platforms were previously declined by prime financing institutions.
A multi-lender waterfall routes customer requests across 30 providers, securing approvals for credit scores down to 550 with credit limits reaching up to $65,000. Decisions arrive in seconds, protecting the momentum of the sales conversation. Because modern platforms transfer all non-payment risk and deliver merchant funding within 24 hours, staff can confidently pitch flexible terms without worrying about administrative fallout.
Developing a Sustainable Sales Coaching and Accountability Cadence
Lasting execution requires regular reinforcement. Run a weekly 15-minute pipeline review dedicated specifically to tracking how often reps present monthly payment options on high-ticket quotes. Review stalled estimates and analyze deals where financing went unmentioned, reinforcing how low installments protect customer cash flow.
Incentivize adoption by publicly celebrating team milestones. Highlight reps who secure the proven 15% increase in average ticket sizes through installment credit, or contractor partners who generate 21% more closed deals. Continuous coaching ensures staff treat flexible payments as a primary sales tool rather than a fallback.
Committing to ongoing training sales staff to offer financing aligns daily sales behavior with company expansion goals. When your team pairs consultative customer conversations with a multi-lender platform, you unlock predictable revenue growth on every ticket. Ready to empower your team? Contact our merchant financing specialists to complete your merchant enrollment and launch your program today.
Turn Payment Conversations into Your Greatest Growth Engine
Elevating your frontline team from transactional order-takers to trusted purchasing advisors unlocks immense revenue potential across every department. Structured training sales staff to offer financing replaces point-of-sale hesitation with repeatable, confident execution. When reps present accessible monthly terms early in the discovery phase, customer sticker shock disappears and average ticket sizes expand naturally.
Lasting success happens when your coaching framework is supported by reliable lending technology. Connecting your checkout counter to 30 integrated lenders secures approval rates exceeding 85%, ensuring reps don’t fear awkward customer declines. With scannable soft-pull pre-qualification protecting customer credit scores and instant funding delivering merchant capital within 24 hours with zero dealer risk, flexible payments become an effortless competitive advantage.
Equip your team with the operational fluency, practical scripts, and institutional backing they need to unlock higher close rates on every high-ticket opportunity.
Frequently Asked Questions
How do I get my sales staff to offer financing to every customer?
Make monthly payment estimates a non-negotiable line item on every quote and proposal rather than an optional add-on. Consistent training sales staff to offer financing involves tracking presentation rates during weekly team check-ins and celebrating reps who quote monthly terms upfront. When leaders pair clear accountability with intuitive tools like scannable QR codes, presenting payment options becomes an effortless, automatic habit for every rep.
Will customers be offended if my sales team offers financing?
No, buyers view payment flexibility as an empowering convenience rather than an insult when it is presented universally. Frame terms around smart cash flow management and liquidity preservation instead of financial hardship. Modern shoppers across all income levels routinely utilize promotional payment structures to keep cash reserves intact. When reps present options consistently to every client, it feels like standard premium customer service.
What is the best way to introduce financing during a sales conversation?
Introduce estimated monthly payments during the initial product discovery phase before discussing the total purchase price. Teach reps to ask, “What monthly investment range feels comfortable for this project?” rather than asking for an all-cash cap. Introducing flexible terms early eliminates price resistance before it forms, allowing customers to focus on product value and custom package upgrades rather than immediate bottom-line cost.
Does checking customer financing options impact their credit score?
No, exploring pre-qualification options through modern digital platforms utilizes a soft credit inquiry that has zero impact on credit scores. Customers can safely review available terms, credit limits, and promotional interest rates directly on their own smartphones before deciding to accept an offer. A formal inquiry occurs only after the customer selects a specific offer and completes the full agreement, protecting applicant credit profiles during the discovery phase.
How does offering financing increase my business ticket size?
Monthly payment options shift customer decision-making from a restrictive lump-sum budget to an accessible recurring expense. Comprehensive training sales staff to offer financing enables reps to bundle add-ons, premium upgrades, and extended service plans for just a few extra dollars each month. Merchants typically experience a 15% increase in average ticket size, while home improvement contractors report 16% larger overall project scopes when monthly options are visible.
What happens if a customer has bad credit or was declined elsewhere?
Multi-lender networks route customer applications across 30 distinct underwriting providers, approving individuals with credit scores as low as 550. Over 60% of Zip-Loan customers were previously turned down by prime lenders before finding approval on the multi-lender platform. Because secondary and tertiary lenders compete to fund transactions, overall approval rates exceed 85%, ensuring reps can help credit-challenged shoppers without awkward point-of-sale friction.